Goldman Sachs is directing investors concerned about artificial intelligence market dynamics toward defensive sectors, specifically health care and consumer staples stocks. According to reports from Goldman Sachs, this strategic recommendation comes less than a week after RBC Capital Markets cut tech to market weight on October 14, with RBC subsequently recommending health care as an alternative. The investment bank's call reflects growing concerns about the sustainability of AI-driven growth, particularly as rising interest rates create pressure on capital costs and market expectations.
Goldman's analysis centers on the impact of months of rate pressure that have raised concerns over capital cost structures. As reported by Goldman Sachs, analysts led by Ben Snider noted that a sharp reduction in investor positioning has amplified equity market moves, leading to lower growth expectations across the market. The bank's cyclicals versus defensives pair fell 6% in the past 2 weeks, demonstrating how defensive sectors are outperforming cyclical ones. Goldman estimates that AI capital spending drives about half of S&P 500 earnings growth, with expectations that this share will shrink as spending growth slows.
Goldman's defensive shortlist includes 23 health care and staples names with low volatility and high free cash flow yields. According to the bank's analysis, Tyson Foods leads with the highest free cash flow yield at 11% over the trailing 4 quarters, despite shares falling nearly 8% since the start of 2026. Other notable performers include Royalty Pharma with +56.0% year-to-date performance, CVS Health with +16.8%, and JM Smucker with +29.9%. The portfolio spans various defensive sectors including pharmaceuticals, food companies, and consumer goods, with most stocks showing positive year-to-date returns. Recent performance data shows Quest Diagnostics leading with +35% year-to-date, followed by US Foods Holding Corp at +34%, and Hormel Foods at -12%.
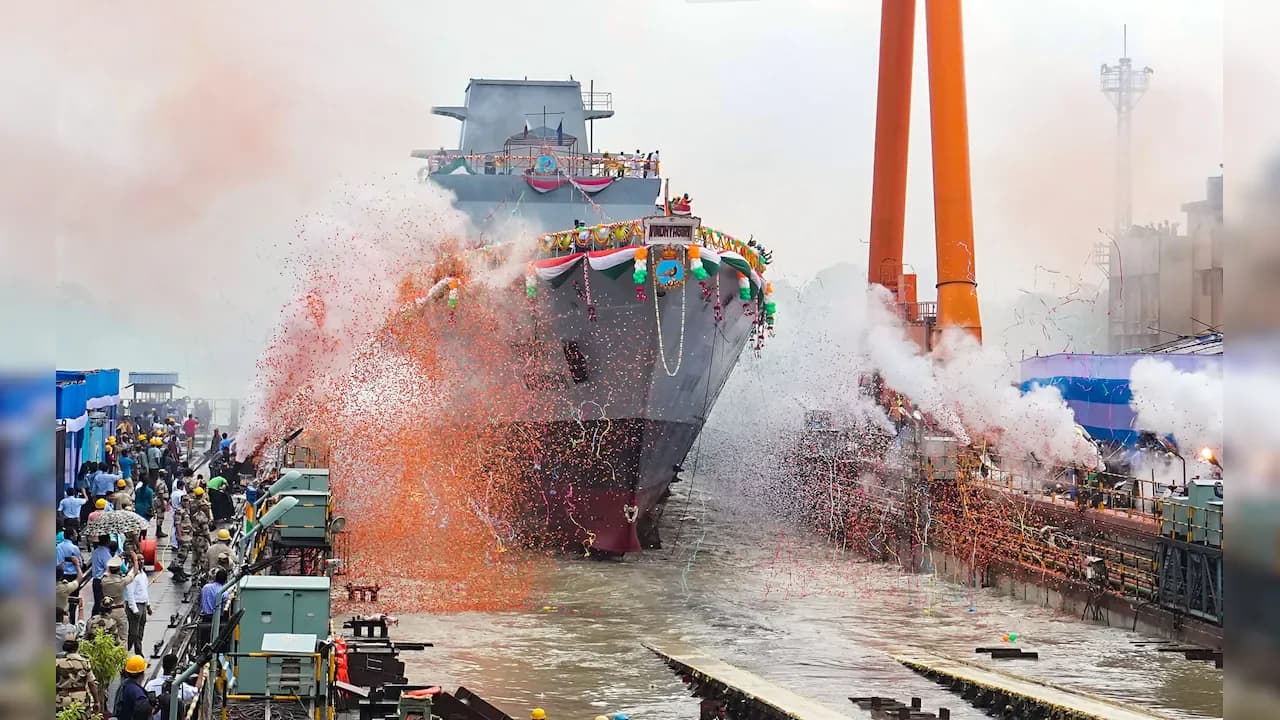
Goldman Sachs has initiated coverage on two shipbuilding companies with 'sell' ratings and specific price targets, citing earnings risks from delayed naval orders. The firm has set a price target of ₹1,855 for Mazagon Dock, indicating a 9.7% downside from current levels, while for Garden Reach Shipbuilders, it has a target of ₹1,515, which indicates a 27.4% downside potential. According to The Financial Express, both companies are approaching the end of major delivery programmes with trailing book-to-bill ratios at cyclical lows - 1.37 times for Mazagon Dock and 1.81 times for GRSE. Goldman Sachs expects EBITDA at the two shipbuilders to decline at a compound annual growth rate (CAGR) of 19.3% between FY26 and FY29, compared with projected growth of 26% for other aerospace and defence companies under coverage.
Goldman expects S&P 500 earnings growth to cool from around 29% in 2026 to 18% in 2027, as reported by the investment bank. The bank's economists anticipate that weaker energy prices and falling rates in 2027 will lift household spending and benefit lagging consumer-facing stocks. Goldman strategists noted that health care has typically been among the best-performing parts of the S&P 500 when growth is positive but slowing, supporting their defensive positioning strategy for investors concerned about market volatility.