Nomura has reiterated its 'Buy' rating on Ather Energy and raised its target price to ₹1,470 from ₹1,120, calling the electric two-wheeler maker its 'top pick to ride on EV inflection.' The revised target price implies an upside potential of 22.5% from the stock's previous closing price of ₹1,200 on the NSE. The brokerage expects electric two-wheeler penetration in India to rise from around 6.5% in FY26 to nearly 19% by FY30, higher than its earlier estimate of 16%, implying a volume CAGR of around 40% over FY26-FY30. Nomura believes Ather, being a pure-play electric two-wheeler company, is well positioned to benefit from this structural shift towards electric mobility, maintaining its market share at around 18% in FY26 despite being supply constrained.
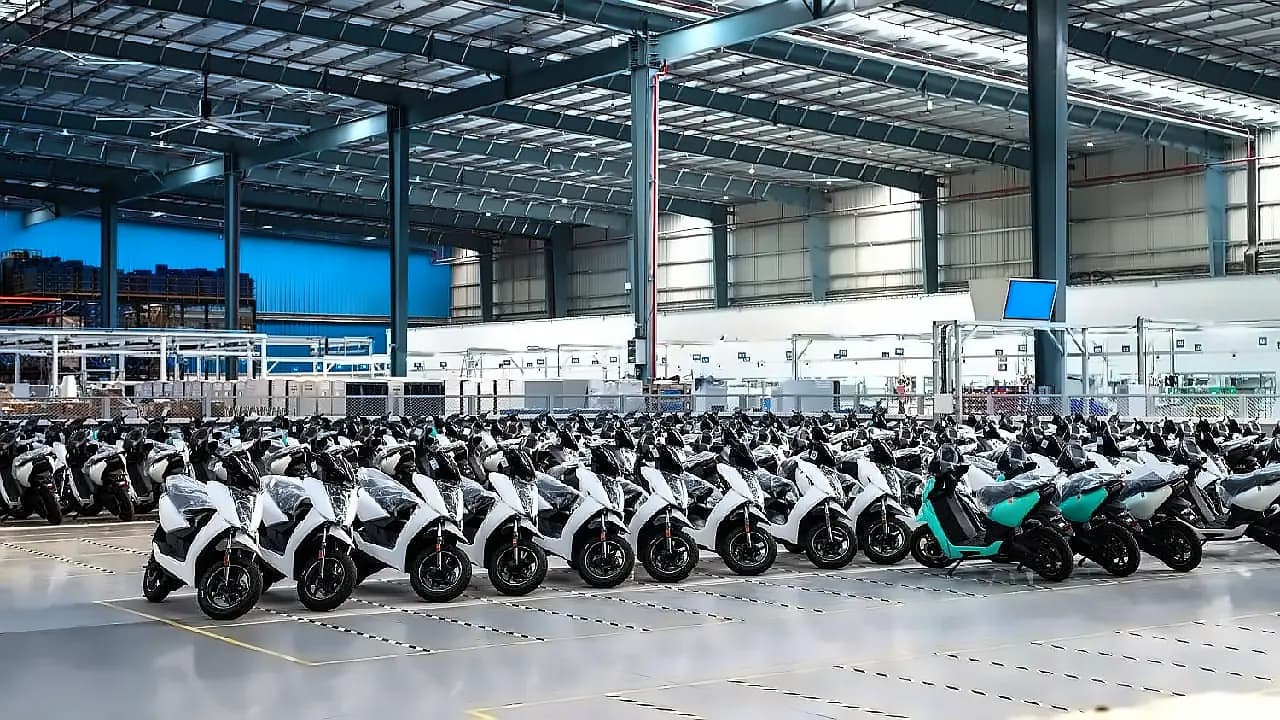
Nomura has significantly raised its volume estimates for Ather Energy, maintaining its FY27 volume estimate at 3.99 lakh units, representing 53% year-on-year growth, while raising its FY28 estimate to 6.22 lakh units from 5.10 lakh units earlier. The brokerage has also introduced an FY29 forecast of 8.24 lakh units, implying another 32% year-on-year increase. Despite expecting a weaker product mix, Nomura expects average selling prices to increase by around 2% as the company passes on higher commodity costs through price hikes. The brokerage forecasts revenue growth of 54%, 57% and 36% over FY27F/28F/29F respectively, with EBITDA margins expected to improve from negative 6% in FY27 to 5.1% in FY29, with the company likely to achieve PAT breakeven in FY29. Nomura believes Ather's long-term margin potential remains in the 15-20% range.
Ather Energy's upcoming affordable scooter based on the EL platform, scheduled for launch from the third quarter of FY27, along with a new manufacturing plant, is expected to help the company tap the ₹1 lakh-₹1.25 lakh price segment, which accounts for around 45% of the industry. Nomura believes the successful launch of Ather's new motorcycle platform could provide additional upside to its estimates. The brokerage has factored in some moderation in EV demand as fuel price risks linked to the Middle East conflict have eased, but notes that if fuel prices remain elevated, there could be further upside to its forecasts. Despite expecting a weaker product mix, Nomura believes the current valuation at 4.0x FY28F EV/sales is attractive given the company's growth outlook, maintaining its premium valuation at 5-7x EV/sales.
Ather Energy shares have delivered exceptional returns, gaining more than 4% in one week and 16% in one month. The stock is overall up around 62% in 2026 so far and has surged 270% in one year. The company currently has a market capitalisation of nearly ₹46,480 crore. The stock made a muted debut on Indian exchanges in May last year, listing at ₹328 per share on NSE, marking a premium of 2.18% over the IPO price. The shares then soared a whopping 273% to hit a fresh 52-week high of ₹1,222.10. Nomura projects strong revenue growth of 54%/57%/36% over FY27F/28F/29F respectively, with EBITDA expected to improve and PAT breakeven anticipated in FY29.
According to Religare Broking's Ajit Mishra, three major stock recommendations have been issued for Thursday, July 9. Ather Energy and Sun Pharma are recommended as buys while ITC is recommended as a sell for futures trading. The recommendations are based on technical analysis showing breakout patterns and momentum indicators across different sectors. Sun Pharmaceutical Industries Limited is recommended as a buy with a current price of ₹1,888.20 and a target price of ₹2,025, while ITC Limited is recommended as a sell for futures trading with a current price of ₹281.50 and a target price of ₹264.