India's solar manufacturing sector is facing a severe cost crisis with commodity prices surging dramatically across the board. According to NDTV Profit, Premier Energies CBO Vinay Rustagi reported that all commodity costs are up between 10% to 30, 40, and even 50% in some cases, creating tremendous pressure on manufacturers. The company expects to largely protect its margins despite the sharp rise in input costs, but smaller and non-integrated solar manufacturers are likely to be hit harder, with the pain described as "much more acute" for these players. Rustagi noted that "there is tremendous pressure on all the commodity costs, be they metals, polymers, the freight costs," calling it a challenge for all manufacturers to mitigate the impact and maintain profitability.
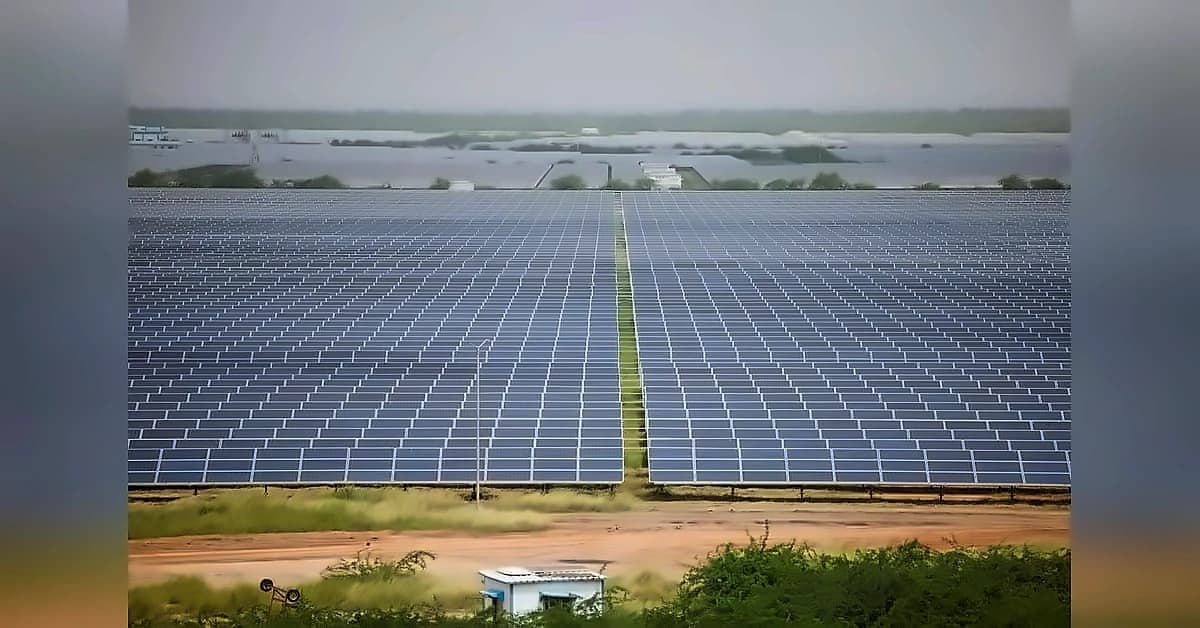
India's solar manufacturing landscape shows a significant imbalance between module and cell production capabilities. According to a Mercom India report, India added 50.6 GW of solar module capacity against 9.7 GW of cell capacity in the first six months of 2026, with module capacity additions accounting for more than five times those of solar cells. By the end of June, India's cumulative solar module manufacturing capacity reached 261.7 GW while solar cell manufacturing capacity stood at 36.6 GW, highlighting the increasing disparity between the two stages of the solar manufacturing chain. However, with India implementing the second phase of its approved-models list for cells, approximately 75% of the demand is going to be served by domestically made cells, as reported by NDTV Profit, which could significantly improve the domestic supply situation.
The widening capacity gap has resulted in increased reliance on imported components to meet domestic solar energy requirements. As reported by Mercom India, imports of solar cells and modules rose 18 per cent in H1 2026 from a year earlier, with solar cells accounting for 81 per cent of total imports while modules made up the remaining 19 per cent. This growing import dependency reflects the current manufacturing imbalance in India's solar sector, with the industry increasingly relying on imported cells to meet domestic requirements. The cost crisis has made this dependency even more challenging, with companies like Premier Energies noting that "the pain will be much more acute for smaller players and the players who are not integrated."
India's solar manufacturing capacity is highly concentrated in specific states, with Gujarat accounting for nearly 45 per cent of the country's module manufacturing capacity and more than 36 per cent of solar cell manufacturing capacity. According to the Mercom India report, Rajasthan and Tamil Nadu ranked second and third respectively in module manufacturing capacity, together accounting for nearly 19 per cent of India's total module capacity. This geographic concentration creates both opportunities and challenges for the sector's development, with manufacturing capacity heavily concentrated in a few key states. The concentration becomes particularly significant during cost crises, as companies with larger scale operations are better positioned to absorb cost pressures and maintain profitability.
The solar manufacturing sector is experiencing some positive price movements despite capacity challenges. As reported by Mercom India, the average selling price (ASP) of Indian mono PERC modules fell 1.8 per cent quarter-on-quarter, indicating some price pressure in the market. Additionally, India's module manufacturing capacity is concentrated among a relatively small number of companies, with the top 10 manufacturers accounting for about 60 per cent of the country's total capacity, suggesting a consolidated industry structure that may influence pricing dynamics in the sector. However, demand for solar in India continues to be strong, with rooftop solar "absorbing the impact and in fact scaled up demand even further," as noted by NDTV Profit. The company's order book was about ₹15,000 crore last quarter with "very strong" order intake in the current quarter.