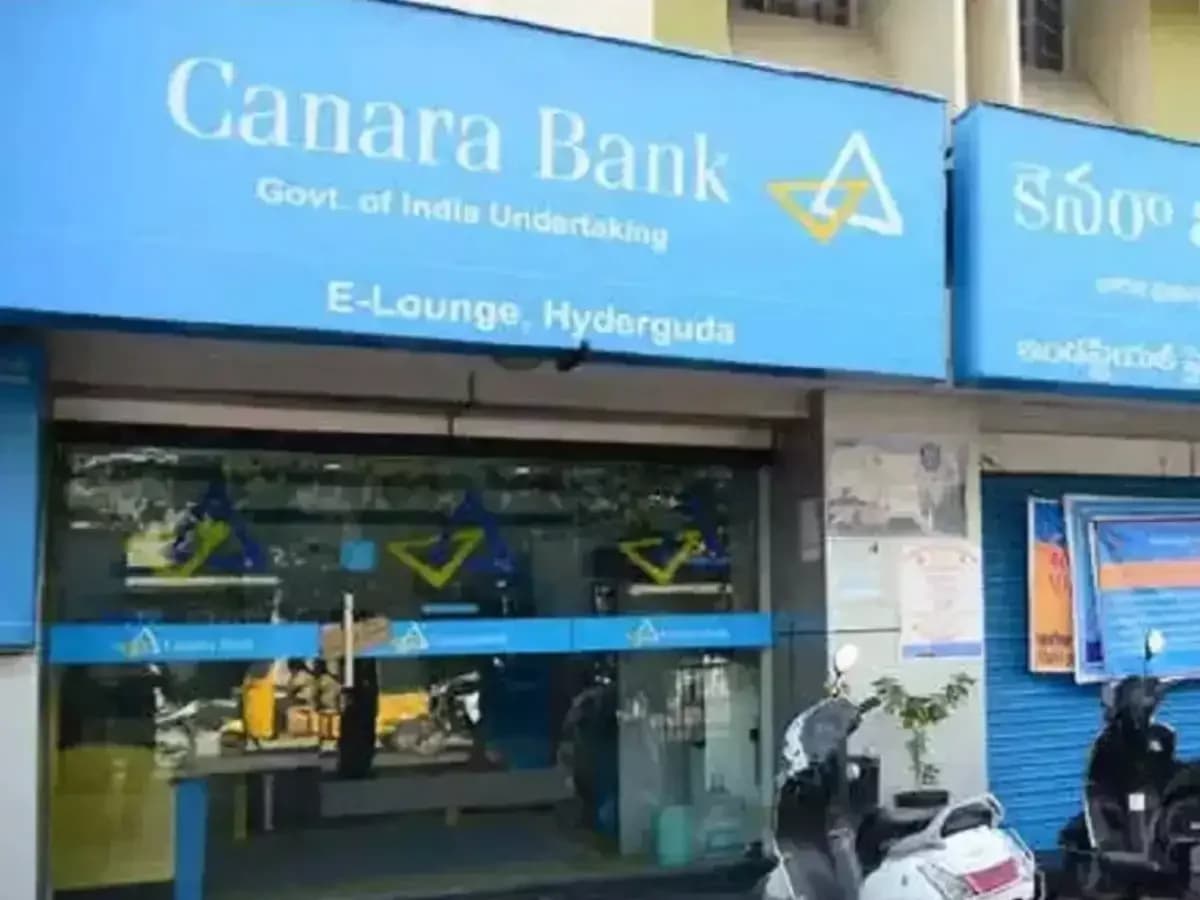
The Insurance Regulatory and Development Authority of India (IRDAI) has imposed a ₹1 crore penalty on Canara HSBC Life Insurance Company for mis-selling a deferred annuity policy to an 88-year-old individual. According to IRDAI's press release dated September 10, 2026, the proceedings were initiated after the authority took suo-motu cognizance of a social media post and sought explanations from the insurer. The policy carried an annual premium of ₹2 lakh for four years and was sold through the insurer's corporate agent, Canara Bank. The customer's daughter was shown as the annuitant in the transaction.
IRDAI identified multiple procedural and disclosure deficiencies in the sales process that led to the penalty. As reported in the press release, the regulator found that the approved product specified an entry age of 30-80 years while the proposer was 88 years old. The competent authority also determined that adequate suitability and financial assessment had not been undertaken despite the customer's advanced age and the significant premium commitment. Additional deficiencies included the benefit illustration lacking verifiable acknowledgement by the policyholder, customer information sheet and proposal form copies not provided at point of sale, premium collection before policy issuance, and inadequate disclosure of consequences if the proposer died during the premium-paying term. According to Moneycontrol, the regulator flagged several shortcomings in the sale, including failures related to product suitability, solicitation, disclosures and the insurer's internal controls.
Following the regulatory action, Canara HSBC Life Insurance Company subsequently refunded the full premium of ₹4.09 lakh to the affected customer, including the second-year premium and reversed commission. According to IRDAI's press release, the insurer met with the policyholder at his request and provided this compensation. The refund amount represents the total premium paid by the customer for the deferred annuity policy.
Beyond the refund, Canara HSBC Life Insurance Company has undertaken comprehensive corrective measures to address the regulatory violations. As reported in the press release, the insurer revised its product brochure, policy document and suitability assessment framework. Additionally, the company introduced pre-issuance video-based validation calls to strengthen its verification processes. These measures demonstrate the insurer's commitment to improving its sales practices and ensuring better policyholder protection.
The regulatory action against Canara HSBC Life Insurance highlights critical safeguards that senior citizens should follow to protect themselves from insurance mis-selling. According to Business Standard, elderly citizens are particularly vulnerable due to their trust in banks and large fixed-deposit holdings that make them easy targets for high-margin products. Key protection measures include understanding product features such as distinguishing premium-payment terms from policy terms, checking the actual internal rate of return, and using the 30-day free-look period to examine policies thoroughly. Senior citizens should also avoid rushed purchases, seek independent fee-only advice, and preserve all documentation including proposal forms, benefit illustrations, and complaint records.