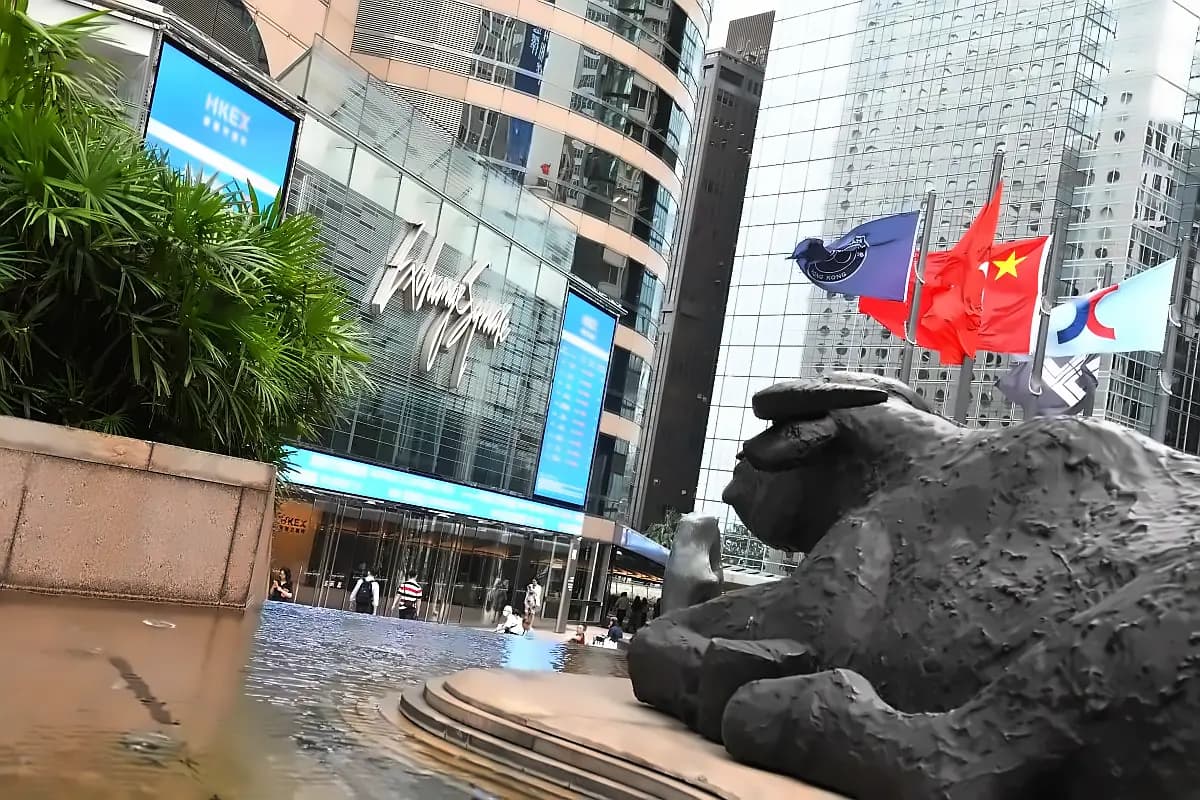
Chinese equity markets declined on Wednesday, with the CSI 300 Index falling 1.3% and the Shanghai Composite Index dropping 0.8%, according to The Economic Times. The weaker performance came as investors faced renewed concerns about global economic conditions, with rising oil prices and higher bond yields dampening sentiment. The Hang Seng Index in Hong Kong also declined 1%, while the Hang Seng Tech Index lost 1.5%, reflecting broad-based weakness across Asian markets. The decline followed overnight declines on Wall Street as a global bond selloff intensified, with the 10-year U.S. Treasury yield climbing to its highest level since 2023.
Technology stocks emerged as the biggest drag on Chinese markets, with Foxconn Industrial Internet falling 2.93%, SMIC dropping 2.01%, CATL losing 1.50%, and NAURA Technology declining 4.59%, as reported by Business Standard. The CSI Semiconductor Index also dropped 2%, reflecting continued weakness across the technology segment. The Shanghai's technology-focused STAR50 Index was down 1.32%, while the smaller Shenzhen index dropped 1.27% and the ChiNext Composite Index, which tracks startup companies, declined 2.18%. This decline comes despite earlier concerns over potential US policy measures against China, including US President Donald Trump's indication that Chinese banks could face sanctions and reports of a possible 7.5% US tariff on Chinese goods.
Higher crude prices have raised concerns that renewed inflationary pressures could complicate the outlook for monetary policy, as reported by The Economic Times. Rising bond yields also tend to weigh on equities by increasing borrowing costs and reducing the relative attractiveness of risk assets. Gold-related stocks were among the biggest losers in China, with the sector falling about 3%, as gold equities are particularly sensitive to changes in interest-rate expectations because higher yields can reduce the appeal of non-yielding assets. The combination of elevated oil prices and rising bond yields has created a challenging environment for risk assets globally.
Despite market weakness, China's manufacturing sector showed signs of improvement, with the private Caixin PMI rising to 51.5 in August from 50.9 in July, beating expectations of 51.0, according to Business Standard. The official manufacturing PMI also improved to 49.8 from 49.2, indicating that the manufacturing sector is expanding after contracting in the previous month. This improvement in manufacturing data provides some positive economic indicators for Chinese markets, though it has not been sufficient to offset the negative sentiment from global economic concerns.
Despite technology weakness, defensive sectors helped cushion overall market losses, with liquor, consumer staples and banking stocks gaining during the session, according to The Economic Times. The defence stocks, however, outperformed the broader market, providing some stability amid the broader decline. Analysts noted that market sentiment was expected to remain cautious, with trading likely to stay range-bound due to a relatively quiet earnings period and uncertainty over the timing of a potential meeting between Chinese and US leaders. The combination of modest domestic economic recovery and an uncertain global rate environment continues to encourage investors to favor defensive assets over growth-oriented stocks.