China's factory-gate prices returned to growth in March for the first time in more than three years, signalling the emergence of fresh cost pressures in the world's second-largest economy. According to data from the National Bureau of Statistics (NBS) released on April 10, the producer price index (PPI) increased 0.5% year-on-year, ending a prolonged 41-month streak of declines that began in late 2022. The uptick, which slightly exceeded market expectations from a Reuters poll forecast of 0.4%, reverses the contraction recorded in February and marks a turning point for industrial price trends. As reported by NBS senior statistician Dong Lijuan, the increase is attributed to factors including a rapid surge in global commodity prices as well as an improved supply-demand relationship in certain domestic industries. The recovery has been particularly pronounced in energy-intensive sectors, with non-ferrous metal mining recording a 36.4% jump in March and non-ferrous metal smelting and processing posting a 22.4% rise.
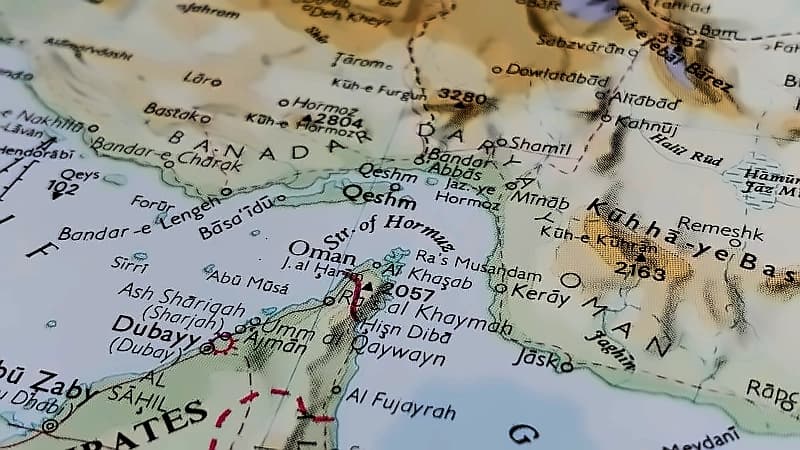
The increase in factory-gate prices has been particularly pronounced in energy-intensive sectors, with prices in non-ferrous metal mining surging sharply while smelting and processing industries recorded strong gains. According to Reuters, higher crude oil prices — driven by Middle East tensions, firmer global demand and speculative buying — were a key factor behind the anticipated rebound in factory-gate prices. The disruption of global energy flows by the conflict in the Middle East is still driving up costs for producers, with China already raising petrol prices three times by roughly a quarter since the war started. While China is more immune to oil shocks after years of investment in renewables and efforts to secure stable supplies, the war's impact is evident in the petroleum and natural gas extraction sector seeing prices rise 5.2%, though this was offset by a 4.5% decline in the refining industry, reflecting slower transmission of cost increases to downstream sectors. As per the NBS, imported inflation also contributed to the PPI rise, pushing up prices or narrowing declines in related sectors.
Manufacturers are already finding it difficult to pass on higher costs to buyers and could end up with even thinner profits as the inflationary pressures mount. According to the latest NBS data, purchase prices of raw materials rose 0.8% from a year ago — faster than the 0.5% gain in their selling prices, indicating pressure on corporate margins. The petroleum and natural gas extraction sector saw prices rise 5.2%, while transportation and communication costs became 0.9% more expensive than a year ago — the fastest gain since January 2023. The cost of energy needed to power vehicles rose 3.4% in March, reversing a contraction of 9% in the previous month. Economists warn that a shift to inflation driven by higher costs rather than stronger demand could leave Beijing boxed in, squeezing corporate margins, crimping growth and narrowing room for stimulus. Imported inflation leaves firms with little buffer if they are unable to pass on higher input costs, squeezing margins, investment and hiring, as noted by economists.
Despite the producer price recovery, consumer-side inflation showed signs of moderation with the consumer price index (CPI) ticking up 1% year-on-year in March, down from 1.3% in February, reflecting weaker domestic demand after the Lunar New Year period. According to Reuters, economists polled by Reuters had expected prices to climb 1.2%, making the actual reading slightly better than forecasts. On a monthly basis, CPI fell 0.7% compared with forecasts for a 0.2% decline, following a 1% rise in February. Core CPI, excluding food and fuel, grew 1.1% year-on-year, versus a 1.8% rise in February, indicating that underlying price pressures remain relatively contained despite the pickup in producer prices. Food prices, particularly pork, declined significantly due to ample supply and reduced seasonal demand, with pork prices alone dropping around 10% month-on-month. Meanwhile, Chinese consumers are feeling the pinch, with their transportation and communication costs becoming 0.9% more expensive than a year ago — the fastest gain since January 2023.
Economists caution that this shift towards cost-push inflation could complicate China's economic outlook, as rising input costs tend to squeeze corporate profit margins and weigh on growth. Wu Ge of Changjiang Securities cautioned that the rebound in factory prices does not necessarily indicate a broad improvement in corporate profitability, noting that the increase is largely driven by external factors such as supply shocks and base effects rather than sustained demand growth. The divergence between rising producer prices and easing consumer inflation points to uneven economic momentum in China, where manufacturers face increasing cost pressures while consumer demand has yet to fully recover. Domestic car sales fell for a sixth straight month in March, as rising fuel prices dampened demand for petrol-powered models while electric vehicle sales continued to feel the impact of reduced incentives. The trend underscores a growing dilemma for policymakers, as while the central bank has signalled scope for further easing to support growth, firmer headline inflation could limit aggressive monetary stimulus if pressures spread beyond energy and upstream industries. China needs to juggle rising inflation with growth risks, a central bank adviser said in late March.