The NPCI's UPI Consolidated Circular released on 18 September has established a comprehensive framework for using both interest-free and interest-bearing credit lines across UPI. According to the circular, "UPI supports inclusion of pre-sanctioned credit lines as a source of funds" and credit on UPI will provide a "seamless, UPI-enabled credit lifecycle experience for users." Members and UPI application providers have been given 15 December 2026 as the deadline for implementation, with the issuer continuing to decide who receives credit, applicable terms, permitted uses and transaction approvals. The framework introduces capped charges on a small share of high-value merchant transactions while keeping person-to-person payments free, balancing affordability with long-term sustainability of digital payments.
The credit on UPI is divided into two broad categories: Interest-free credit line (CLIF) and Interest-bearing credit line (CLIB). As reported by Mint, users can use the credit without interest during the interest-free period, provided the entire outstanding amount is paid by the due date. Interest starts accruing from the date of the transaction for interest-bearing credit lines, meaning users should not assume that every credit on a UPI transaction is interest-free. The cost of borrowing will depend on the specific credit facility.
The framework permits credit on UPI to be used across several UPI features, including merchant payments, EMI transactions, UPI AutoPay, and UPI Reserve Pay, subject to the type of credit line and issuer's conditions. According to the circular, RuPay Credit Card on UPI is allowed for all UPI features, while interest-free credit line (CLIF) is allowed for merchant payments, EMI, UPI AutoPay, and UPI Reserve Pay, and interest-bearing credit line (CLIB) is allowed for all UPI features. However, person-to-person transfers (P2P) are not allowed for both types of credit lines. The new framework specifically protects small merchants and street vendors receiving up to ₹1 lakh per month via UPI QR codes, ensuring they remain exempt from transaction fees even in semi-urban areas.
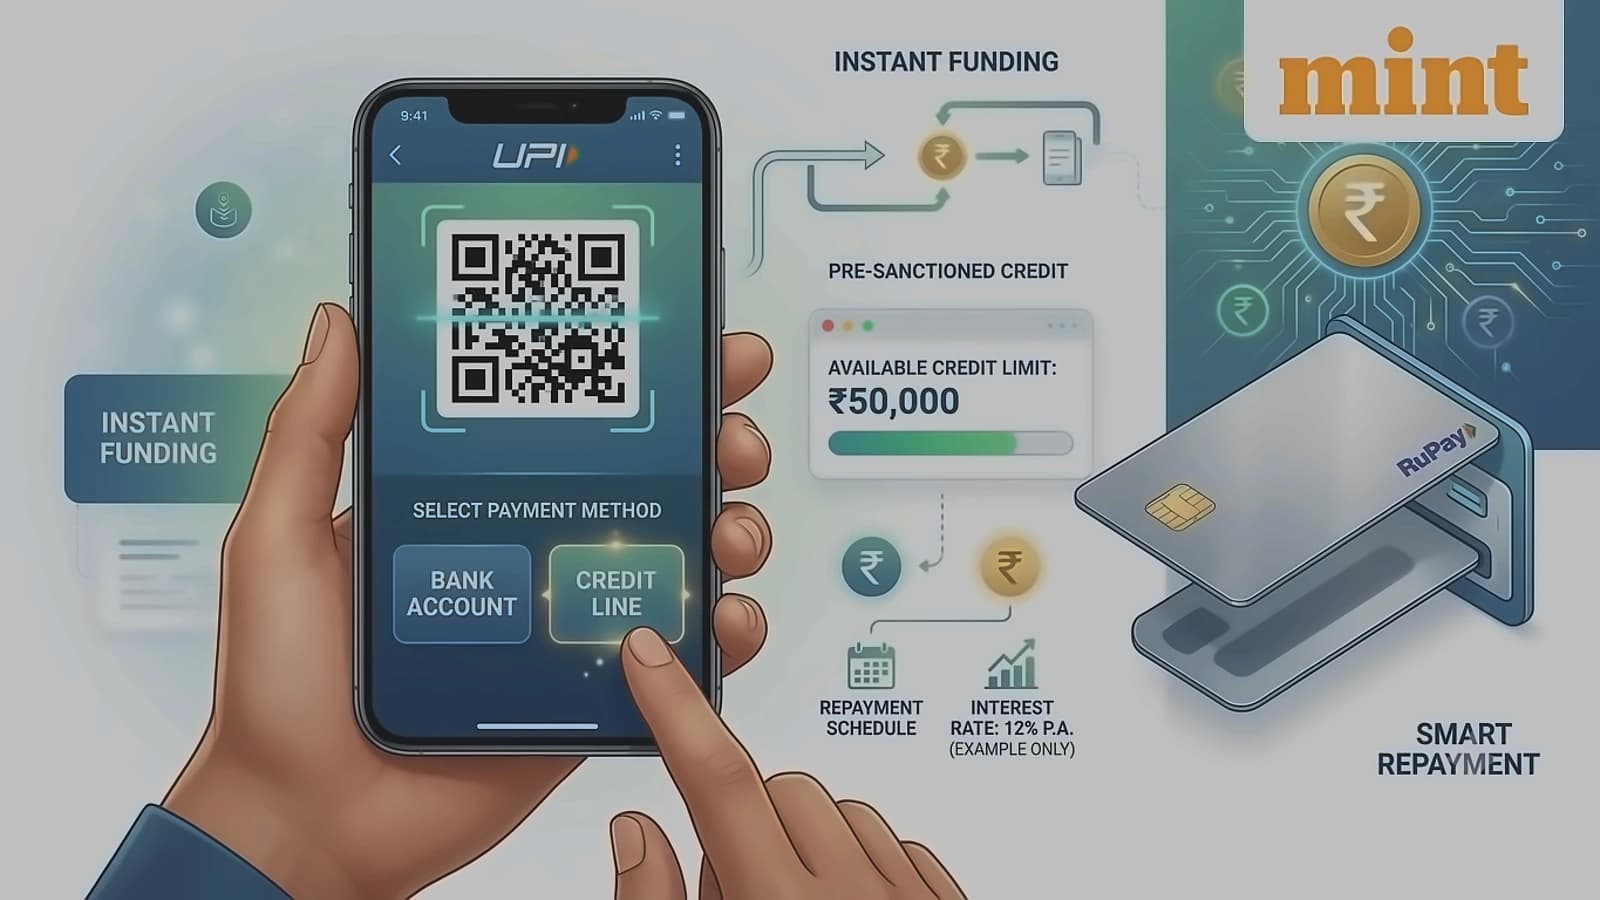
As per the circular, "Members shall standardise the account subtype and account reference number (as per the detailed guidelines laid down in the product document) to harmonise the user experience, reducing friction at the point of payment, and enabling scalable adoption of Credit on UPI." The circular emphasizes that users will have to repay the amount according to the terms of that credit facility, with the issuer maintaining control over who receives credit, applicable terms, permitted uses and transaction approvals. The framework also includes a dedicated fund to promote UPI adoption among small merchants, supported by an amount equivalent to 5 per cent of total MDR settlements, which will help more small businesses adopt and continue using UPI while protecting their interests from additional costs.