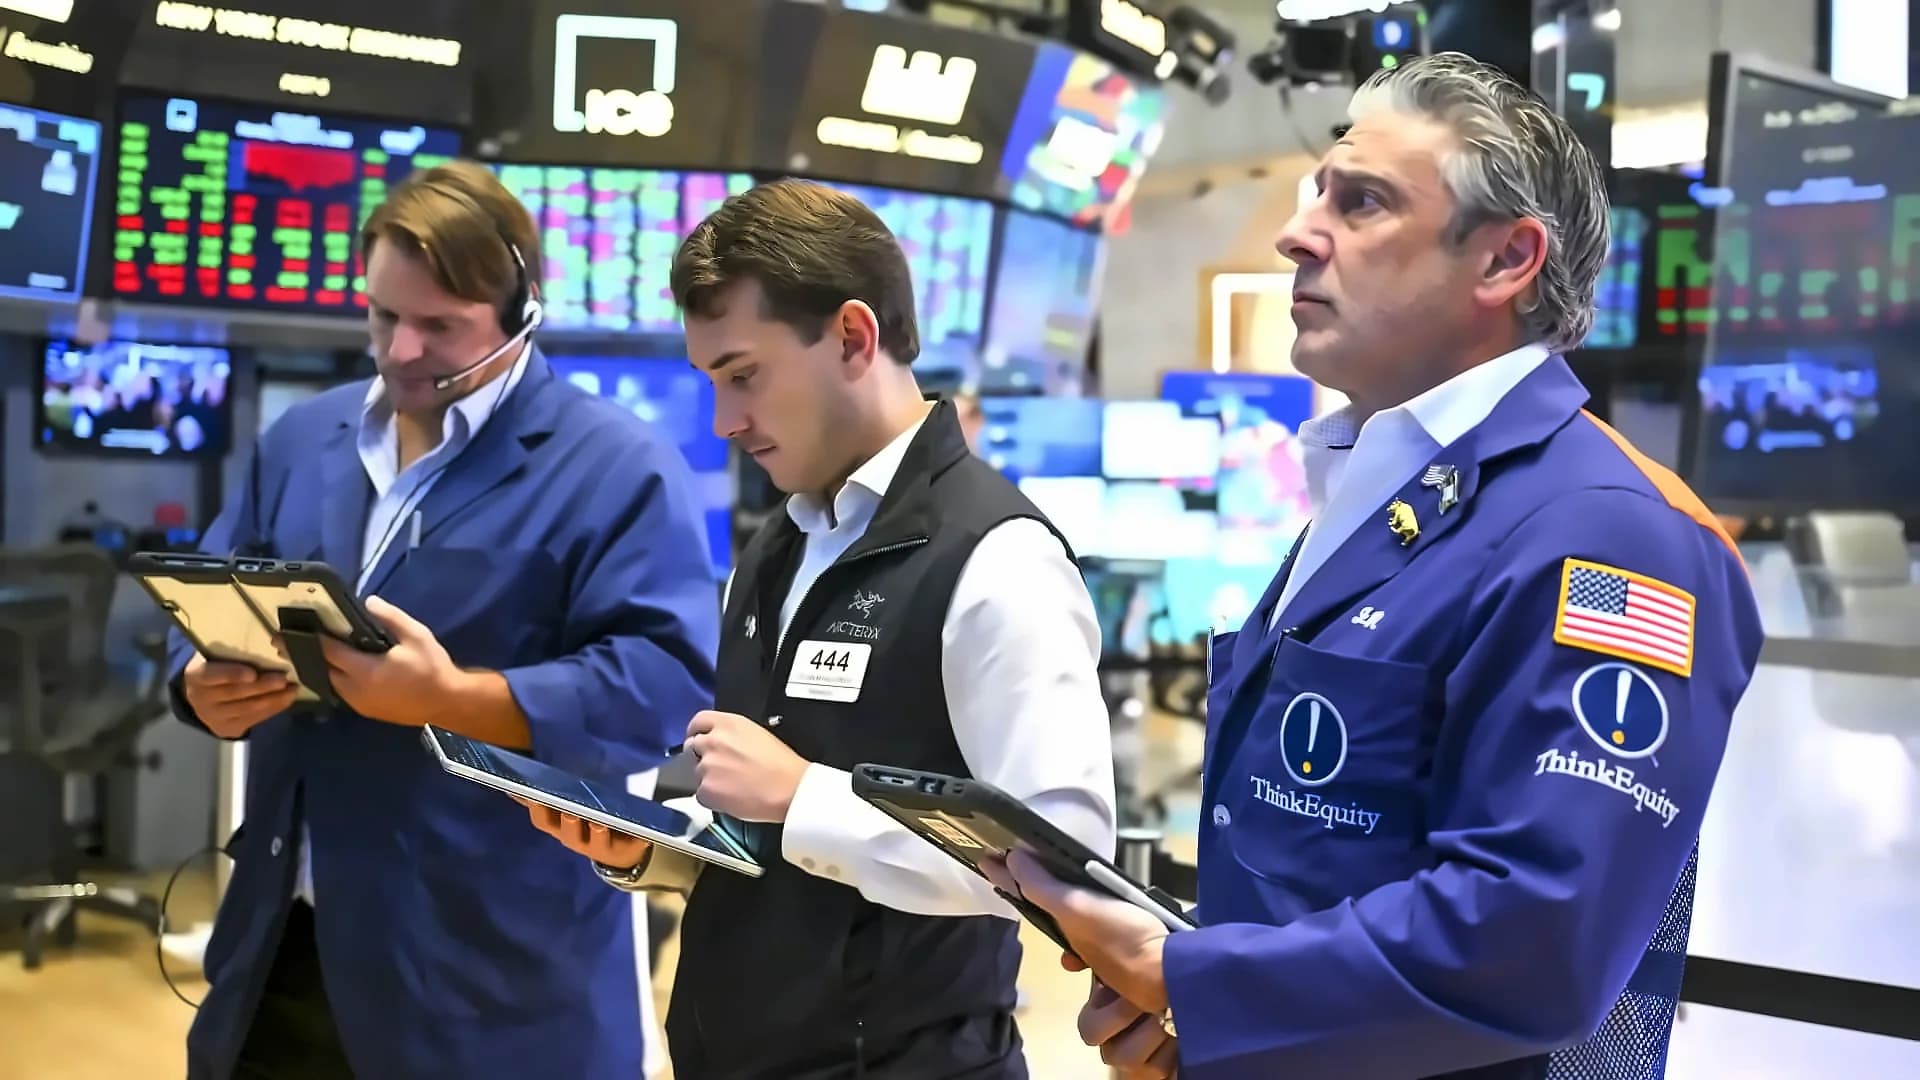
Wall Street staged a partial recovery on Wednesday, with all three major U.S. stock indexes posting modest gains as investors responded to weaker-than-expected employment data. According to reports from Reuters, the Dow Jones Industrial Average gained 0.7% just after the open, while the S&P 500 climbed 0.5% and the Nasdaq Composite rose 0.4% in morning trading. The recovery came after the ADP National Employment Report showed private-sector jobs increased by 38,000 in August, missing estimates of a 48,000-position rise and marking the slowest pace of job creation since January. As per Reuters, the gains came after the U.S. stock market kicked off September on a down note, with the Nasdaq, Dow, and S&P 500 closing 1%, 0.8%, and 0.7% lower respectively in the previous session.
Oil prices experienced significant acceleration during Tuesday's trading session, with Brent crude topping $95 per barrel as U.S. airstrikes on Iran escalated military tensions in the Middle East. According to Reuters, futures on Brent crude rose by roughly 2.5% to cross $92.50, while US benchmark WTI crude picked up a strong 2.8% to trade above $88, once again beginning the climb toward $90. The surge came after two oil tankers were struck while attempting to exit the Strait of Hormuz, with no one claiming responsibility for the attacks. The 10-year Treasury yield (^TNX) rose to 4.79%, its highest intraday level since January 2025, while the 30-year yield climbed to 5.27%, hovering near multi-decade highs. The Job Openings and Labor Turnover Survey (JOLTS) showed job openings ticked up slightly in July, providing a somewhat stable read on hiring ahead of Friday's monthly jobs report.
The Federal Reserve's latest Beige Book report revealed that the U.S. economy expanded modestly from early July through late August, with 10 of 12 districts reporting slight to moderate growth. As reported by Business Standard, data center construction and defense orders drove manufacturing gains, while AI adoption both boosted productivity and weakened demand for some entry-level roles. The report provides crucial insights into the current economic landscape as investors navigate through the ongoing market volatility. The modest growth figures suggest a stable but cautious economic environment that continues to influence market sentiment and investment decisions.
Market leadership shifted across sectors as investors rotated into previously underperforming areas. As reported by Reuters, airlines, gold and silver miners, and regional banks emerged as the top performers, while software and services sectors, which have been impacted by AI disruption concerns, lagged significantly. The Philadelphia SE Semiconductor Index showed signs of recovery, with chipmaker Broadcom expected to deliver second-quarter results after market close. The semiconductor index has lost nearly one-fourth of its value since late June despite powering much of the stock market's gains this year. Nvidia and Meta Platforms led the Magnificent Seven mega-cap tech stocks with gains above 3% and 2% respectively, while the Roundhill Magnificent Seven ETF was up 0.7%. The Magnificent Seven ETF was up 0.7% as of latest reports.
Several major companies posted significant gains during the session, with earnings driving much of the market movement. According to Reuters, Dell Technologies shares surged 14% after reporting earnings that topped analyst estimates, with the company posting adjusted earnings of $7.04 per share - more than tripling year-over-year - and revenue growing nearly 60% to $46.97 billion. GitLab shares soared 11% after reporting revenue of $286.25 million, up 20% year-over-year, while MongoDB sank 14% despite beating estimates with second-quarter revenue of $771.8 million and adjusted EPS of $1.90. Alphabet edged up 0.8% following its victory against a U.S. bid to break up Google's advertising technology business. Uber Technologies gained 2.2% after announcing plans to lay off about 10% of its staff. Nvidia, the chipmaker at the forefront of the AI wave, was up 3.4%, while Micron and Qualcomm were up 1.3% and 1.8%, respectively.