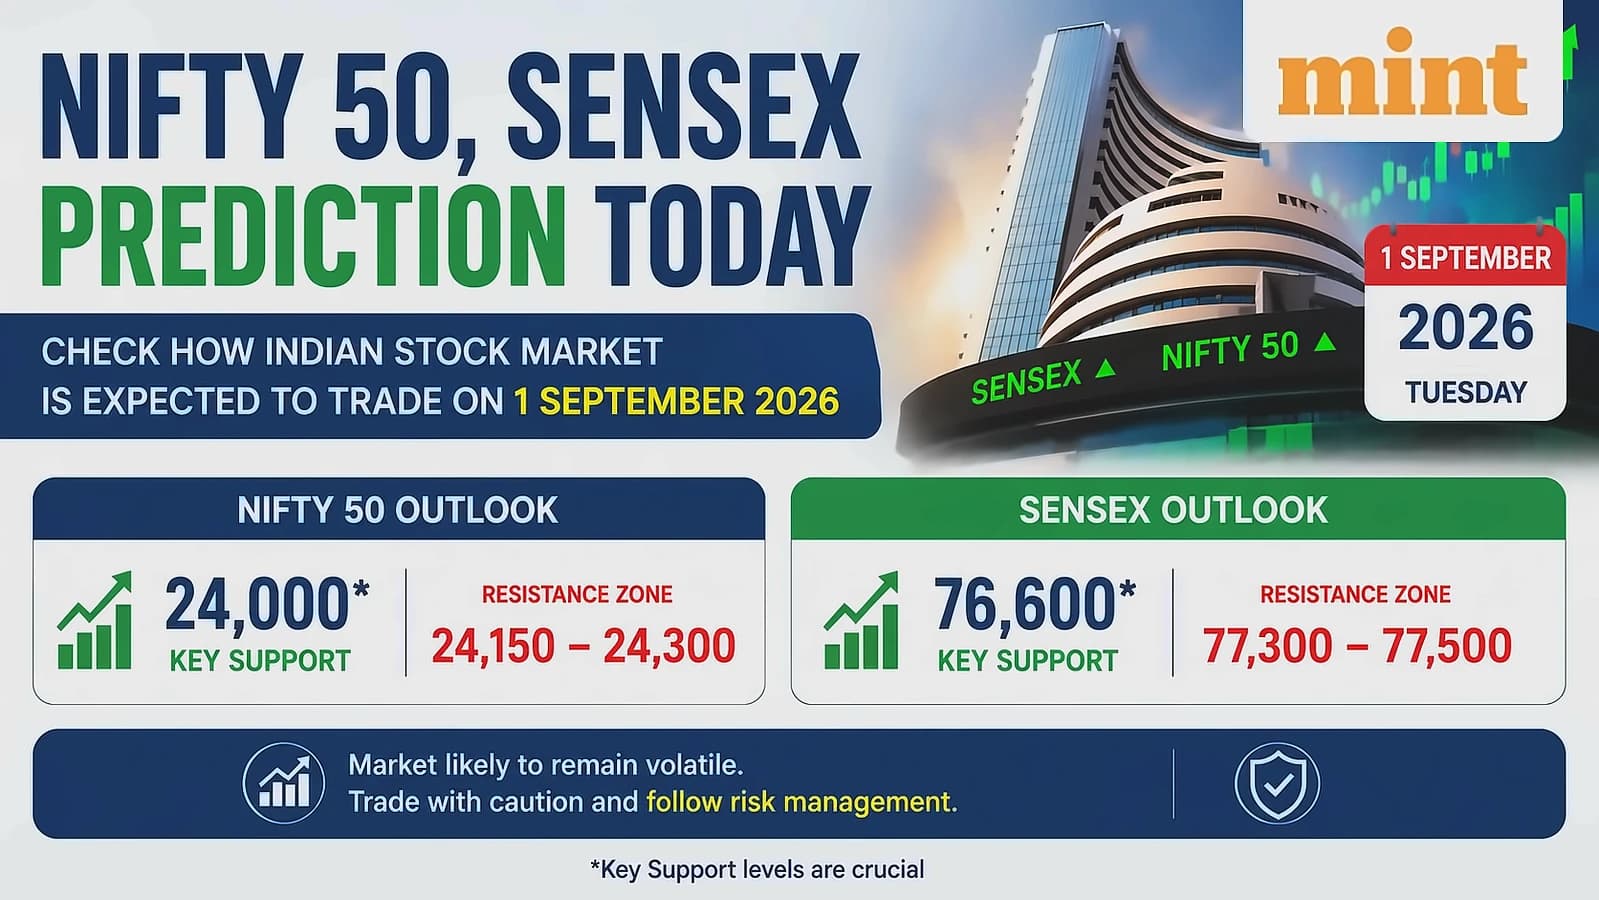
Indian equity benchmark indices witnessed a sharp recovery on Friday, September 4, with both the Sensex and Nifty rebounding strongly to snap their four-day losing streak. According to The Hindu BusinessLine, the BSE Sensex rallied 362.57 points or 0.48% to close at 76,515.43, while the NSE Nifty 50 gained 24.25 points or 0.1% to end at 23,897.70. The Nifty 50 index hit the day's peak of 24,000, showing significant resilience despite earlier headwinds. During intraday trading, the Sensex had earlier tumbled as much as 808.56 points, or 1.05%, before the strong recovery. The broader markets showed mixed performance with Nifty Midcap 100 declining 0.25% and Nifty Smallcap 100 gaining 0.22% as of the closing bell. Despite Friday's recovery, the Nifty posted a weekly loss of 1.15%, with the Sensex down around 750 points over the week.
The day's trading activity led to the formation of a green-bodied candle with a lower shadow, highlighting buying interest emerging from lower levels while the index managed to close above its opening price. The recovery was seen near a significant support zone where multiple technical factors came together. The index took support near the 38.2% Fibonacci retracement level of the recent upmove from the April 2 low, along with the July 29 gap area. It also bounced from the previous parallel lows, making Wednesday's low of 23,786 an important level to watch. A decisive break below 23,786 could bring renewed selling pressure and may drag the index towards the July swing low near the 23,600 zone. Rajesh Palviya, head of research at Axis Direct, noted that technically, the Nifty's near-term bias remains constructive above 23,800. He added that a sustained move above 24,000 could pave the way for 24,250, while a break below 23,800 may trigger a move towards 23,650. However, Rupak De, Senior Technical Analyst at LKP Securities, noted that Nifty remained extremely sideways during the day as traders stayed on the sidelines ahead of the important US non-farm payroll and unemployment data, with the short-term trend likely to remain weak as the index continues to trade below the 50-EMA on the hourly chart.
The market rally was significantly boosted by Federal Reserve Governor Christopher Waller's signals of patience on raising interest rates, which eased investor concerns about potential rate hikes. According to Bloomberg, Waller said his next decision on interest rates will be "heavily influenced" by August inflation data due next week. Waller sounded close to supporting a rate increase in prepared remarks, stating "While inflation remains meaningfully above the Federal Open Market Committee's 2 per cent goal, recent data suggest we are finally seeing some signs of disinflation." Following his comments, expectations for a rate increase at the Fed's September meeting came down, with markets pricing in a 50 per cent chance for a hike, versus about 63 per cent in the prior session, as per CME FedWatch. The relief rally was further supported by softer-than-expected US Non-Farm Employment Change data that bolstered risk appetite globally. The day's sentiment was lifted largely by dovish signals from US Fed Governor Christopher Waller, who indicated support for keeping interest rates unchanged at the next policy meeting.
At the sectoral level, metals, financial services and cement emerged as the top gainers, while realty, healthcare, pharma and IT faced selling pressure. Market breadth turned nearly even with 245 stocks advancing against 249 declining within the Nifty 500 universe, as per The Hindu BusinessLine. Among Nifty 50 stocks, SBI Life, Tata Steel and HDFC Life led gains, while HCL Technologies, Bharti Airtel and Maruti were the top laggards. The Hindu BusinessLine reports that gains remained capped by profit booking at higher levels and persistent geopolitical tensions in the West Asia, limiting the overall market momentum despite the positive Fed signals. The broader markets delivered a split verdict with Nifty Smallcap 100 gaining 0.22% and Nifty Midcap 100 declining 0.25%.
Indian stocks tracked positive sentiment in global markets, with the Nikkei 225 index gaining 1.30%, South Korea's Kospi adding 1.61%, and Hang Seng trading 1.76% higher. Overnight, the US stock market had closed with solid gains, with all three indices - Dow Jones, S&P 500 and Nasdaq Composite - gaining over 1%. The rally was primarily driven by index heavyweights in action, with shares of Reliance Industries single-handedly contributing a third of Sensex's gains following a 2.4% rise. Reliance Industries was supported by brokerages like Jefferies and Nomura who have reiterated bullish views amid expectations of strong earnings growth in FY27, supported by RIL's oil-to-chemicals business and firm petrochemical spreads. HDFC Bank also accounted for a major chunk of the rise and was among the top Sensex gainers.
On the macro front, India's Q1FY27 real GDP growth came in at 7.8%, beating market expectations, driven by strong exports and investment growth. The Indian rupee strengthened, closing near 94.50 against the dollar, a nearly 1% appreciation during the week, supported by FCNR deposit inflows that have crossed $127 billion under the RBI's special concessional window. However, Brent crude rose 0.3% to around $95.4 per barrel, remaining an overhang on sentiment given India's import dependence. The Hindu BusinessLine reports that gold saw volatile moves during the week, recovering from around ₹1,50,000 to ₹1,55,000 on softer employment data, with analysts pegging its near-term range at ₹1,52,500–₹1,57,500. Looking ahead, markets will watch the US unemployment data closely, while next week's US CPI print will be critical in shaping Fed rate expectations. On the domestic front, 11 mainboard IPOs are scheduled to open next week, targeting over ₹7,000 crore. As per Motilal Oswal Financial Services, crude prices and developments in the West Asian conflict remain key risks, while investors will track global rate expectations and domestic liquidity.