The Blockchain Association has submitted a letter of comment to the SEC on August 17, joining the growing list of market participants supporting the proposal to eliminate Rule 611. According to the latest filing, the association argues that the current crypto market has become more automated, interconnected, and technologically advanced, making the existing rules outdated for modern trading environments. The Blockchain Association specifically supports the SEC's proposal that removing both Rule 611 and Rule 610(e) could improve competition, liquidity, and price discovery for the upcoming crypto market. The association emphasizes that unlike traditional exchanges, blockchain markets can offer 24/7 trading, near-instant settlement, transparent records, and self-custody while using models such as AMMs, on-chain order books, and intent-based systems.
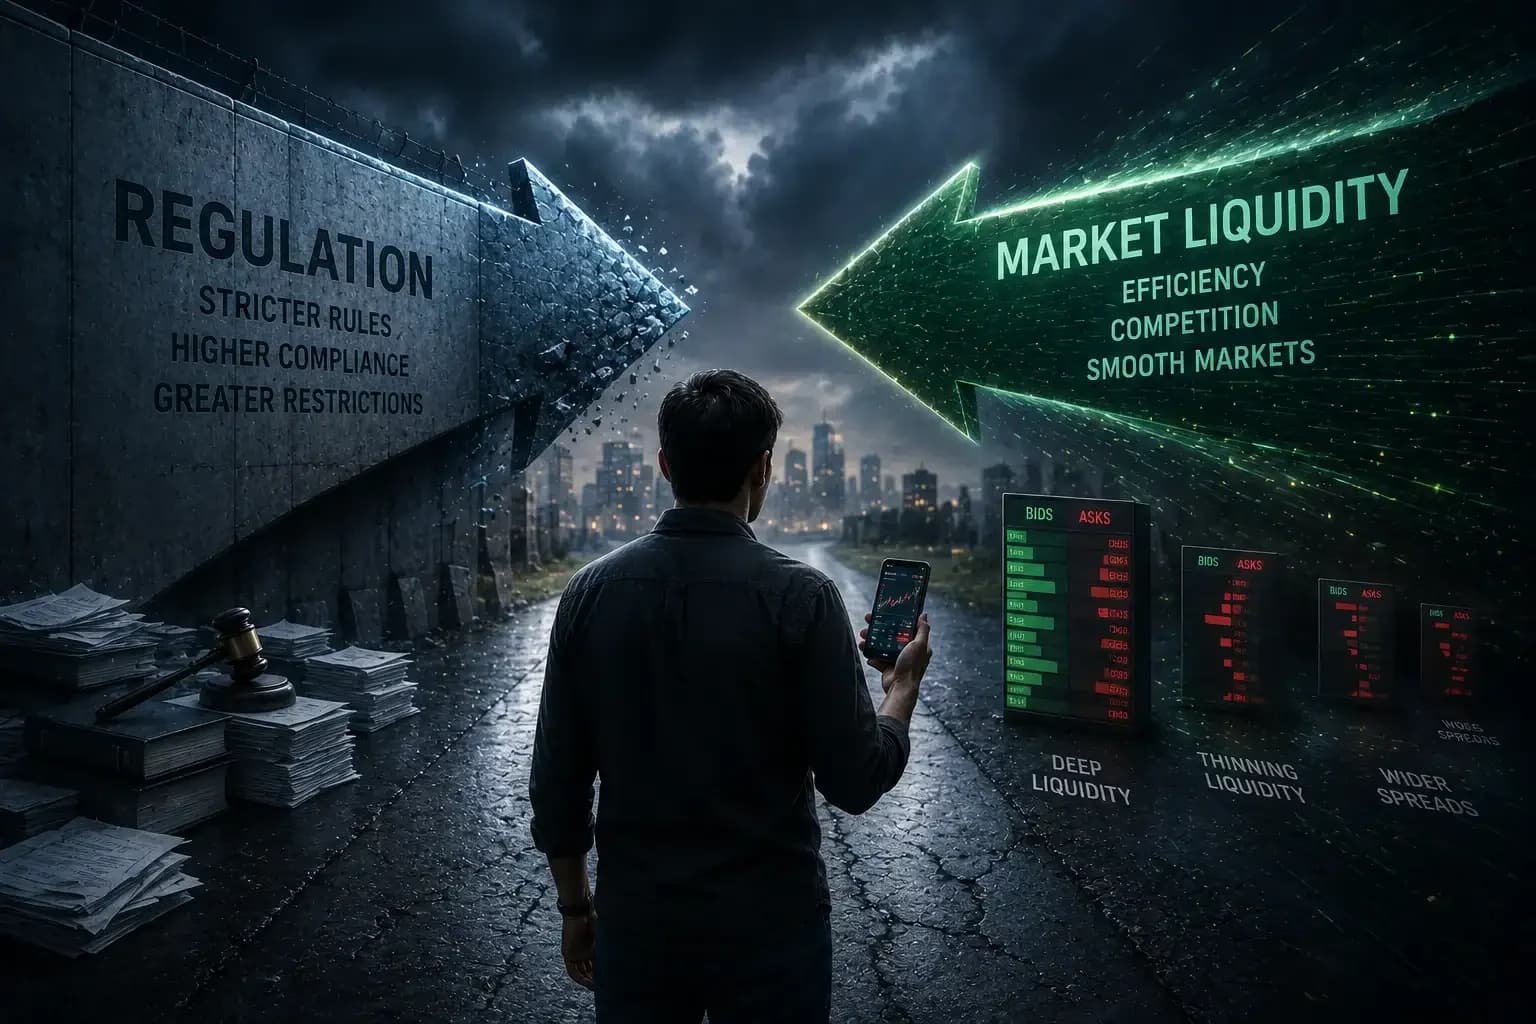
The U.S. Securities and Exchange Commission's proposal to eliminate Rule 611 has drawn mixed responses from market participants, with Hyperliquid Policy Center and Douro Labs submitting a joint comment letter on August 17 supporting the repeal. According to recent reports, the 22-page letter argues that the current quotation system does not map cleanly onto automated market makers, onchain order books, and markets operating continuously outside traditional exchange hours. The proposal represents a significant shift from the existing framework that prevents executions at prices worse than protected quotations displayed elsewhere, with the SEC comment period closing August 17 and no final decision announced yet. The Blockchain Association now stands with these groups in supporting the regulatory modernization.
Citadel Securities has maintained its strong opposition to the SEC proposal, urging the commission to reconsider its decision to eliminate the order protection rule. As reported by Reuters, Stephen John Berger, managing director and global head of government and regulatory policy at Citadel Securities, warned that the proposal would amount to a significant overhaul of U.S. equity market structure and described the SEC's economic analysis as "fatally flawed." The market-making firm argues that eliminating the rule could make it easier for brokers to bypass better prices displayed on public exchanges, potentially reducing incentives for market participants to display competitive quotes. The firm has recommended alternatives including minimum trading-volume thresholds for exchanges to qualify for protected status.
The Hyperliquid Policy Center and Douro Labs joint submission highlights significant technical limitations of the current Rule 611 framework. According to their filing, the quotation system assumes executable interest appears as firm quotations collected by securities information processors, but automated market makers calculate execution prices from liquidity pools when orders are placed. Some onchain central limit order books display bids and offers, but these prices are not currently incorporated into the consolidated feeds used to calculate the National Best Bid and Offer (NBBO). The groups propose evaluating effective execution price after accounting for protocol charges, network fees, and market movement caused by orders, with settlement speed and reduced counterparty settlement risk forming part of the assessment. The Blockchain Association specifically notes that these mechanisms differ from traditional exchanges, making the current rules inappropriate for on-chain markets.
The proposed repeal would not affect the regulatory framework for tokenized U.S. equities, which would remain subject to securities rules and broker best execution duties unchanged. As reported by recent filings, Hyperliquid Policy Center and Douro Labs asked the SEC to confirm that tokenized versions of NMS stocks remain inside Regulation NMS and the wider best execution framework. This approach ensures that investor protections would not depend on whether ownership records use a blockchain, addressing the expansion of tokenized stock products across crypto networks. The Blockchain Association specifically wants the SEC to clarify how tokenized securities can trade and settle using stablecoins, emphasizing that regulation should not prevent blockchain-based markets from integrating tokenized assets, stablecoins, and on-chain settlement. The association argues that the Proposing Release is consistent with the Administration's intention to promote United States leadership in digital assets and financial technology, focusing on factors beyond price including speed, costs, settlement, certainty, interoperability, and self-custody.
The SEC will now review all submitted comments before deciding whether to adopt, revise, or withdraw the Rule 611 repeal proposal. According to recent reports, SEC Chairman Paul Atkins said the proposal was intended to simplify market structure and reduce costs, with the agency taking a "careful, deliberative approach" while reviewing public feedback. The repeal would require a final Commission vote and adopting release establishing the final text and effective date. Not all market participants support removing the rule, with some warning that repeal could weaken objective price protection standards and place greater reliance on individual brokers' routing systems. As SEC Commissioner Mark Uyeda acknowledged in June, removing Rule 611 could raise issues involving best execution, transparency, trading mechanics, and investor confidence. The Blockchain Association's support represents a significant development as the crypto market continues to evolve, with the association noting that Rule 611 created fragmented trading and increased costs, whereas Rule 610(e) was used to skew price discovery.