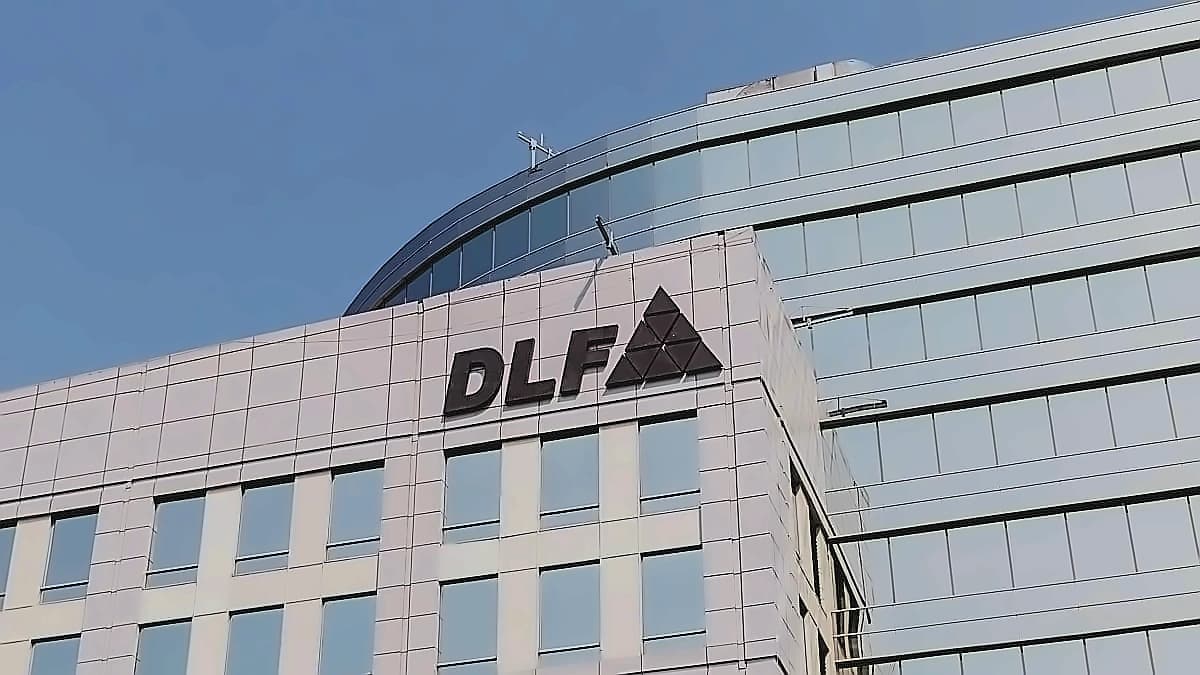
DLF Limited reported strong financial performance for Q2 FY27, with consolidated net profit rising 10% year-on-year to ₹1,301 crore compared to ₹1,180 crore in the same quarter last year. However, revenue from operations declined 23% to ₹2,298 crore during the July-September quarter. The company achieved gross margins of 47% and EBITDA of ₹1,060 crore, while operating cash flow stood at ₹1,858 crore. Despite a dividend outflow of ₹1,980 crore, DLF maintained a net cash position of ₹15,084 crore. The company's new sales bookings jumped 478.7% quarter-on-quarter to ₹3,800 crore, demonstrating robust demand for its residential offerings. As per Whalesbook, the growth was primarily driven by a non-operating fair value gain of ₹738.71 crore on compulsorily convertible debentures, while operating revenue shrank during the quarter.
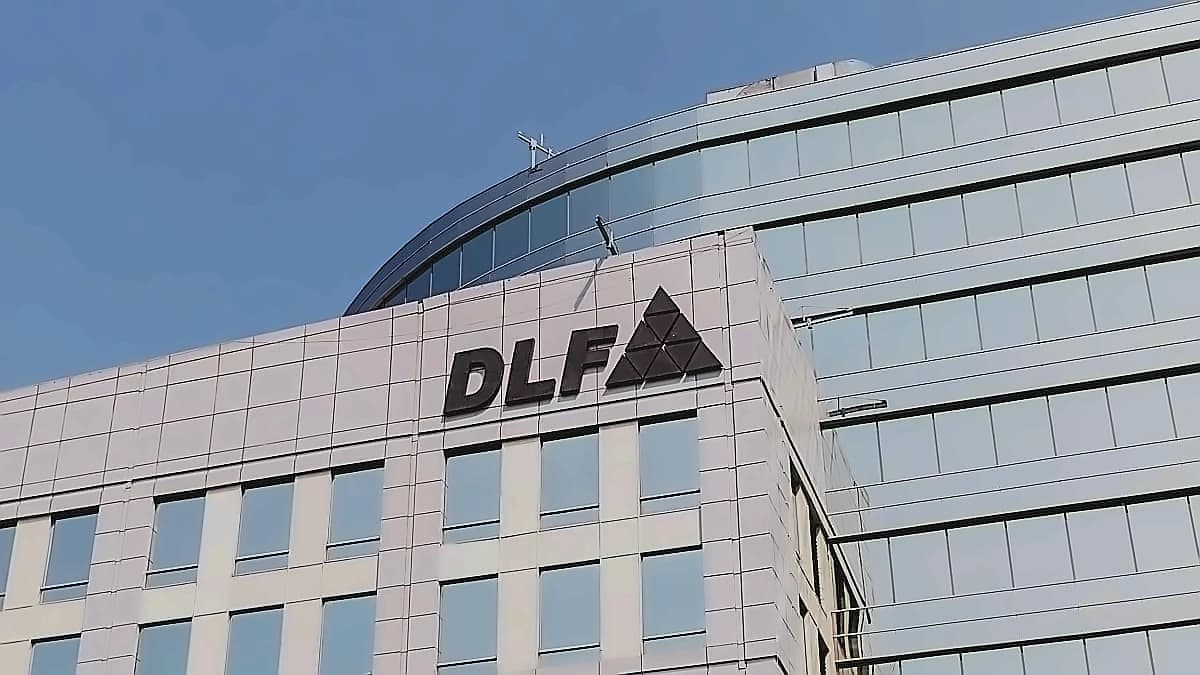
For the first half of FY27, DLF's performance showed mixed results with net profit jumping 8% to ₹2,095 crore compared to ₹1,943 crore in H1 FY26. However, revenue from operations declined 46% to ₹2,341 crore in H1 FY27 as against ₹4,360 crore in H1 FY26. The company's EBITDA dropped 92% to ₹23 crore compared to ₹284 crore in the corresponding quarter of the previous fiscal year, with EBITDA margin contracting to 1.79% from 17.29% in Q2 FY26. Despite revenue challenges, DLF maintained its strong cash position and operational strength, with the company stating that operating cash flow at ₹1,858 crore further reinforces the underlying business strength.
On Friday, DLF shares closed at ₹675 apiece on the National Stock Exchange, rising 0.67% following the results announcement. According to NSE data, as of October 16, 2026, DLF has a total market capitalisation of ₹1.67 lakh crore. From the beginning of the year, DLF shares have slipped 2.3%, while over a month's time, the stock has gained 8%, and for a six-month period, it has jumped over 14%. Shares of the firm had hit a 52-week high of ₹786.50 on October 29, 2025, and a 52-week low of ₹489.40 on April 2, 2026. The positive market response reflects investor confidence in the company's strong cash position and growth prospects despite revenue challenges.
As reported by Business Standard, Aakash Ohri, joint managing director and chief business officer at DLF Limited, confirmed that the company's Dahlias project had seen a 10 per cent price increase this quarter, with further increases expected once the experience centre is completed. Ohri explained that the Dahlias pricing algorithm ensures an increase with every sale, not linked to velocity or number of sales, operating as a progressive system. The company's luxury retirement housing project, The Aureva in Gurugram, witnessed a complete sell-out during Q2 FY27, underscoring demand for differentiated residential offerings, while The Dahlias continues to attract strong customer interest. The company's rental portfolio spans approximately 50 million square feet, with the company reporting strong occupancy rates across its operational developments.
According to reports from Business Standard, DLF Limited expects revenue growth to accelerate from FY28 onwards as its launched projects worth around ₹75,000 crore near completion and are handed over to buyers. Badal Bagri, group chief financial officer at DLF, stated that the company's inflection point of revenue, which is almost ₹75,000 crore of launched end projects so far, will be seen in 2027 to 2028, with the next four to five years when this entire revenue will be recognised. The company follows the completed contract method of accounting, under which revenue is recognised only once a project is completed and an occupation certificate (OC) is received. DLF stated that with a significant land bank, a robust launch pipeline across development and rental businesses, a strengthened balance sheet and consistent cash flow generation, DLF is well positioned to capitalize on the structural upcycle in the sector.