The U.S. Securities and Exchange Commission has unveiled Regulation Crypto Assets, marking the first comprehensive offering framework specifically tailored to crypto asset projects where the crypto asset is subject to a covered investment contract. According to the latest SEC proposal published in the Federal Register on August 21, 2026, the framework includes two exemptions from registration under Section 5 of the Securities Act of 1933, principles-based disclosure requirements, a non-exclusive safe harbor from the definition of 'investment contract,' and preemption of certain state registration requirements. The Commission states this proposal should reduce compliance burdens, support network development, and promote capital formation, representing a significant shift away from ad hoc regulation by enforcement actions.
The framework introduces two distinct pathways for crypto asset offerings. The Startup Exemption provides early-stage projects with a four-year regulatory runway to raise up to $5 million through capital raises, airdrops, staking rewards, and other network-development activities. Securities issued under this exemption would not be restricted securities and would not be subject to Rule 144 resale limitations, with general solicitation permitted. The Fundraising Exemption offers a two-tier structure for larger offerings, permitting up to $75 million in any 12-month period with scaled requirements depending on whether issuers elect Tier 1 ($20 million maximum, $6 million affiliate selling) or Tier 2 ($75 million maximum, $22.5 million affiliate selling). Unlike the Startup Exemption, the Fundraising Exemption is available only to U.S.-organized entities where more than 50% of assets are located in the United States, with Tier 2 issuers required to provide audited financial statements.
The framework includes a non-exclusive Investment Contract Safe Harbor that provides a defined off-ramp from SEC oversight. If an issuer completes all essential managerial efforts under the investment contract and files a transition report certifying conditions are met, the investment contract would be deemed to have ceased to exist. More significantly, Proposed Rule 500 defines 'qualified purchaser' under Section 18(b)(3) to preempt state registration and qualification requirements for covered investment contracts. This preemption extends to both initial offers and secondary-market transactions by any person other than an issuer, underwriter, or dealer, provided the issuer initially sold the covered investment contracts pursuant to a Regulation Crypto Assets exemption. The Commission notes this represents a meaningful departure from Regulation D and Regulation Crowdfunding, neither of which preempt state law for secondary trading.
The tokenization initiative represents a significant shift in capital markets infrastructure, with Citi analysts estimating tokenized assets could grow into a $5.5 trillion market by 2030. According to CoinDesk, global asset managers, banks and market infrastructure firms are pushing deeper into blockchain technology, betting on faster settlement, around-the-clock markets and lower costs. The basic concept involves taking familiar assets like stocks, bonds or investment funds and representing ownership on a blockchain for easier movement between investors and financial platforms. The new regulatory framework is expected to facilitate the development of liquid secondary markets for covered investment contracts without requiring participants to navigate a patchwork of state registration requirements.
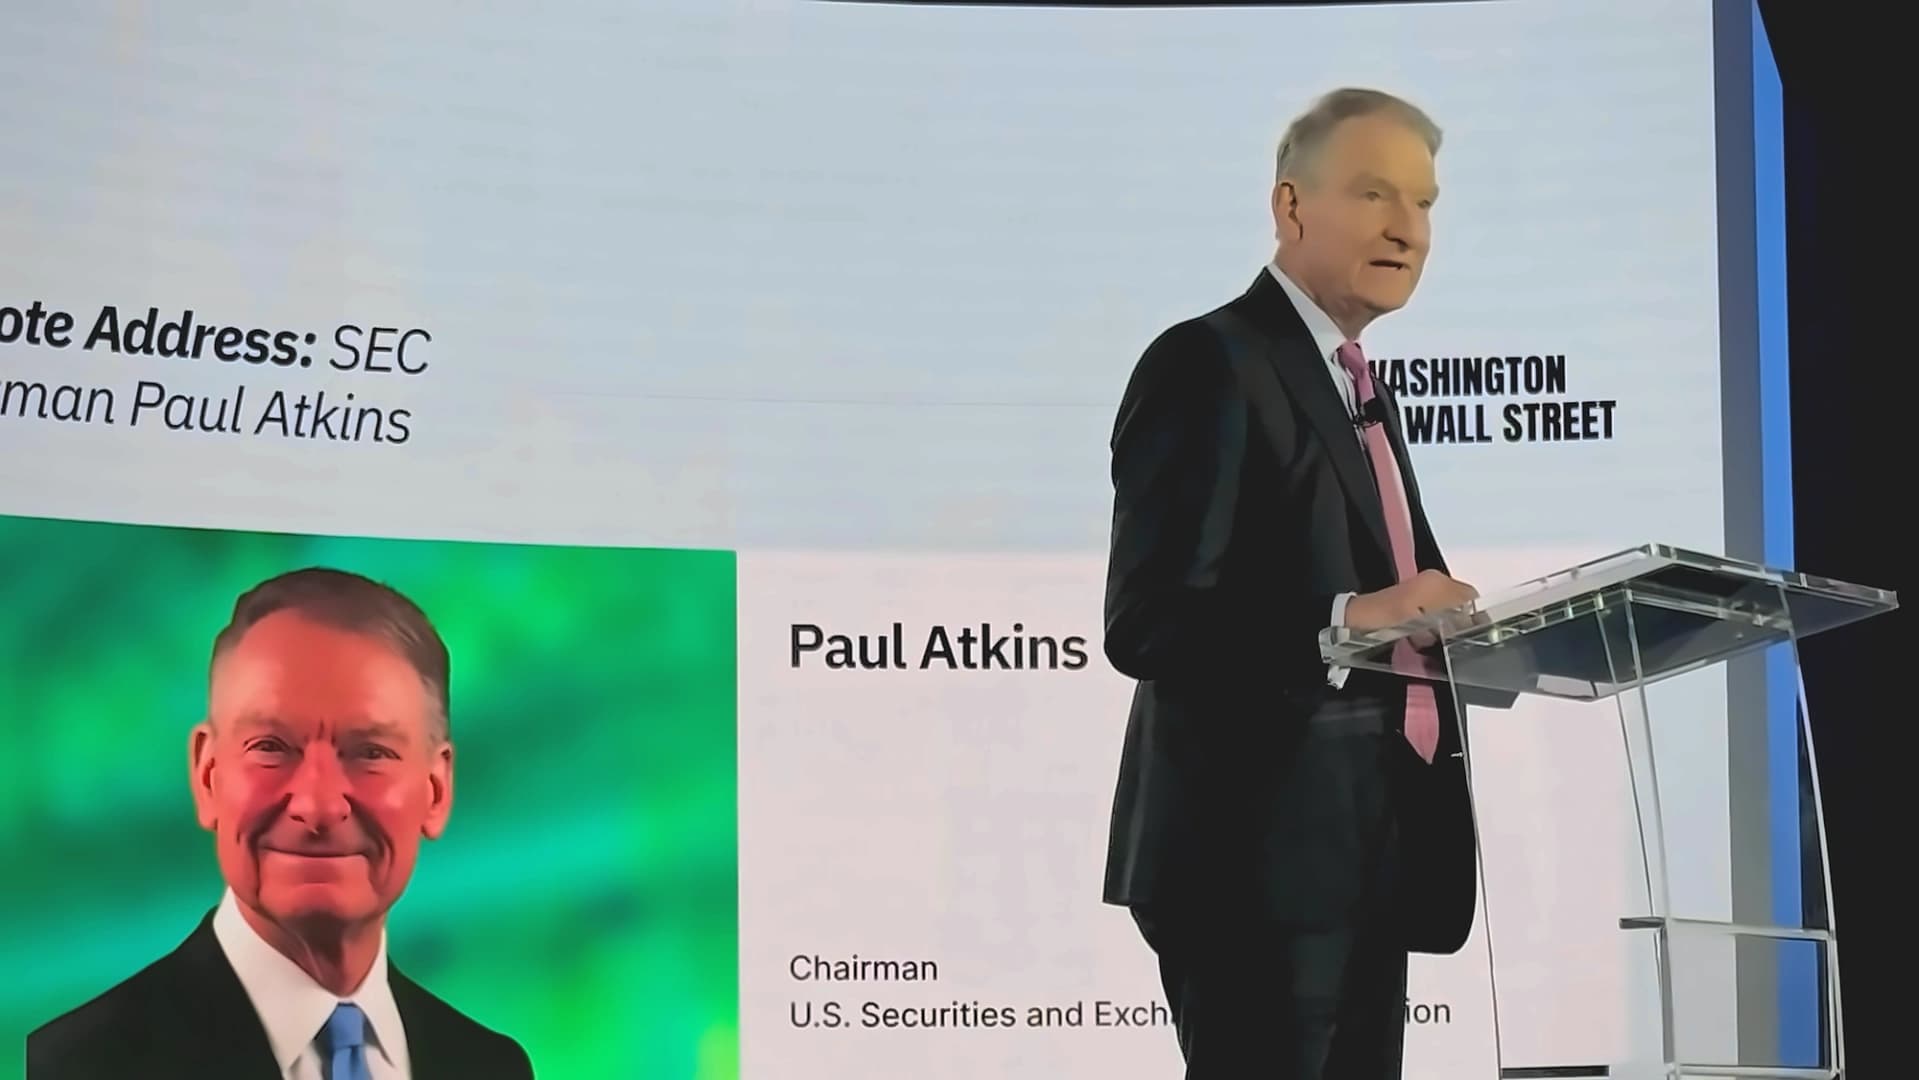
Comments on the Regulation Crypto Assets proposal are due on or before October 20, 2026, with submissions accepted through the SEC's internet comment form, email to rule-comments@sec.gov, or paper mail to the Commission's Secretary. The proposal is one component of the SEC's broader 'Project Crypto' initiative launched in July 2025 by Chairman Atkins to modernize the federal securities regulatory framework for crypto assets. The framework builds on the Commission's March 2026 interpretive release that established a classification framework for crypto assets and clarified circumstances under which a non-security crypto asset becomes, and subsequently ceases to be, subject to an investment contract. The Commission has indicated that topics including registered offerings of crypto asset securities, amendments to broker-dealer or investment adviser rules, or full scope of secondary-market trading issues may be addressed in future rulemakings.