Cryptocurrency gifts are legally permitted in India, as they are recognized as Virtual Digital Assets (VDAs) under the tax framework. According to Pranav Pagaria, Head of Finance & Strategy at CoinDCX, it is advisable to maintain a gift deed documenting the transfer to ensure proper record-keeping. Such documentation becomes crucial for tax reporting when the recipient eventually sells the gifted crypto, as it establishes the original transaction details and donor's purchase records. The latest August 2026 CBDT Guidance Note emphasizes the importance of maintaining transaction-wise logs of every buy, sell, swap and transfer with dates, amounts, INR values and the exchange used, and retaining supporting statements for accurate reporting.
Under Section 56(2)(x) of the Income Tax Act, 1961 and Section 92(3) of the Income Tax Act, 2025, gifts from specified relatives are fully exempt with no monetary ceiling. As reported by Mint, the specified relatives include spouse, siblings of the taxpayer or spouse, siblings of either parent, lineal ascendants and descendants, and spouse of any listed above. For example, if your mother gifts Bitcoin worth ₹12 lakh, no tax arises on receipt. Additionally, gifts received on marriage occasions, under wills, by inheritance, or in contemplation of death remain fully exempt regardless of amount or relationship with the recipient. The August 2026 CBDT Guidance Note confirms that VDA received as gifts can be taxable in the recipient's hands under normal gift provisions, subject to usual exemptions.

For gifts from non-relatives, taxation applies when the aggregate value exceeds ₹50,000 in a financial year. According to Pagaria's analysis, the entire amount becomes taxable, not merely the portion above ₹50,000, and is taxed as 'Income from Other Sources' at the recipient's applicable slab rate. For instance, if a colleague gifts Ethereum worth ₹75,000, the entire ₹75,000 is added to the recipient's taxable income. The August 2026 CBDT Guidance Note introduces stricter reporting requirements, with no expense being deductible except the cost of acquisition, and loss from one VDA cannot be set off against gain from another VDA or against any other income. For gifts between Indian residents and NRIs, transfers must comply with FEMA rules.
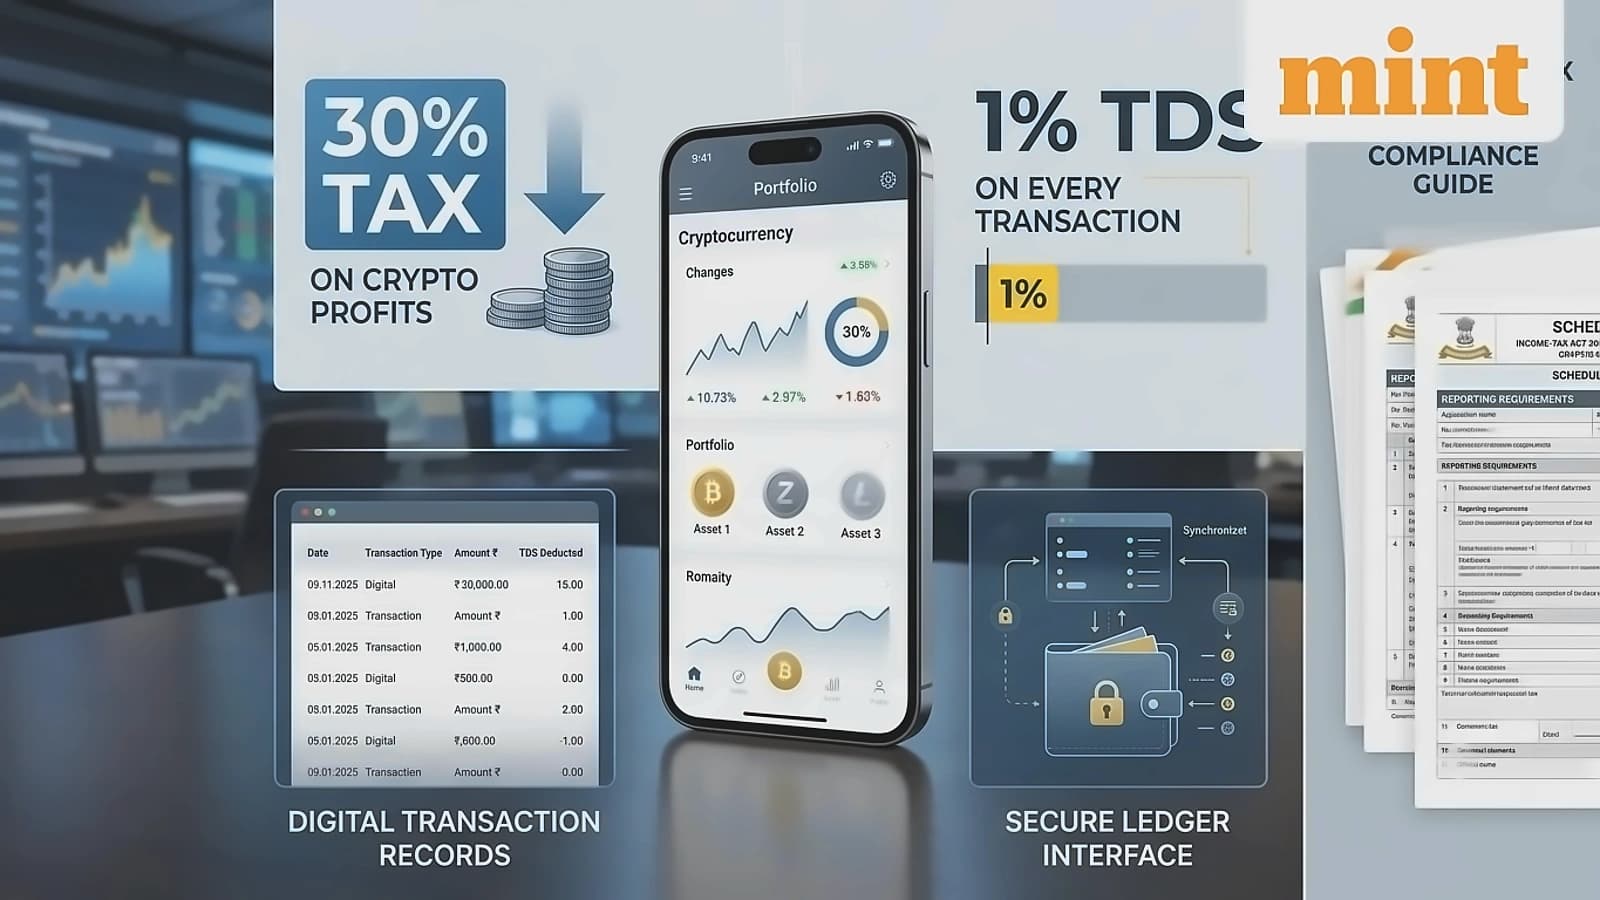
When tax-exempt gifted crypto is later sold, the donor's original purchase price becomes the recipient's cost of acquisition, rather than the crypto's fair market value on the gift date. As explained by Pagaria, if your father bought 0.1 BTC in 2019 for ₹15 lakh and gifted it to you in 2024 when its value was ₹45 lakh, and you sell it in 2026 for ₹70 lakh, the taxable gain is ₹55 lakh (₹70 lakh - ₹15 lakh). At the 30% VDA tax rate, the tax liability comes to ₹16.5 lakh, excluding surcharge and cess, with the 1% TDS deducted by the buyer claimable as credit against tax liability. The August 2026 CBDT Guidance Note clarifies that only the cost of acquisition is allowed, with no other expenditure or allowance deductible against VDA gains.
According to Pagaria's guidance, India's ITR framework requires transaction-wise reporting of VDAs. When the recipient sells gifted crypto, the transaction must be disclosed under Schedule VDA with relevant acquisition and transfer details. Both parties should maintain exchange statements, transaction records, wallet addresses, transaction hashes, and valuation of crypto on the gifting date. The August 2026 CBDT Guidance Note emphasizes that reporting is a disclosure obligation, not just a 'tax due' trigger, and recommends reconciling every exchange, wallet and P2P transaction against the Annual Information Statement (AIS) before filing. For gifts held on foreign platforms, the taxpayer must disclose them under Schedule FA (Foreign Assets) in the ITR. The recipient should also retain the donor's original purchase records, including exchange statements, invoices, wallet history, and gift transaction details.