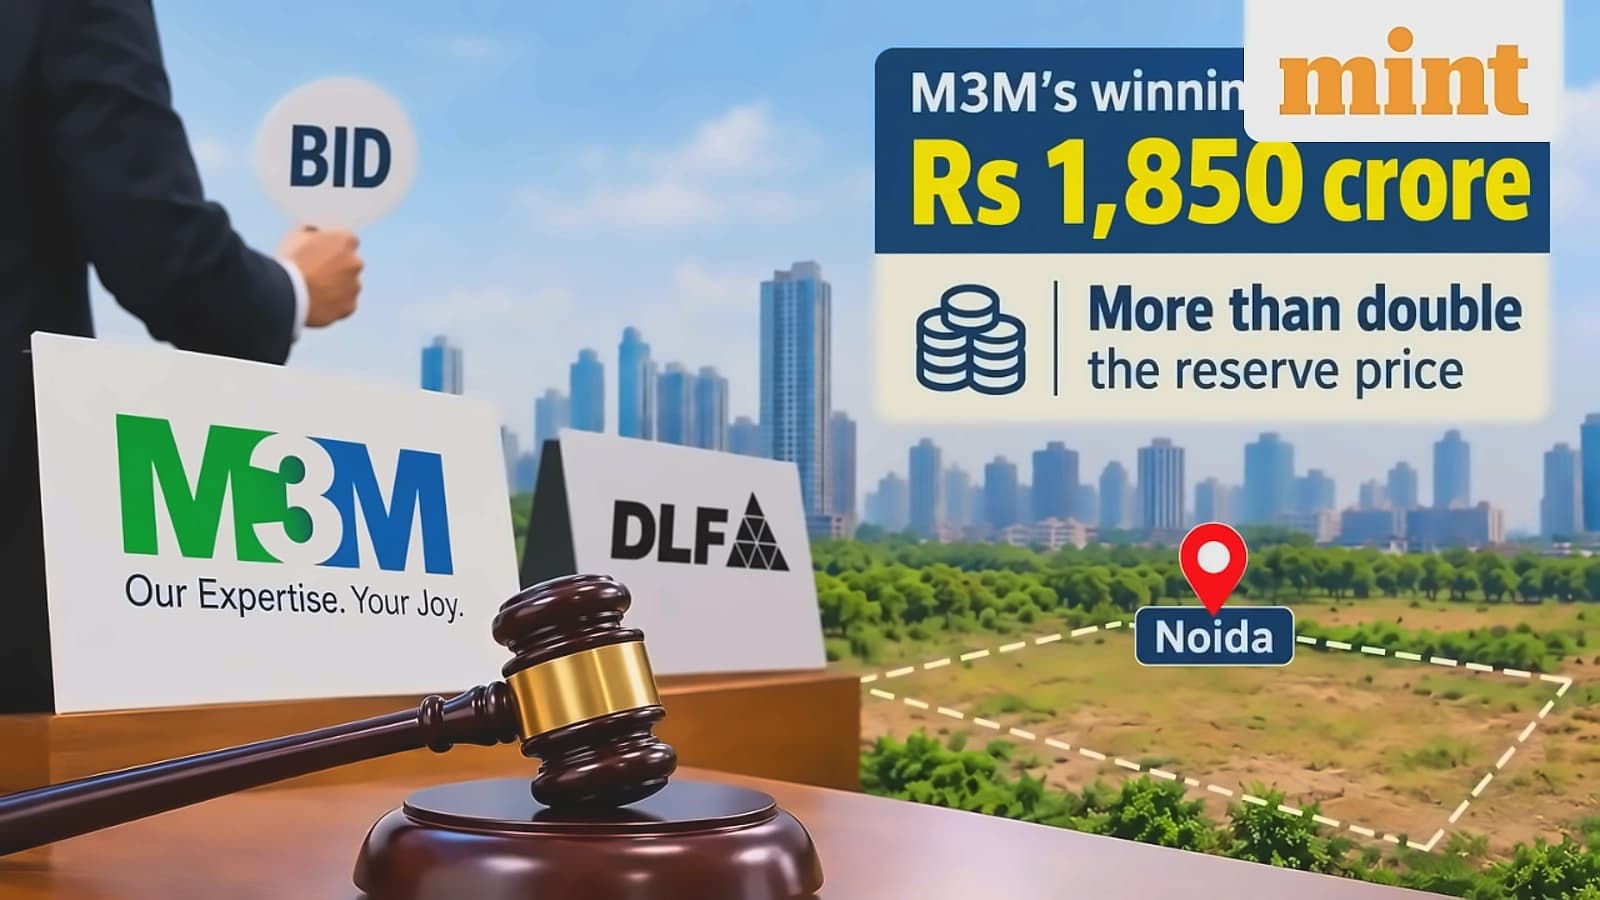
The reserve price was set at Rs 835 crore. When the bidding concluded,
Including stamp duty and government charges, M3M's total outlay is expected to approach Rs 2,000 crore, translating to roughly Rs 147 crore per acre.
Godrej Properties, though shortlisted, did not bid on the day. This outcome wasn't just about who wrote the bigger check; it was a revealing moment that exposed fundamentally different strategic philosophies, risk appetites, and capital allocation priorities between two of Delhi-NCR's most prominent developers.
M3M's High-Stakes Expansion Gamble
M3M's aggressive bidding is rooted in an ambitious expansion strategy. The company has committed Rs 2,500 crore for land acquisition and set an annual target of Rs 5,000 crore in land deals for 2026. Beyond land, M3M plans to invest Rs 14,500 crore to accelerate construction of its 45 million sq. ft. under-development portfolio. This is a developer in aggressive growth mode, actively seeking to establish dominance in prime NCR corridors.
The Noida acquisition fits neatly into this broader playbook. M3M already had a growing footprint in the region, including prior acquisitions in Sectors 94 and 97, and a cumulative investment of Rs 9,000 crore in Noida with projected sales potential of Rs 12,500 crore. Securing the Sector 108 parcel strengthens M3M's presence along the Noida Expressway—a corridor benefiting from infrastructure upgrades like the upcoming Jewar International Airport—and allows the company to create geographic synergies with its existing projects.
However, this strategy comes with significant financial risk. M3M's total debt stands at approximately Rs 350 crore, down from Rs 940 crore, indicating a deleveraging trend. The Rs 2,000 crore outlay for Sector 108 represents a substantial capital commitment that will likely require new debt or equity infusion. If funded through debt at current market rates (7-8%), M3M's annual interest obligations could increase by Rs 86-108 crore, potentially pressuring its interest coverage ratio—which historically stood at 1.7x—down toward 0.8-1.0x. This level of leverage could strain the company's BBB+ credit rating and limit financial flexibility for other projects.
DLF's Disciplined Retreat
DLF's decision to participate but not match M3M's premium reflects a fundamentally different approach to capital allocation. Management has consistently emphasized a "margin-accretive" philosophy, pursuing only those deals that meet strict return thresholds. Unlike M3M, which is aggressively building its land bank, DLF maintains it has "adequate freehold license land to take forward our growth for the next several years". This existing land bank reduces the urgency to overpay for new parcels. Transcripts +2
DLF's capital allocation framework prioritizes three areas: increasing shareholder returns through dividends, investing in its existing healthy pipeline (particularly its rental business), and being open only to opportunistic, margin-accretive deals. The company's strong balance sheet—with a net cash position of Rs 15,200 crore and net debt-to-GAV of just 18%—provides the luxury of discipline. DLF can afford to walk away from overpriced assets because it has superior alternatives for deploying capital, including expanding its rental portfolio (targeting ~Rs 10,000 crore in annual rental income) and entering new markets like Mumbai. Transcripts +5
The opportunity cost of losing the Sector 108 deal is significant—estimated at Rs 6,000-8,000 crore in potential project revenue over its lifecycle—but DLF clearly calculated that the premium required to win would compromise project economics. Historical context supports this caution: DLF's record Gurgaon acquisition in 2018 was priced at Rs 127 crore per acre. M3M's Rs 147 crore per acre bid exceeds even that benchmark, particularly notable given the eight-year gap and different market conditions.
The Auction Mechanism as Competitive Catalyst
The Noida Authority's auction design played a crucial role in driving the aggressive bidding. The reserve price of Rs 835 crore served as a psychological anchor, but the transparent e-auction format, with minimum bid increments of Rs 2,000, encouraged competitive escalation. The structured payment schedule—30% within 30 days, followed by 20% tranches at 90, 150, and 210 days—favored well-capitalized developers, effectively creating a barrier to entry for smaller players and intensifying competition among established giants like M3M and DLF.
Perhaps more importantly, the cumulative auction value of Rs 3,300 crore across five parcels created momentum effects. Early high bids, such as Godrej Properties' Rs 331.75 crore for a 4.95-acre residential plot in Sector 151 (a 35% premium over its Rs 245.74 crore reserve), established a premium tone. Max Estates' Rs 700 crore acquisition in Sector 105 and M3M's own prior Rs 400 crore commercial plot win in January 2025 provided additional pricing benchmarks. This sequence of high-value transactions validated the market's potential and created a bandwagon effect that encouraged aggressive bidding.
For M3M, these benchmarks offered validation. The company's own track record in Noida, including successful execution of prior projects, provided confidence that it could justify the premium through superior product design and timely execution. For DLF, however, the same benchmarks likely reinforced concerns about overheating. The company's historical discipline—evidenced by its conservative leverage metrics and focus on annuity income streams—made it unwilling to chase escalating prices beyond what its models deemed margin-accretive.
Project Economics: Confidence vs. Margin Pressure
M3M's aggressive bid implies strong confidence in achieving premium pricing for the end product. To justify the Rs 147 crore per acre land cost, M3M likely assumes sale prices in the range of Rs 12,000-15,000 per square foot for residential components and Rs 8,000-10,000 per square foot for commercial space. The company is probably targeting internal rates of return (IRR) in the 18-25% range, which is typical for luxury residential developments in prime NCR locations.
However, the premium land cost creates significant margin pressure. In a typical real estate project, land costs represent 20-35% of total project cost. At Rs 147 crore per acre, land alone could account for 35-40% of total project cost for a luxury development, leaving less room for construction, financing, marketing, and profit. Industry benchmarks show that ultra-luxury developers like Oberoi Realty consistently report net margins of 39-42%, while mid-market developers achieve 10-18%. M3M's premium land cost pushes its potential margins toward the lower end of this range, requiring exceptional execution and robust market absorption to maintain viability.
The break-even analysis is unforgiving. A 10% decline in sale prices or a 20% construction cost overrun could reduce project IRR from 22% to 12-14%, significantly impacting financial viability. This sensitivity to market conditions underscores the high-risk nature of M3M's strategy. The company is betting that the Noida Expressway corridor will continue its strong performance—property prices in Noida rose 13.7% year-on-year in Q4 2025—and that its brand can command premium pricing despite the elevated cost base.
The Future Landscape of Noida Real Estate
The outcome of this auction has significant implications for the future competitive dynamics in Noida's real estate market. M3M's victory strengthens its position as an aggressive challenger to established players like DLF. The company now has multiple parcels in strategic Noida locations, creating geographic synergies and establishing pricing leadership in the corridor. This cluster effect could provide operational efficiencies and enhanced market positioning.
For DLF, the loss represents a missed opportunity to deepen its presence in a growth market. The company currently has only one land parcel in Noida and has maintained a cautious approach to the region despite acknowledging it "continues to be one area of interest". While DLF's disciplined approach preserves capital and protects margins, it risks ceding market share and strategic positioning to more aggressive competitors like M3M. Transcripts
Looking ahead, the intense competition for prime land parcels is likely to reshape project launches and pricing power in Noida. M3M's Rs 147 crore per acre benchmark sets a new reference point for future auctions, potentially elevating land costs across the corridor. This could pressure developers to launch projects at higher price points, testing the market's appetite for premium real estate. At the same time, the presence of multiple well-capitalized developers—including Godrej Properties, Max Estates, and now M3M with expanded holdings—could accelerate infrastructure development and enhance the overall attractiveness of the Noida Expressway as a destination.
Ultimately, the Sector 108 auction was more than a transaction; it was a statement of intent. M3M signaled its willingness to take calculated risks to secure growth and market dominance. DLF reaffirmed its commitment to financial discipline and sustainable value creation. As the Noida market continues to evolve with infrastructure catalysts like the Jewar Airport, these divergent strategies will be tested by market realities. The developer that best aligns risk-taking with execution capability and market conditions will likely emerge as the long-term winner in this high-stakes game.