Hero MotoCorp’s September 2026 sales numbers tell an interesting story. The company dispatched 766,348 units, marking a 12% year-on-year increase from 687,220 units in September 2025. On a monthly basis, volumes surged 34.8% from August’s 568,398 units, signaling strong momentum heading into the festive season. But behind this headline growth lies a more nuanced picture of strategic shifts, operational challenges, and market dynamics that will determine whether this momentum is sustainable.
What Drove the 12% Growth?
The standout performer was undoubtedly the scooter segment. Scooter volumes crossed the six-figure mark for the first time, reaching 100,354 units—a 64.51% jump year-on-year. Internal combustion engine scooters alone grew 60%, while Vida, Hero’s electric vehicle brand, dispatched 28,798 units with an 83% surge in VAHAN retail registrations. This wasn’t just about selling more units; it was about a deliberate shift in product mix toward higher-growth categories where Hero had historically been under-indexed. Other
Domestic market strength provided the foundation. Domestic sales rose 14.12% to 739,018 units, supported by robust consumer demand.
This gap between retail sales and dealer dispatches is crucial—it indicates genuine end-consumer demand rather than inventory stuffing. The company strategically built inventory ahead of the festive season, aligning manufacturing with peak demand patterns. Other
However, exports told a different story. International shipments fell 31% to 27,330 units from 39,638 units a year earlier. This decline highlights the volatility in global markets and underscores Hero’s continued dependence on domestic demand for growth. The company did celebrate reaching one million cumulative customers in Latin America, but export recovery remains a work in progress.
Product Mix and Pricing Strategy
Hero’s product strategy has evolved significantly. The company is aggressively targeting segments where it was previously weak—scooters, electric vehicles, and premium motorcycles. In scooters, launches like Destini 110, Xoom 125, and Xoom 160 have helped expand market share. The portfolio now ranges from ₹69,000 to ₹1.44 lakh (ex-showroom Delhi), covering key white spaces in the market. Other +1
On the pricing front, Hero implemented a 2% price hike in April 2026, ranging from ₹700 to ₹3,500 depending on the product. The company follows a structured approach to commodity cost management, passing on adverse fluctuations to customers through price increases based on cost-benefit analysis. When commodity costs rose ₹2,000 per unit in Q4 FY26, Hero achieved a corresponding ₹2,000 increase in revenue per unit. This pricing discipline, combined with cost optimization initiatives like the LEAP (Lead Efficiency Acceleration Program), has helped protect margins despite inflationary pressures. Transcript +2
Dealer Inventory and Dispatch Strategy
Dealer inventory management has been a focus area. As of the latest data, dealer inventory stands at approximately 5 weeks—down from earlier levels. The company has actively reduced channel stock, entering the new financial year with healthier inventory levels. For EV scooters specifically, inventory is on the lower side nationally, indicating single-digit days of stock. This cautious approach to inventory building, especially in EVs, reflects management’s disciplined execution. Transcript +1
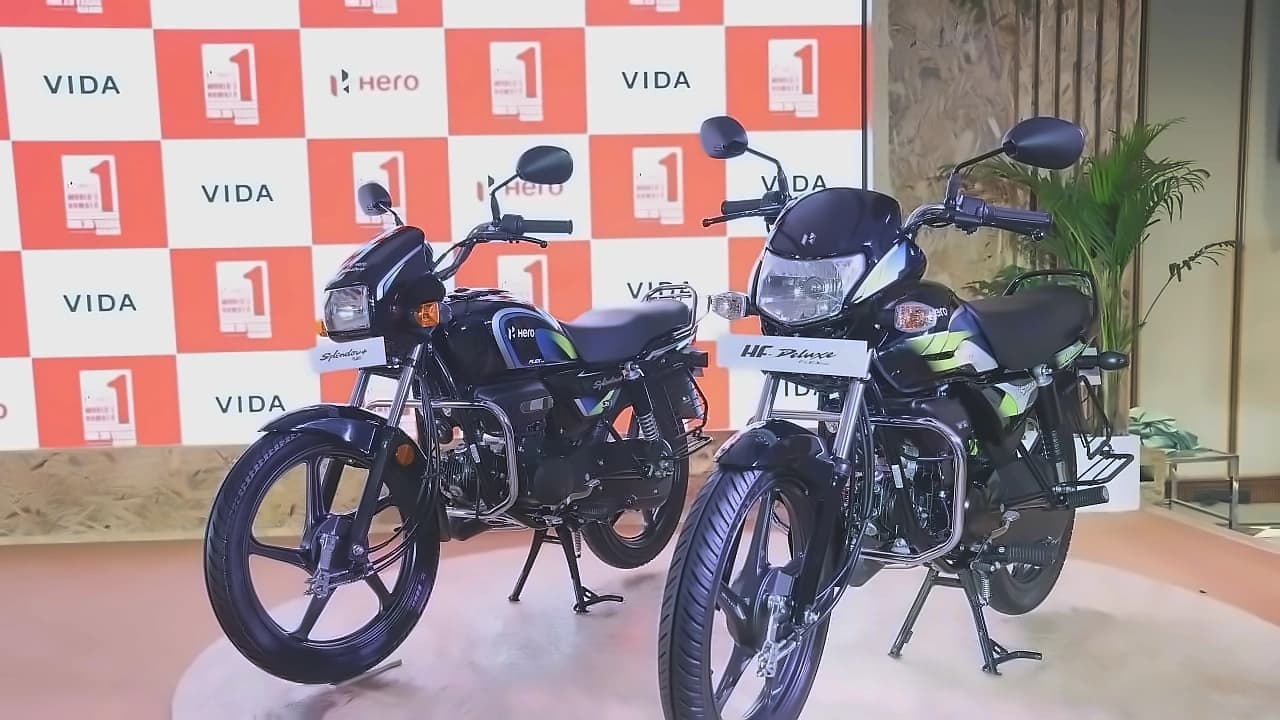
The dispatch strategy is tightly aligned with festive demand. During the festive season, Hero scaled production to 2.3 million units, demonstrating its ability to meet demand surges. Key manufacturing achievements include scaling HF Deluxe Pro production to 30,700 units monthly and expanding Vida production to 15,800 units through multi-sourcing and capacity augmentation. The company also strengthened its supply chain to support this scaling, diversifying magnet sourcing and reinforcing supply networks for new markets. Other +2
Operational Transformation Under CEO Harshavardhan Chitale
His appointment was explicitly designed to accelerate Hero’s shift toward electric vehicles and new mobility platforms. Under his leadership, Hero has implemented significant operational improvements.
Capacity expansion has been a priority. The company added 2,500 units per day of extra scooter capacity across Vida and all scooters combined, including 1,500 units per day specifically for ICE scooters. Splendor capacity increased by 2,000 units per day (approximately 50,000 per month) to prepare for the festive season. Vida capacity is ramping from 15,000 units in Q1 FY26 to 30,000 units, with plans to reach 45,000 units. Two-thirds of this capacity expansion is complete. Transcript +2
Cost optimization has been equally important. The LEAP program, described as a “relentless focus on cost and design for cost,” is yielding quarterly improvements in unit economics. During Q1 FY27, despite 4.5% commodity inflation, the company improved mix through higher premium variants, rationalized noncritical expenses, accelerated cost savings, and leveraged operating scale. These efforts limited EBITDA margin decline to 120 basis points despite a 300 basis point gross margin contraction. Transcript +2
“We Have Started”—Progress and Challenges
The company has gained market share in five of six strategic categories (entry, premium, scooters, EV, parts, and exports) in Q3 FY26 itself. Scooter sales volumes skyrocketed 87% year-on-year in Q1 FY27. Vida EV is scaling rapidly, though it still trails TVS Motor, Bajaj Auto, and Ather Energy in volumes. The premium segment push through the Harley-Davidson partnership is underway, though the Mavrick 440’s discontinuation shows the challenges ahead. Transcript
The 12% growth doesn’t mask the challenges Hero faces. Commodity cost inflation remains a persistent headwind. Q1 FY27 faced “transitionary commodity cost pressures” due to the West Asia conflict, triggering inflationary spikes across oil, gas, freight, foreign exchange, steel, aluminum, and precious metals. Management expects a marginal uptick in input cost inflation for Q2 FY27. Transcript +1
The EV business is still in a “build-out phase.” While some models are now gross margin positive, EBITDA breakeven is targeted at 25,000-30,000 units per month, expected in a couple of years. Total P&L investment in Vida remained flat sequentially at approximately ₹230 crores in Q1 FY27. Increased competition in the EV space is likely to lead to price wars, impacting margins. Transcript +2
Market share dynamics are concerning.
Honda Motorcycle & Scooter India holds 25% share, narrowing the gap substantially. TVS has galloped to nearly 20% share from just 13% over the past decade. The entry-level segment, which once made up 65% of Indian motorcycle sales, has shrunk to around 44%, creating structural challenges for a company historically dependent on this segment. Transcript
Revenue and Margin Outlook
For Q2 FY27, analysts project revenue in the range of ₹13,500-14,000 crore, representing approximately 10-15% year-on-year growth from Q2 FY26’s ₹12,218 crore. This projection is based on volume growth, mix improvement toward higher-value segments, and realization gains of approximately 5% driven by premium mix and price increases.
Margin performance is more nuanced. Management reaffirmed its medium-term EBITDA margin target of 14-16%. However, given commodity headwinds and mix improvement, EBITDA margin for Q2 FY27 is expected to be in the 13.5-14.5% range—potentially showing marginal improvement from Q1 FY27’s 12.97% but below Q2 FY26’s 14.45%. The key question is whether price increases of 2-3% were sufficient to absorb commodity inflation. Transcript
Analyst Sentiment and Sustainability
The consensus target price is ₹5,951, representing approximately 15.15% upside from the current price of ₹5,168. However, the stock is trading below both its 50-day and 200-day moving averages, reflecting market caution despite the strong sales performance.
Key concerns include commodity inflation and margin pressure, export volatility, EV profitability timeline, premium segment execution risk, and market share erosion. Expectations center on festive demand momentum, margin recovery, EV market share expansion, and strategic clarity from management. The September 28 analyst meeting was viewed as critical for management to outline its H2 FY27 festive season strategy.
The sustainability of the 12% growth trajectory is moderately supported in the near term by festive tailwinds, mix improvement, capacity readiness, and cost management. However, longer-term sustainability faces structural challenges from market share dynamics, competitive intensity, margin pressure, and execution complexity. Success will depend on market share stabilization, EV profitability achievement, premium segment breakthrough, margin delivery, and export recovery.
The Road Ahead
Hero MotoCorp’s September 2026 performance demonstrates that the company is executing on its strategic priorities. The 12% growth is real, driven by genuine demand rather than inventory stuffing. The product mix shift toward scooters and EVs is working. Operational improvements under Chitale are bearing fruit.
But the challenges are equally real. Market share erosion continues. Competition is intensifying across all segments. Commodity inflation and EV investment costs are pressuring margins. The premium segment breakthrough remains elusive.
The next few quarters will be critical. Can Hero sustain this growth momentum through the festive season? Can margins recover as commodity pressures normalize? Can the company gain meaningful market share in scooters and EVs? Can the premium segment strategy finally deliver?
The answers to these questions will determine whether Hero MotoCorp’s September 2026 performance marks the beginning of a sustained turnaround or just a strong quarter in a challenging transition. For now, the company has started—but there’s still work to do.