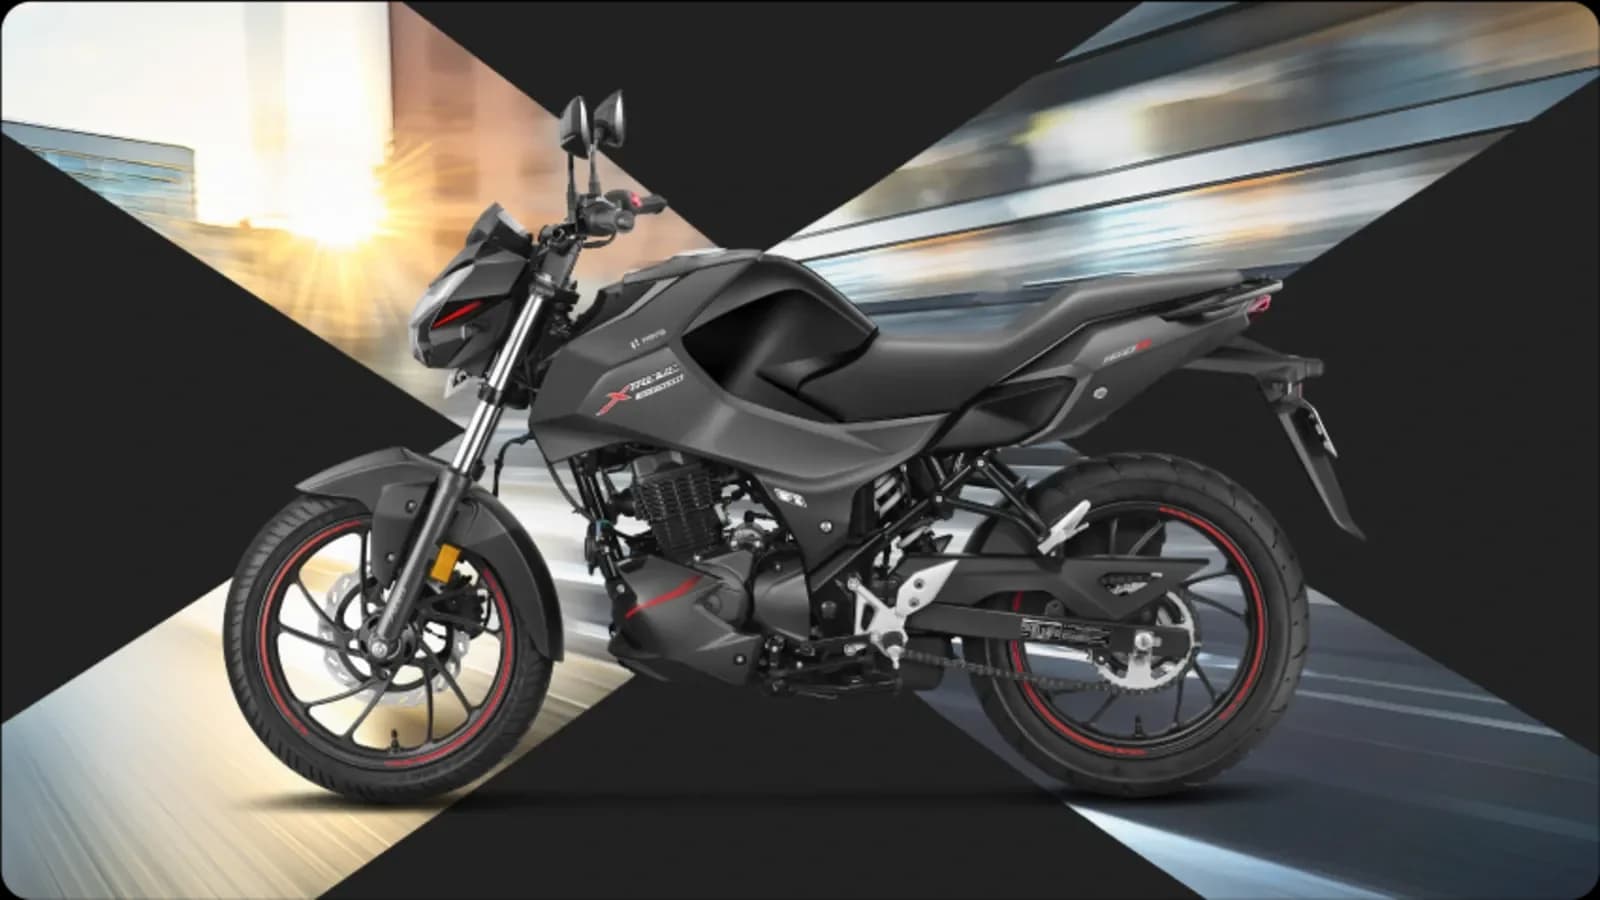
Hero MotoCorp delivered impressive Q3 FY26 results with volume sales of 16.97 lakh units compared to 14.64 lakh units in Q3 FY25, representing a strong 16% growth. The company reported revenue from operations of ₹12,328 crore versus ₹10,211 crore in the corresponding quarter last year, marking a 21% increase. The ICE scooter segment continued its strong performance with double-digit growth of 24%, backed by a strengthened product portfolio and scale-up of the Xtreme and Glamour range of motorcycles. EBITDA for Q3 FY26 stands at ₹1,810 crore, showing 23% growth, while profit before tax before exceptional item reached ₹1,896 crore, demonstrating 19% growth.
Hero MotoCorp Ltd, India's leading two-wheeler manufacturer, has scheduled its Q4 FY26 earnings announcement for Tuesday, May 5, 2026. According to an exchange filing, the company's Board of Directors will meet on this date to consider and approve the audited standalone and consolidated financial results for the quarter and financial year ended March 31, 2026. The company has not announced the specific time for result release, though in the previous two quarters, earnings were announced post-market hours. The board meeting announcement was made on April 21, 2026, at 23:21:52 +05'30 in compliance with SEBI regulations, with official notifications sent to NSE and BSE.
As reported by Economic Times, Hero MotoCorp shares are currently trading at ₹5,267.50, showing a modest increase of 0.17% today. The stock has demonstrated impressive 3-year returns of 114.53% and monthly returns of 0.13%, though it has experienced a slight decline of 0.31% over the past month. The company's market capitalisation stands at ₹1,05,264.23 crore with a price-to-earnings ratio of 19.23 and earnings per share of ₹272.03. The stock's trading volume was 321,063 shares with an average volume of 702,980 shares for the past week.
According to reports from Upstox, Hero MotoCorp will not declare any dividend with the fourth quarter FY26 results. This decision aligns with the company's previous dividend policies and reflects its current financial position.
Morgan Stanley has maintained its Overweight rating on Hero MotoCorp while raising the target price to ₹6,537 from ₹6,471. The global investment bank expresses strong conviction in the auto volume upcycle and attractive industry outlook, though acknowledges near-term challenges including 1QFY27 margin headwinds, cost pressures, supply-chain risks, and tighter regulations. The brokerage believes Hero MotoCorp's ability to demonstrate gradual cost pass-through capabilities will be crucial for maintaining profitability during the challenging period. Looking ahead, the company anticipates continued positive momentum in the automotive sector and remains optimistic of businesses delivering well in the next quarter, focusing on leveraging favorable product mix and advancing future-ready technologies to drive growth amid an evolving market.