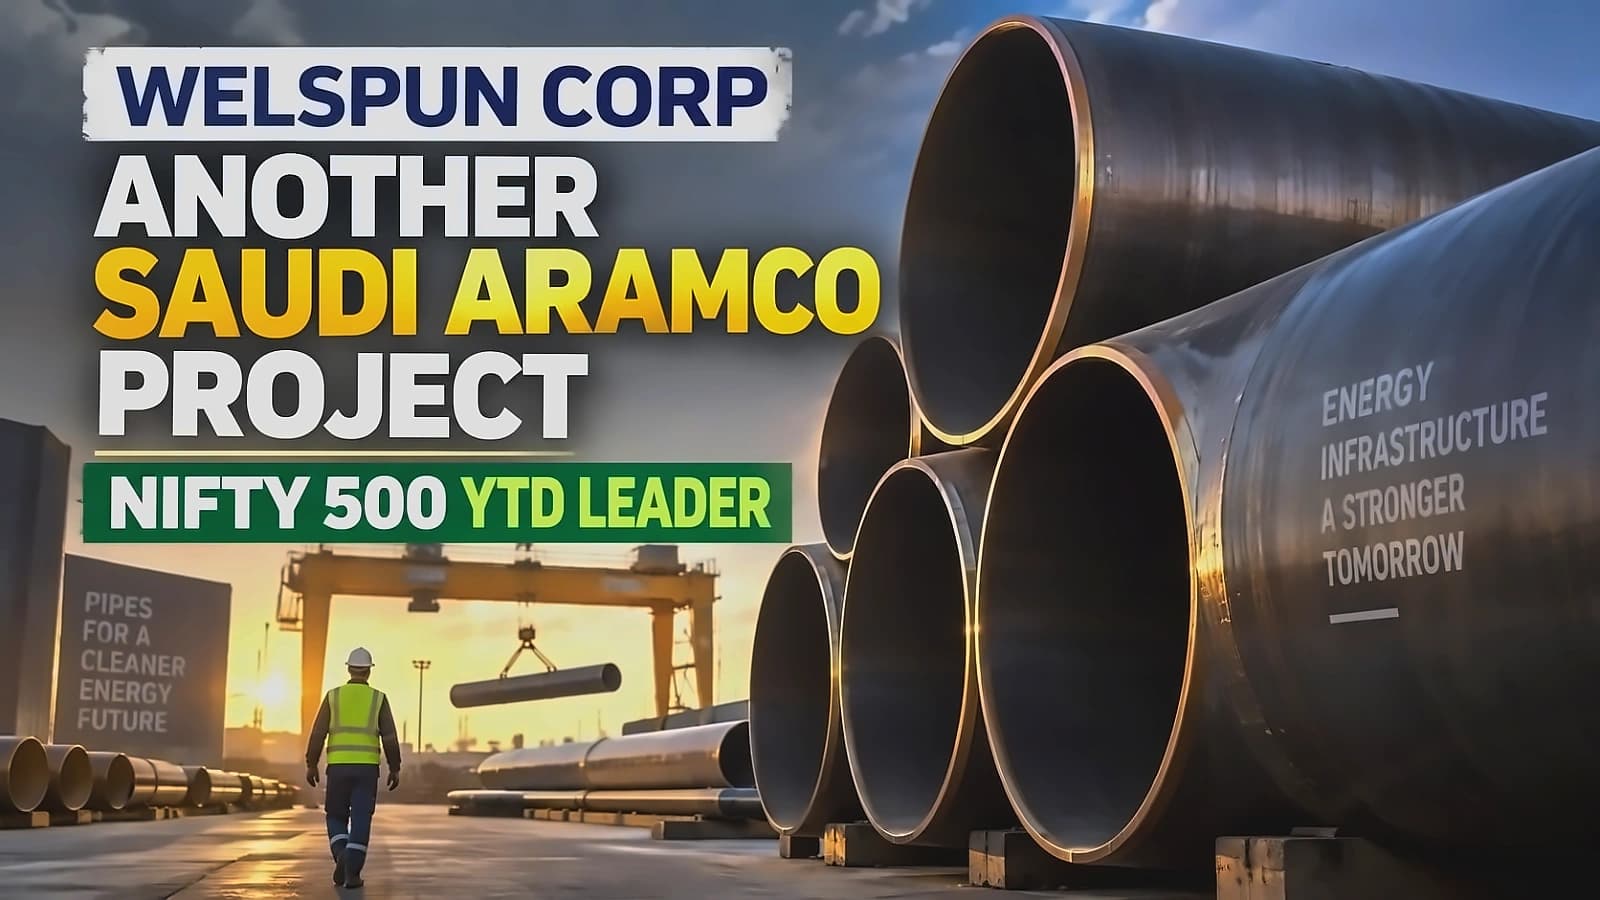
Welspun Corp has emerged as the top-performing Nifty 500 stock in 2026 after a 236% rally, overtaking AI infrastructure play HFCL's mammoth 230% gain and establishing itself as the best-performing stock on the Nifty 500 index. The sharp gains have been driven by strong investor interest in the company's oil, gas and water transmission business, with the stock surging up to 5% in Monday's trading session after its associate company East Pipes Integrated Company for Industry (EPIC) secured a significant contract with Saudi Aramco for manufacturing and supply of steel pipes. The contract is valued at ₹2,000 crore (771 million Saudi Riyal) with a six-month duration, representing approximately 43.5% of the company's average quarterly revenue of ₹4,594.50 crore. When added to existing wins, the total disclosed order book reaches ₹20,960 crore, providing coverage for 4.56 quarters of average quarterly revenue.
EPIC is Saudi Arabia's leading manufacturer of Helical Submerged Arc Welded (HSAW) pipes with fully integrated manufacturing facilities and a track record of executing large orders in the Kingdom of Saudi Arabia. This latest order comes just one month after Welspun Corp secured its largest ever order worth $1.8 billion for pipe supply from its US manufacturing facility, taking the company's order book to a record ₹42,100 crore or $4.4 billion. The company has also expanded its international footprint with an MoU signed earlier this month with Perma-Pipe International Holdings Inc. to explore setting up pipe manufacturing and advanced coating facilities in Jordan. Under the proposed partnership, Welspun Corp and Perma-Pipe plan to establish a joint venture to develop an integrated pipe manufacturing platform catering to water, oil and gas, energy and infrastructure projects in Jordan and neighbouring regional markets. Additionally, the company's wholly-owned subsidiary Welspun Global Holdings (WGHL), DIFC, UAE has approved the incorporation of a wholly owned subsidiary in Jordan for manufacturing, producing, processing and fabricating wires, tubes and pipes of iron and steel.
The stock has been a standout performer with gains of over 240% in 2026 so far, making it the best performer on the Nifty 500 index this year. The stock has witnessed fresh buying interest after the company announced the latest Aramco contract, with shares gaining over 4.5% in the past five trading sessions and 16.65% over the past month. The company's shares ended 8.1% higher at ₹2,660 last Friday and was among the top performers on the Nifty 500 index. The balance sheet remains healthy with a current ratio of 1.33x and operating cashflow of ₹3,204.30 crore in FY26, supporting capital expenditure needs and indicating effective conversion of profits into cash. The AI boom has dominated the stock market narrative in 2026, with companies linked to data centre and artificial intelligence infrastructure themes delivering some of the biggest gains, but Welspun's 236% rally has overtaken even the most prominent AI beneficiaries.
Welspun Corp demonstrated robust financial performance with consolidated net profit surging 198.64% to ₹1,046.49 crore in Q1 FY27 on a 14.91% rise in revenue to ₹4,081.12 crore over Q1 FY26. The company reported a net profit of ₹349.16 crore in the same period a year ago. Total income rose to ₹4,144.91 crore from ₹3,586.52 crore logged in Q1 FY26. The company's annual revenue has grown from ₹14,167.30 crore in FY25 to ₹16,905.40 crore in FY26, representing a YoY growth of +19.3%. In Q1FY27, the company achieved strong margin expansion with operating profit margin (OPM) at 16.96%, up from 11.68% in Q4FY26 and 13.58% in Q3FY26. The company serves customers across more than 50 countries on six continents, supported by manufacturing facilities in India, the US and Saudi Arabia, with a diversified portfolio spanning line pipes, ductile iron pipes, stainless steel bars, pipes and tubes, and TMT rebars.
Jefferies expects Welspun's total pipe-manufacturing capacity to increase 51% to 37 lakh tonnes per annum by FY27, from 24 lakh tonnes in FY26, with the expansion projected to support a 17% compound annual growth rate in volumes between FY26 and FY29. The brokerage expects EBITDA to grow at a CAGR of 32%, while earnings per share are projected to increase at a CAGR of 33% over the same period. Growth is expected to be supported by higher volumes and a greater contribution from the company's more profitable overseas operations. The company holds an estimated 30% share of the US large-diameter line-pipe market and its domestic manufacturing presence gives it an advantage over import-dependent suppliers by limiting exposure to trade barriers, reducing delivery times and improving eligibility for projects that prioritise locally manufactured products. Nuvama points to renewed opportunities following disruption to nearly 20% of LNG supply, with higher demand for pipes as restoration activities come up over the next three to five years.