Syrma SGS Technology's shares have surged 144% in 2026 as the electronics manufacturer expands beyond traditional contract manufacturing into design-led electronics manufacturing, specialised sectors and printed circuit board (PCB) production. According to reports from NDTV Profit, the stock trades at ₹1,733 per share, representing approximately 90 times earnings, above its five-year median price-to-earnings multiple of 67 times. The company reported operating revenue of ₹1,588.6 crore in Q1 FY27, up 66.7% year-on-year, with EBITDA rising 68.8% to ₹161.6 crore and net profit increasing 111.7% to ₹105.7 crore. The shift towards higher-margin design-led manufacturing is helping Syrma move up the electronics value chain and expand its presence in automotive, healthcare, defence and railways.
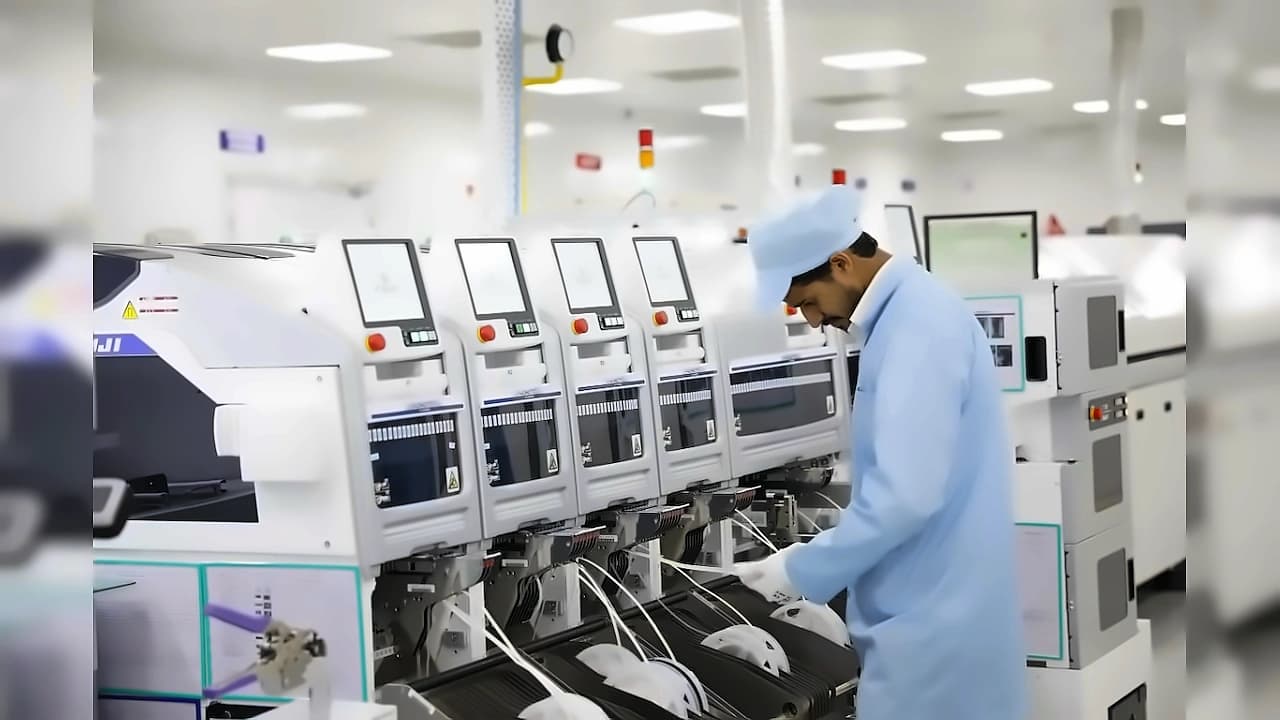
The company is increasing its focus on original design manufacturing (ODM), where manufacturers participate in product design and development rather than simply assembling products based on customer specifications. As reported by NDTV Profit, ODM revenue increased 115% to ₹270 crore in Q1 FY27, accounting for 17% of total revenue, with management planning to increase ODM's share to 18-19% in the near term and 25% over the long term. ODM revenue is expected to grow at a compound annual growth rate of 50-60% over the next several years, supported by higher margins compared to traditional electronics manufacturing services (EMS). The changing business mix is reflected in margins, with Syrma's consolidated gross margin increasing from 22.6% in FY25 to 25.6% in FY26, supported by higher contribution from ODM and exports, both of which carry higher margins than standard contract manufacturing.
Syrma is expanding its presence across multiple high-growth sectors through strategic acquisitions and partnerships. According to NDTV Profit, the company acquired a 60% stake in Elcome to enter the defence and maritime electronics sector, expecting the business to generate baseline annual revenue of ₹200-300 crore with EBITDA margins of 20-25%. The automotive segment showed strong performance with revenue growing 78% year-on-year to ₹394.9 crore, accounting for 25% of operating revenue, supported by rising electronic content in vehicles. Healthcare and MedTech revenue doubled to ₹134.5 crore, with management expecting the MedTech business to grow around 50% in FY27 with revenue targeted at more than ₹300 crore. The company has also signed a multi-year framework agreement worth more than ₹2,000 crore with a global OEM across automotive, industrial systems and healthcare, expected to reserve manufacturing capacity for two to three years.
The company's ₹1,600 crore greenfield bare-board PCB facility in Andhra Pradesh represents a major step towards expanding manufacturing capabilities. As reported by NDTV Profit, Syrma has formed a 75:25 joint venture with South Korea-based Shinyup to develop this facility, with commercial production scheduled to begin by April 2027. The facility will manufacture single-sided, double-sided and multilayer PCBs in the first phase, with plans for high-density interconnect boards, flexible PCBs and an in-house copper-clad laminate (CCL) facility in the second phase. The CCL plant will supply raw materials to Syrma and other domestic PCB manufacturers. Management expects initial capacity utilisation of 40-50% with EBITDA margins of around 10%, while at utilisation levels above 80%, the facility has estimated annual revenue potential of around ₹2,400 crore and EBITDA of ₹360-432 crore. This expansion addresses India's significant import dependency, with around 90% of domestic PCB demand currently met through imports.
Syrma is using international partnerships to access new customers and expand its manufacturing relationships with global OEMs. The company has established a 60:40 joint venture with Japan's Kaga Electronics, with management expecting the partnership to develop into a business worth ₹300 crore to ₹500 crore within three to five years. Exports grew 61% year-on-year to ₹387 crore in Q1 FY27, accounting for 24% of operating revenue, with the company securing multi-year framework agreements with international customers. The strategy forms part of Syrma's plan to become an integrated manufacturing partner for global customers diversifying their supply chains, while the company's diversified order book includes consumer electronics (30%), automotive (29%), industrials (24%), IT and railways (9%), and healthcare and MedTech (7%).