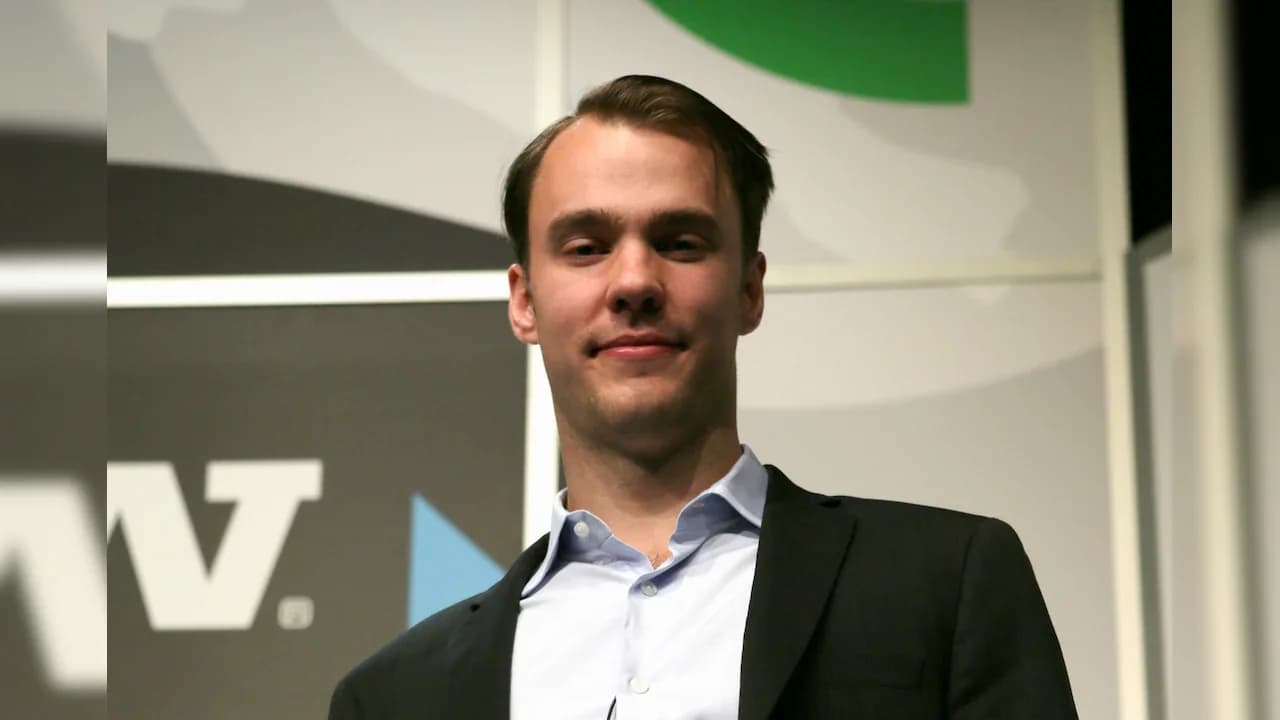
Coinbase co-founder Fred Ehrsam is seeking control of at least three Venezuelan oil fields as part of Washington's reshaping of Venezuela's oil industry, according to people familiar with the negotiations. The fields are currently operated by Alvorada Heavy Industries Ltd in the Boca, Guico and Guara blocks of Venezuela's Orinoco Belt, under contracts that US officials are considering revoking. As reported by Bloomberg News, Ehrsam has made repeated trips to Caracas since May and met senior US and Venezuelan officials while exploring investments in oil and gas, fintech and digital payments. His pursuit of Alvorada's fields illustrates the uncertain footing of existing operators, even as they move quickly to adapt to the new order. Ehrsam has emerged as one of the best-connected newcomers pursuing opportunities there, having also tried to tap connections in Washington while scouting Venezuelan energy assets. His access is particularly unusual for a crypto founder, given his previous role as Coinbase president until 2017 and his current position on the board, along with his advisory role to the White House on science and technology.
Alvorada had invested approximately $30 million to restart idle wells after entering the fields around 2023, but was required by state-owned PDVSA to work with a politically connected local contractor, adding costs even when production was halted. The company had been moving to comply with Venezuela's new hydrocarbons law and expand output when new challenges emerged from Washington. In July, Alvorada acquired small Texas producer Calistoga Energy Reserves LLC to establish a US headquarters and coordinate its Venezuela strategy from there, according to Brazilian business publication Exame. One of the people familiar with the matter noted that Alvorada is looking to engage with US officials in an attempt to maintain its investments, though the company declined to comment. Ehrsam's pursuit through Primavera, a company he co-founded to invest in Venezuela, demonstrates the complexity of navigating the current transition period, as the company has said nothing publicly and declined to comment when approached.
Venezuela holds the world's largest proven oil reserves at 303 billion barrels, according to OPEC data, but production remains severely constrained. The country still pumped only 783,000 barrels per day in 2023, highlighting the significant gap between potential and current output. Recovery will be gradual, with Rystad Energy expecting national output to grow 17% by late 2028, which would add roughly 194,000 extra barrels per day. As an Rystad Energy upstream research note states, "Execution, not geology, remains the key constraint." The payments side of Ehrsam's pitch could move faster, as Venezuela is moving toward formal dollarization, which widens the market for dollar rails and digital payment solutions.
The reshuffling is part of President Donald Trump's push to revive Venezuela's oil industry with foreign capital and boost supplies as the US replenishes strategic reserves depleted during the war with Iran. Energy Secretary Chris Wright is visiting Caracas this week and is set to showcase as many as 17 oil and gas agreements. Other contracts being reconsidered include the Ayacucho 6 project awarded to Venezuelan construction and engineering company West-Construcciones C.A. and the Bare field operated by Cavallino Oil Company. Colombia's billionaire Gilinski family and GeoPark Ltd are nearing a deal to become the operator of Bare. The overhaul also highlights a defining feature of Trump's approach: one relationship-driven system is giving way to another. Under Maduro, access often depended on ties to government insiders and officials at state-owned oil company PDVSA; under Trump, connections in Washington are increasingly shaping who gets a seat at the table. As Steven Levitsky, director of Harvard University's David Rockefeller Center for Latin American Studies, noted, the US government is "highly personalistic right now."
The government has moved to transfer assets to new operators, including transferring the assets of the Petrodelta joint venture to California-based Pacific Coast Energy Co. in May after revoking the minority stake held by DP Delta Finance BV, controlled by the family of late Venezuelan businessman Oswaldo Cisneros. In May, Venezuela's oil ministry revoked the minority stake held by DP Delta Finance BV, citing failures to meet investment and production commitments. The state deal sets clear terms for newcomers, with a White House fact sheet dated August 31 granting North American Blue Energy Partners 100-year concessions on 17 fields that hold about 65 billion barrels. Washington maintained leverage by taking a 35% equity stake in the venture's parent and retaining the ability to buy a fifth of production at cost. In August, the Trump administration pressured Florida oil magnate Harry Sargeant III to sell his minority interest in North American Blue Energy Partners, Venezuela's second-largest private oil producer, after the Treasury Department froze assets belonging to his offshore holding company, ultimately resulting in a $300 million sale.