Sign in to fuzzto save your conversations, follow your research and come back anytime.

In the news

Privi Speciality Chemicals Q1 profit jumps 36% to ₹84.21 cr
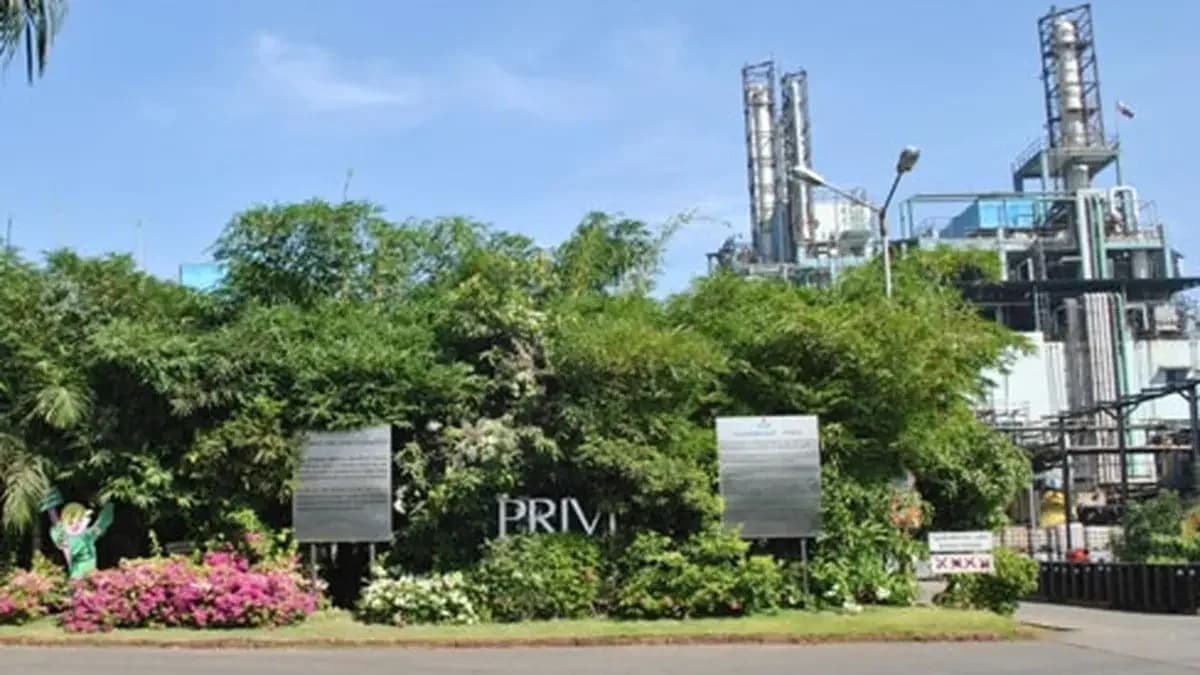
InCred Sets ₹4,796 Target for Privi Speciality Chemicals
MarketSmith India Recommends Navin Fluorine, Allied Blenders
MarketSmith India Recommends 2 Stocks for April 20; Vaishali Parekh Adds 3 More
Company insights, generated from the most recent coverage.
Q1 FY27 gross margin collapsed 650 bps YoY from 51% to 44.2% despite 19.22% revenue growth — input cost pressure is eroding profitability even as EBITDA held at ~24.58%.
Balance sheet is strengthening fast: Net Debt/EBITDA fell from 2.0x to 1.29x and ROCE improved to 21.70% from 18.71%, supporting the capex-led expansion plan.
Phase-1 capacity expansion (48,000 to 54,000 MT) missed its September 2026 commercialization target — execution delays risk the growth story the market has priced in.