Sign in to fuzzto save your conversations, follow your research and come back anytime.

Deepak Nitrite Limited is an Indian chemical manufacturing company that produces Advanced Intermediates and Phenolics. The company operates through Strategic Business Units including Basic Chemicals, Fine and Speciality Chemicals, and Performance Products. It has manufacturing facilities in Gujarat, Maharashtra, and Telangana, and exports to over 45 countries. The company's product portfolio includes sodium nitrite, sodium nitrate, nitro toluidines, fuel additives, optical brightening agents, phenol, acetone, and isopropyl alcohol. These products cater to various industries such as colorants, rubber chemicals, explosives, dyes, pharmaceuticals, agrochemicals, and personal care. Deepak Nitrite has expanded its operations through acquisitions, capacity expansions, and the establishment of subsidiaries. The company has also undertaken significant projects, including the commissioning of a phenol and acetone plant through its subsidiary Deepak Phenolics Limited.
In the news
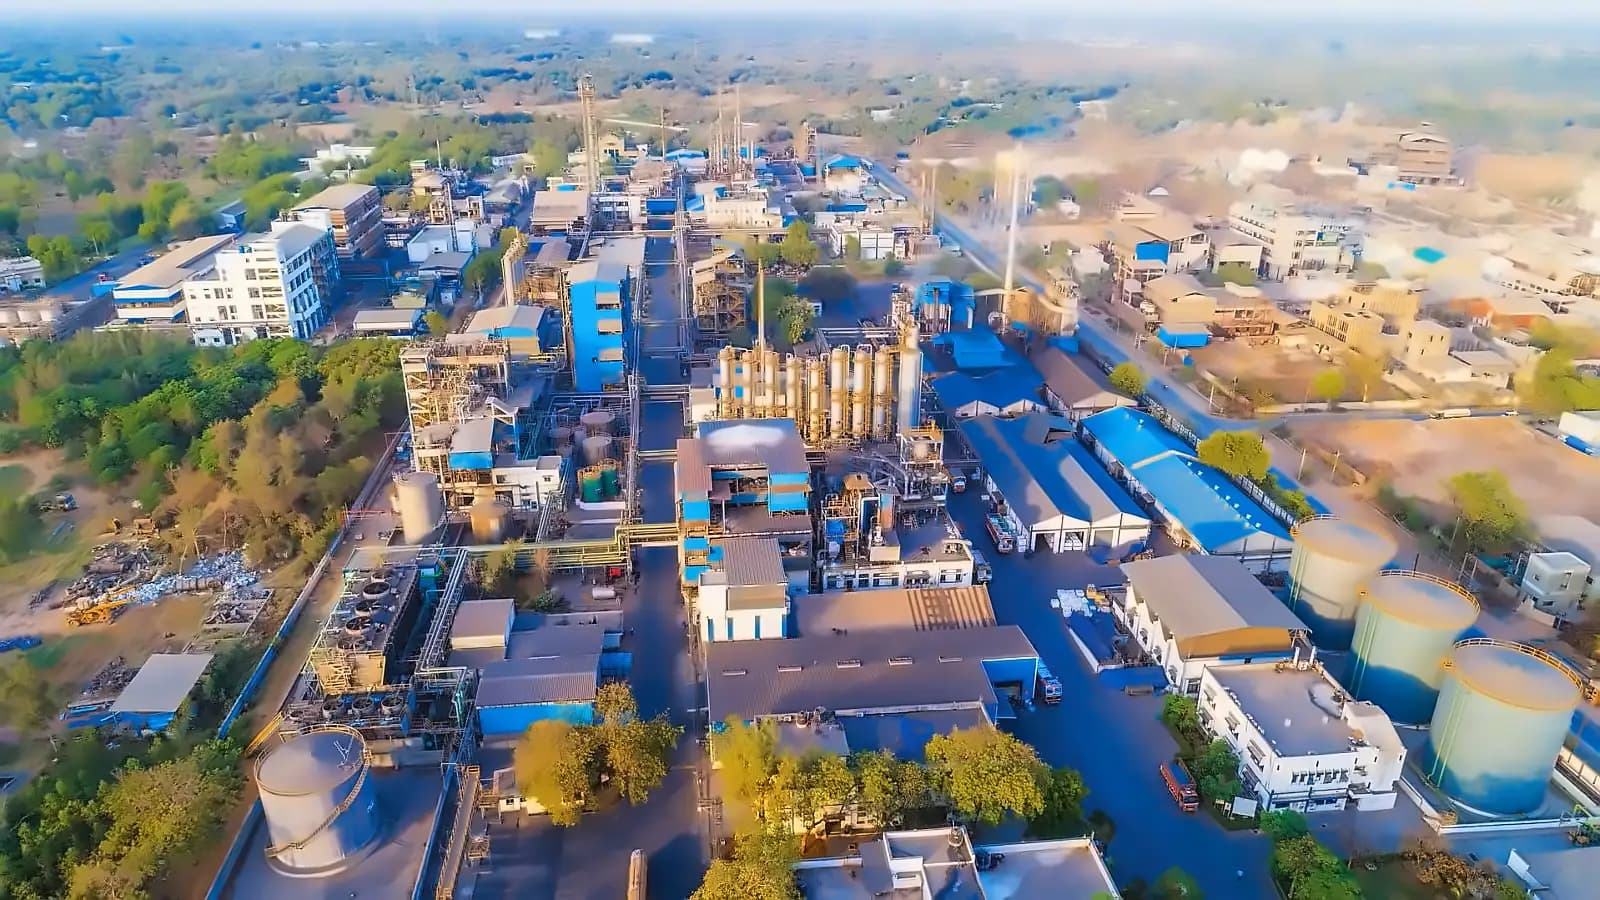
Deepak Nitrite subsidiary commissions ₹300 cr plant in Gujarat
Top 3 stocks to buy today: NLC India, Deepak Nitrite, Hindustan Copper
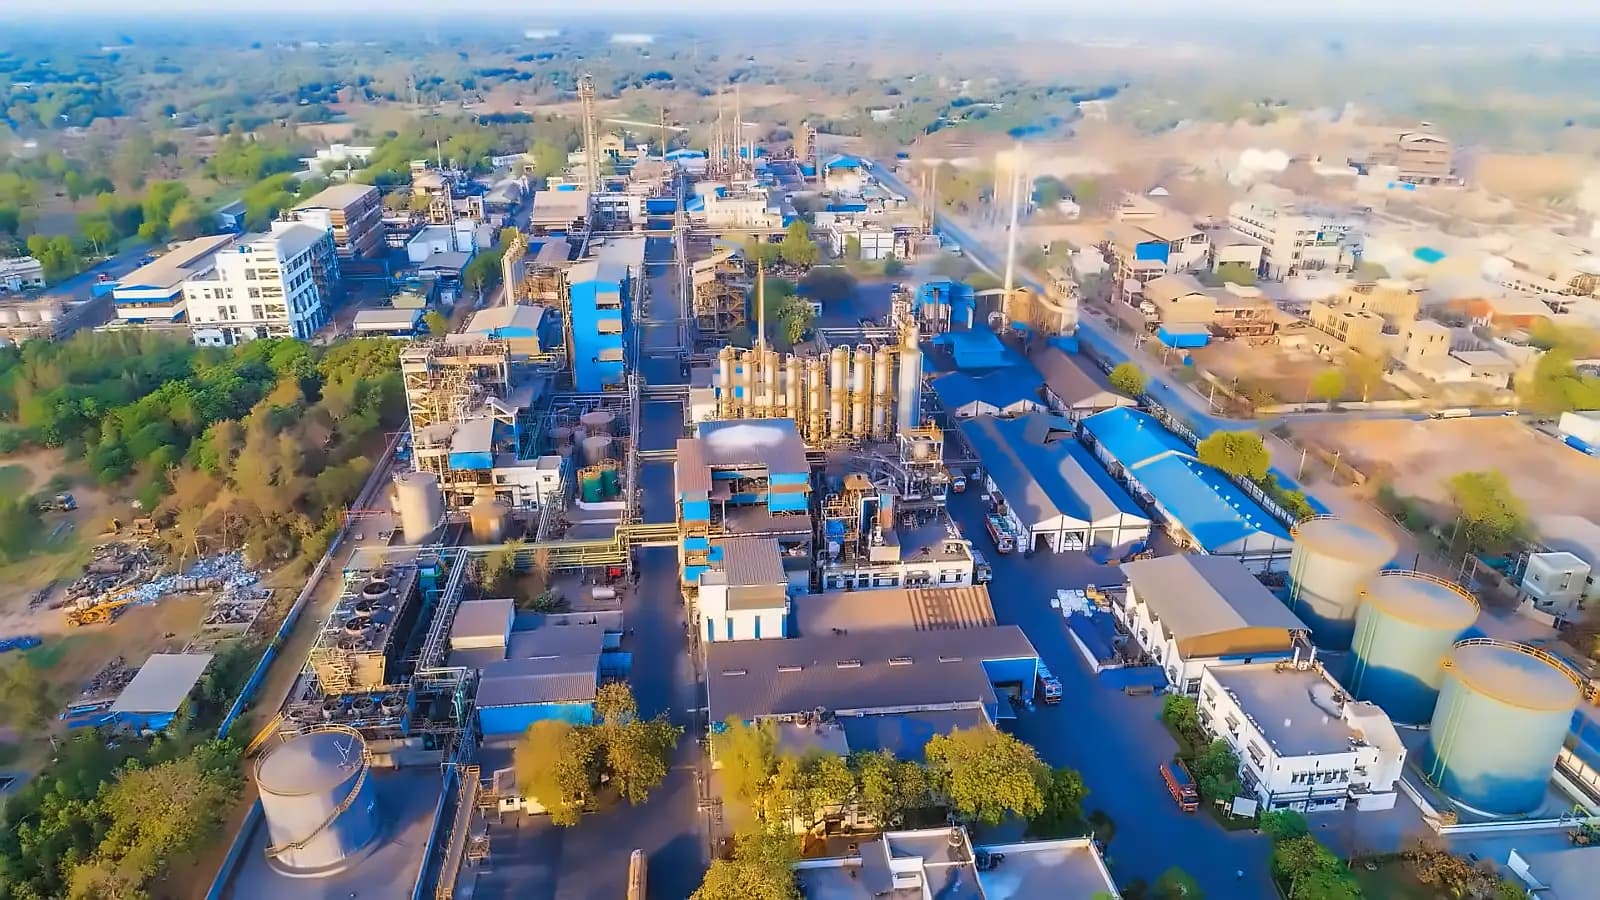
Deepak Nitrite Q1 profit triples, shares gain 2.3% on strong results
Trade Spotlight: 10 stocks for July 17 with technical targets
BDL shares tumble 8% on weak Q4 results, brokerage downgrades
Gift Nifty up 26 points; positive opening signals for today

Deepak Nitrite Q4 profit up 10% to ₹220 cr, margins surge 319 bps

Deepak Nitrite reappoints Maulik Mehta, names Meghav as Deputy MD

Deepak Nitrite shares jump 6% on Q3 results announcement
The Quarter story
The two most recent quarterly results, compared side-by-side.
Deepak Nitrite posts record revenue and profits in Q1 FY27, marking a strong recovery after a mid-cycle slowdown.
Consolidated revenue grows from ₹1,914 Cr to ₹2,592 Cr from Q1 FY26 to Q1 FY27, reflecting sustained demand recovery.
Finance costs rise from ₹9 Cr to ₹23 Cr from Q4 2024-25 to Q1 FY27, indicating higher debt servicing obligations.
Consolidated EBITDA margin expands from 11% to 21% from Q1 FY26 to Q1 FY27, confirming strong cost optimization.
Other expenses increase from ₹135 Cr to ₹168 Cr from Q4 2024-25 to Q1 FY27, signaling rising operational overheads.
Phenolics segment EBIT surges from ₹118 Cr to ₹418 Cr from Q1 FY26 to Q1 FY27, driving overall profitability.
Depreciation and amortization grow from ₹51 Cr to ₹64 Cr from Q4 2024-25 to Q1 FY27, reflecting ongoing capacity expansion.
Consolidated PAT jumps from ₹100 Cr to ₹345 Cr from Q3 FY26 to Q1 FY27, highlighting robust earnings recovery.
Company insights, generated from the most recent coverage.
Up 3.32% to ₹1,605 at 09:45 AM on Oct 8 while Nifty was down 0.3% — clear sector-led relative strength, not market beta.
Rally broke resistance R1 at ₹1,597 with R2 at ₹1,640 next, but volume was only 0.35x the 1-month average — breakout is unconfirmed and sentiment-driven.
Stock still trades ~15% below its 52-week high of ₹1,890 after a ~10.9% one-year correction, so today's move is recovery off support rather than momentum continuation.