Global data centre spending is projected to reach $31.6 trillion through 2050 to meet the world's growing appetite for artificial intelligence, according to PricewaterhouseCoopers LLP. The investment boom, described as having no precedent in history, could potentially exceed $50 trillion if AI adoption accelerates beyond PwC's central scenario forecast. For comparison, the US gross domestic product is roughly $30 trillion, making this investment level unprecedented in scale. As Clara Cutajar, global infrastructure leader at PwC Australia, noted, "The AI buildout is not a rising tide that will naturally lift all boats. Capturing this investment requires active positioning."
The US will capture nearly $15.1 trillion of the projected data centre spending, representing the largest share globally, according to PwC's inaugural Global Data Centre Outlook released on September 2, 2026. The Asia-Pacific region will follow at $8.2 trillion, Europe at $5.6 trillion, the Middle East at $1.1 trillion, and Africa at $255 billion of the cumulative capital expenditure. On an annual basis, global data centre spending will increase from approximately $800 billion this year to $1.1 trillion in 2030 and $1.8 trillion in 2050. However, geopolitical changes could significantly reshape the market - if tighter export controls disrupt advanced GPU supplies, cumulative global investment could fall to $25.5 trillion through 2050, around $6 trillion below the central forecast. PwC commissioned Oxford Economics Ltd. to model data centre capital expenditure, with the report covering 46 countries and territories, and five regions, which account for the bulk of global economic activity and digital infrastructure investment.
The AI infrastructure cycle underway dwarfs previous technological transformations including railways, electrification, and the internet, with the cycle resetting every 4 to 6 years and showing no signs of ending. Unlike traditional capital expenditure cycles, recurring chip upgrades will account for most of the investment, with graphics processing units, servers, storage systems, and networking equipment requiring routine replacement. ICT equipment is expected to account for 93% of total data centre capex by 2050, compared with 70% today, creating a recurring investment requirement as AI workloads expand. China and India are expected to drive the largest share of incremental demand, supported by large populations, rapidly expanding digital economies, and substantial headroom for AI integration in business and consumer activity. The bulk of spending will go into what fills the data centres — hardware from companies such as global AI chip leader Nvidia Corp., with the tech industry setting up new computing facilities across the planet at a rapid clip. Most of the projected spending will go towards the equipment operating inside data centres rather than land or construction, with AI processors and related hardware accounting for a substantial share.
Despite strong global demand, at least 75 projects worth about $130 billion were blocked or delayed by local opposition during the first quarter of 2026, according to research group Data Centre Watch. Protesters cite concerns about environmental impact, resource consumption, and broader societal implications of AI adoption, including how AI could upend employment and society. The tech industry is actively working to address these backlash concerns that threaten to slow down the data centre buildout across the planet. "The $31.6 trillion question isn't whether the capital exists. It does," the report noted. "Nor is the question whether the demand is real. It is. The question is which regions, operators, and institutions are positioned to capture it and which aren't."
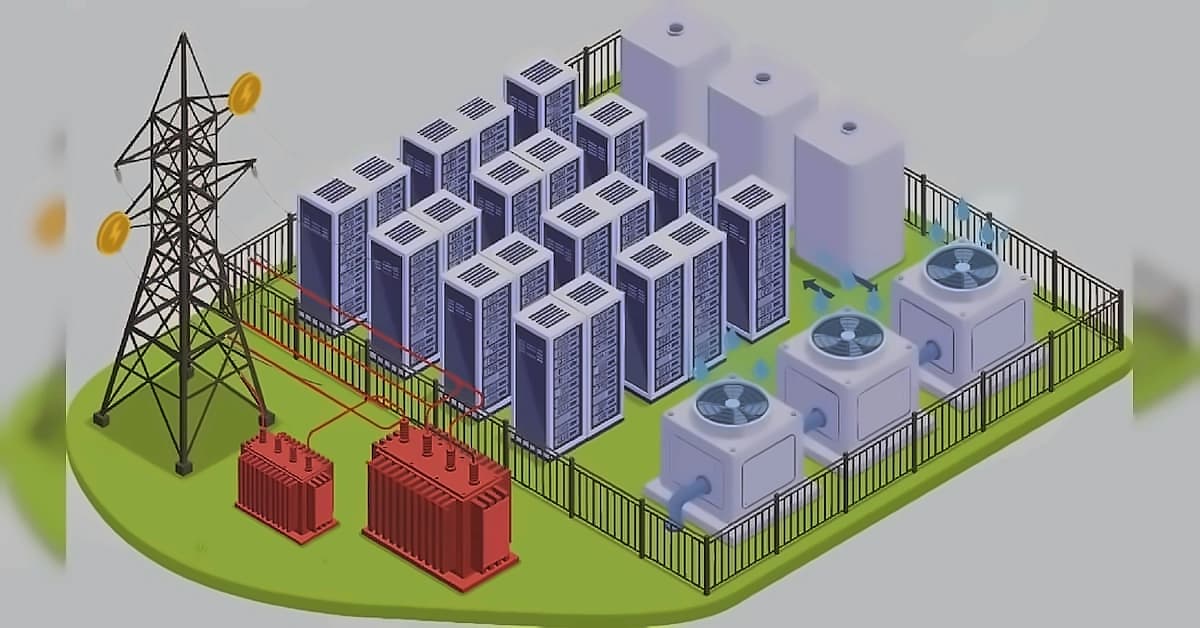
According to PwC's report, power availability, data sovereignty requirements, and semiconductor supply chain flows will determine which regions capture the investments. Power emerges as the foremost factor shaping where AI infrastructure investment occurs, with affordable, reliable, and increasingly low-carbon electricity at scale being the hardest requirement for many markets. Much of the forecast hinges on how fast reliable electricity supply for data centres can be established, according to the report. Connectivity, security, policy certainty, community consent and access to GPUs will also influence global locations of AI facilities. A shift towards digital sovereignty would have a smaller impact on total spending but alter its geography, with PwC estimating cumulative investment would reach $29.5 trillion, with capital redistributed into markets with stronger domestic demand rather than established global hubs. While the researchers' projection assumes a fairly open trading system where chips move freely across borders, disruptions in semiconductor supply chains could cut global investment by nearly 20%.