The Central Board of Direct Taxes (CBDT) has significantly simplified TDS compliance for residents purchasing immovable property from non-residents, effective October 1, 2026. According to CBDT Notification No. 121/2026, eligible resident individuals or HUFs can now undertake prescribed TDS payments and reporting without first obtaining a separate Tax Deduction Account Number (TAN). This represents a major shift from the previous TAN-oriented compliance structure to a transaction-specific PAN-based reporting framework. The new compliance mechanism is facilitated through the insertion of a dedicated Schedule E in Form No. 141, which creates a specific reporting mechanism for residents purchasing immovable property from non-residents. As per Mint, the Finance Ministry has introduced this PAN-based compliance mechanism, removing the need for a separate TAN for what could be a one-off property transaction.
October 2026 brings several important income tax compliance deadlines for taxpayers, employers, and specified entities. According to reports from Mint, taxpayers must keep in mind both the Income-tax Act, 1961, and the Income-tax Act, 2025 for these requirements. The month includes key deadlines for ITR filing, quarterly TDS returns, and specialized forms like Form 141 under the new 2025 framework. The ITR for Assessment Year 2026-27, covering income earned during FY 2025-26, continues to be governed by the Income-tax Act, 1961, while the new Act applies to Tax Year 2026-27 onwards. The CBDT's recent amendments to Rules 215, 218 and 219 have further streamlined compliance processes, particularly for property transactions involving non-residents.
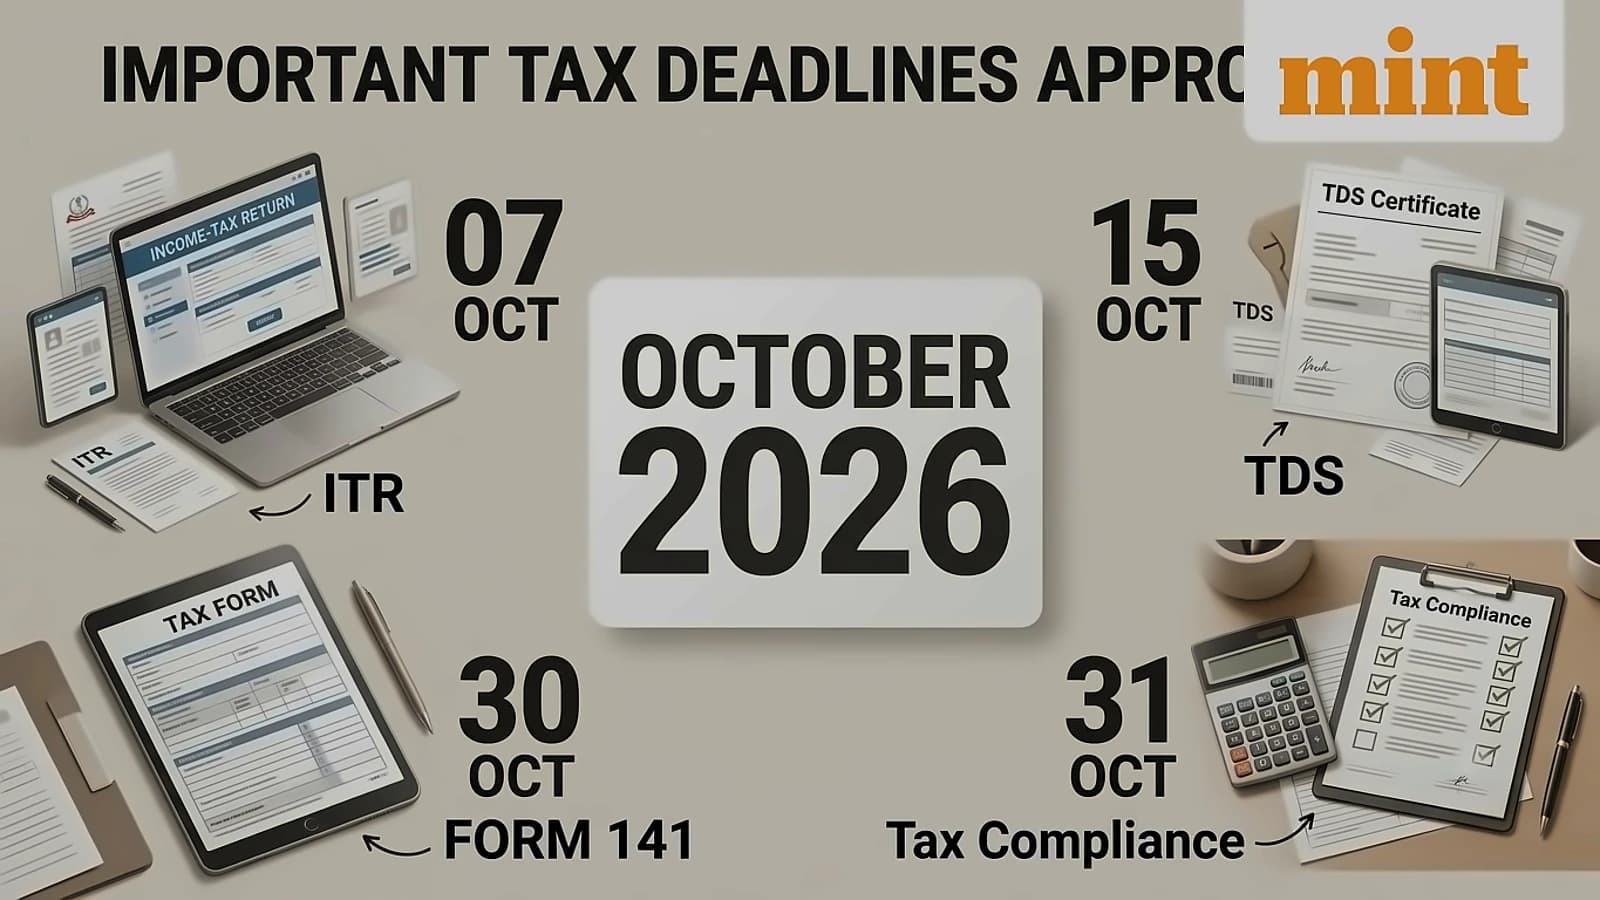
October 7 marks the deadline for TDS/TCS payments for September 2026 deductions and quarterly TDS payments for July-September 2026. As reported by Mint, this applies to tax deducted or collected during September that must generally be deposited by October 7. The general rule under the Income-tax Act, 1961 requires TDS to be deposited by the seventh day of the following month, with the Income-tax Rules, 2026 retaining the same timeline under the new Act. Certain specified transactions, including those covered by the new Form 141, follow a separate 30-day deadline for compliance. The CBDT's recent amendments have expanded Rule 218 to cover consideration for transfer of immovable property paid or credited by a resident individual or HUF, while Rule 219 has been amended to include such transactions within Form No. 141 compliance.
October 30 marks the deadline for Form 141 submissions covering September 2026 deductions under the Income-tax Act, 2025. According to Mint, Form 141 serves as a consolidated challan-cum-statement replacing separate forms 26QB, 26QC, 26QD and 26QE for specified transactions. The form covers specified TDS on immovable property transfers, rent, contractor/professional payments, and virtual digital asset transfers. The Income Tax Department states that Form 141 must be furnished within one month from the end of the month in which the tax is deducted, with the deducted amount also paid to the Central Government within 30 days from the end of that month. The form is filed through the income tax e-filing portal under the Income-tax Act, 2025, and the CBDT's recent amendments have further enhanced Form 141 by inserting a dedicated Schedule E for property purchases from non-residents, which requires details of the property address, type of immovable property, and all buyers including their PAN, names and respective proportion of sale consideration.
October 31 represents the most significant deadline for income-tax return filing for AY 2026-27, applicable to taxpayers whose accounts require audit but are not covered by transfer-pricing provisions. As reported by Mint, this deadline is particularly relevant for taxpayers subject to section 92E transfer-pricing provisions, who face an extended ITR deadline of November 30, 2026. The return relates to income earned during FY 2025-26 and is governed by the Income-tax Act, 1961, with the Income Tax Department clarifying that the old Act continues to govern AY 2026-27 returns even though they are filed after the new Act came into force. The tax audit report for these cases has a separate deadline of September 30, 2026, while taxpayers covered by transfer-pricing provisions have an ITR deadline of November 30, 2026, with the relevant audit report due by October 31. The month also includes specialized filings for transfer pricing reports (Form 3CEB), audit reports under section 44AB, and various deduction claims under sections 80JJAA, 80LA, and others.
October 31 brings compliance requirements for several quarterly TDS and TCS statements for the July-September 2026 quarter under the Income-tax Act, 2025. According to Mint, Form 138 requires employers and specified banks to file for TDS deducted on salary, pension or specified interest income, with the form being earlier known as Form 24Q. Form 140 covers persons deducting TDS on non-salary payments made to residents, covering payments such as commission, brokerage, professional fees, rent and other applicable payments. Form 143 requires persons responsible for collecting tax at source on specified goods and transactions, while Form 144 covers specified TDS on non-salary payments made to non-residents. Form 142 requires eligible virtual digital asset exchanges to furnish the prescribed quarterly statement relating to tax deducted on VDA transfers, with the Income Tax Department listing Form 142 as the new form corresponding to the earlier Form 26QF. These forms are generally relevant to employers, businesses, deductors, collectors and specified entities rather than most individual salaried taxpayers.