The Foreign Assets of Small Taxpayers - Disclosure Scheme (FAST-DS) was announced in the Union Budget 2026 and notified on 14 August 2026, coming into effect on 16 August 2026. According to reports from The Times of India, eligible taxpayers can make declarations until 31 December 2026 for foreign assets that may have been overlooked years later, including bank accounts opened while studying abroad, stocks received under ESOPs or RSUs, overseas brokerage accounts, and foreign pension contributions. The scheme addresses taxpayers who inadvertently missed disclosing foreign financial assets in their India tax returns, with the Finance Minister clarifying that such omissions do not necessarily amount to deliberate tax evasion.
FAST-DS separates eligible taxpayers into two broad categories based on the nature of the reporting lapse. As reported by The Times of India, Category 1 covers undisclosed foreign income or assets that meet prescribed conditions, with the effective cost potentially reaching 60% of the asset's fair market value and undisclosed income. Category 2 applies to foreign assets from explained sources but not reported, subject to a flat fee of ₹1 lakh under prescribed conditions. The distinction is central to the scheme as it directly determines eligibility, amount payable, and relief available to taxpayers.
The financial implications under the two categories differ significantly, as reported by The Times of India. For Category 1 undisclosed foreign income or assets, the effective cost can equal 60% of the asset's fair market value and undisclosed income. Category 2, covering foreign assets from explained sources but not reported, applies a flat fee of ₹1 lakh subject to prescribed conditions. Once taxpayers make a valid declaration, pay the prescribed amount, and meet scheme conditions, the disclosed foreign income or asset is regularised, providing protection from further tax, penalty, and prosecution under the Black Money Act for the declared income or asset.
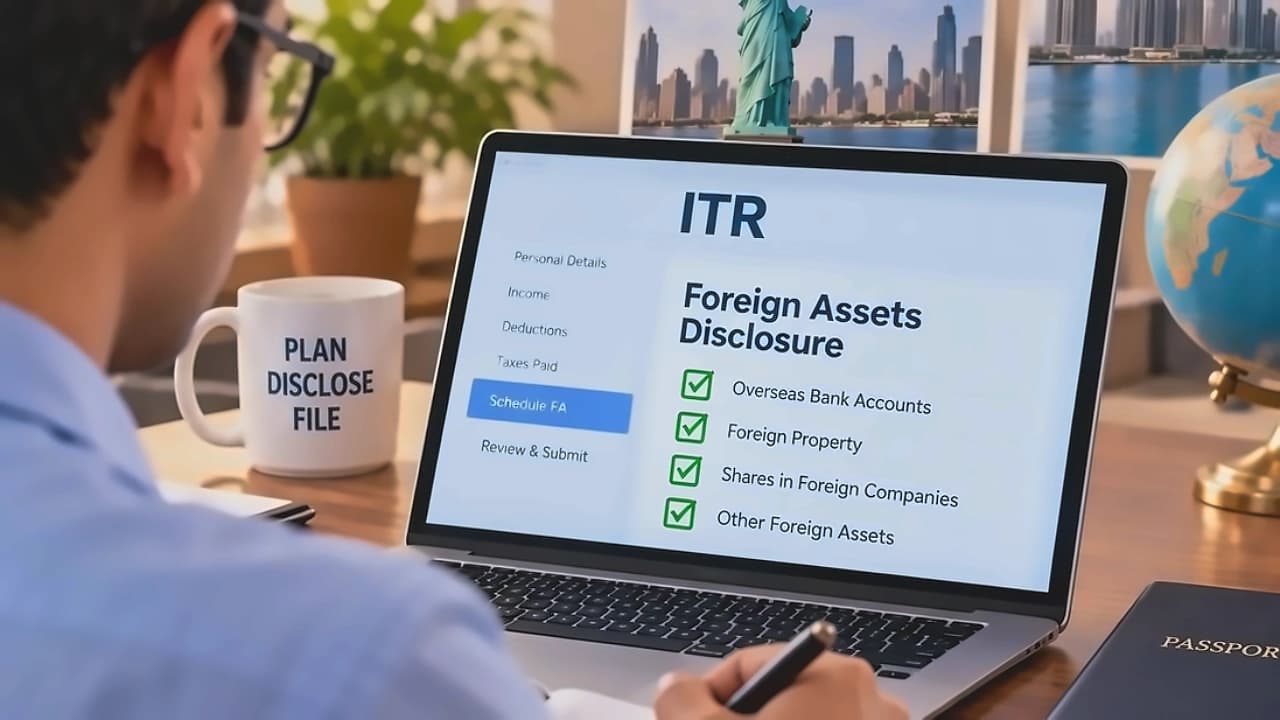
FAST-DS applies to taxpayers who failed to report foreign income or assets in ITR or did not file ITR despite requirements, covering any previous year(s) subject to prescribed thresholds and conditions. According to The Times of India, the scheme is not restricted to current Indian residents and applies to individuals who subsequently became Non-Residents or Resident and Not Ordinarily Resident where foreign income or assets relate to years when they qualified as Tax Residents in India. However, the scheme excludes serious cases involving criminal proceeds, is unavailable for years already assessed under the Black Money Act, and provides limited immunity extending only to tax, penalty, and prosecution under the BMA.
The scheme offers taxpayers certainty through a structured declaration process from declaration to clearance certificate. As reported by The Times of India, once taxpayers make a valid declaration, pay the prescribed amount, and meet scheme conditions, the disclosed foreign income or asset is regularised. The scheme provides a 20% valuation difference tolerance for assets other than foreign bank accounts, and amounts paid under the scheme are non-refundable. Taxpayers must undertake comprehensive reviews before filing, mapping each foreign asset to relevant assessment years and ensuring supporting documentation consistency across tax returns and account statements.