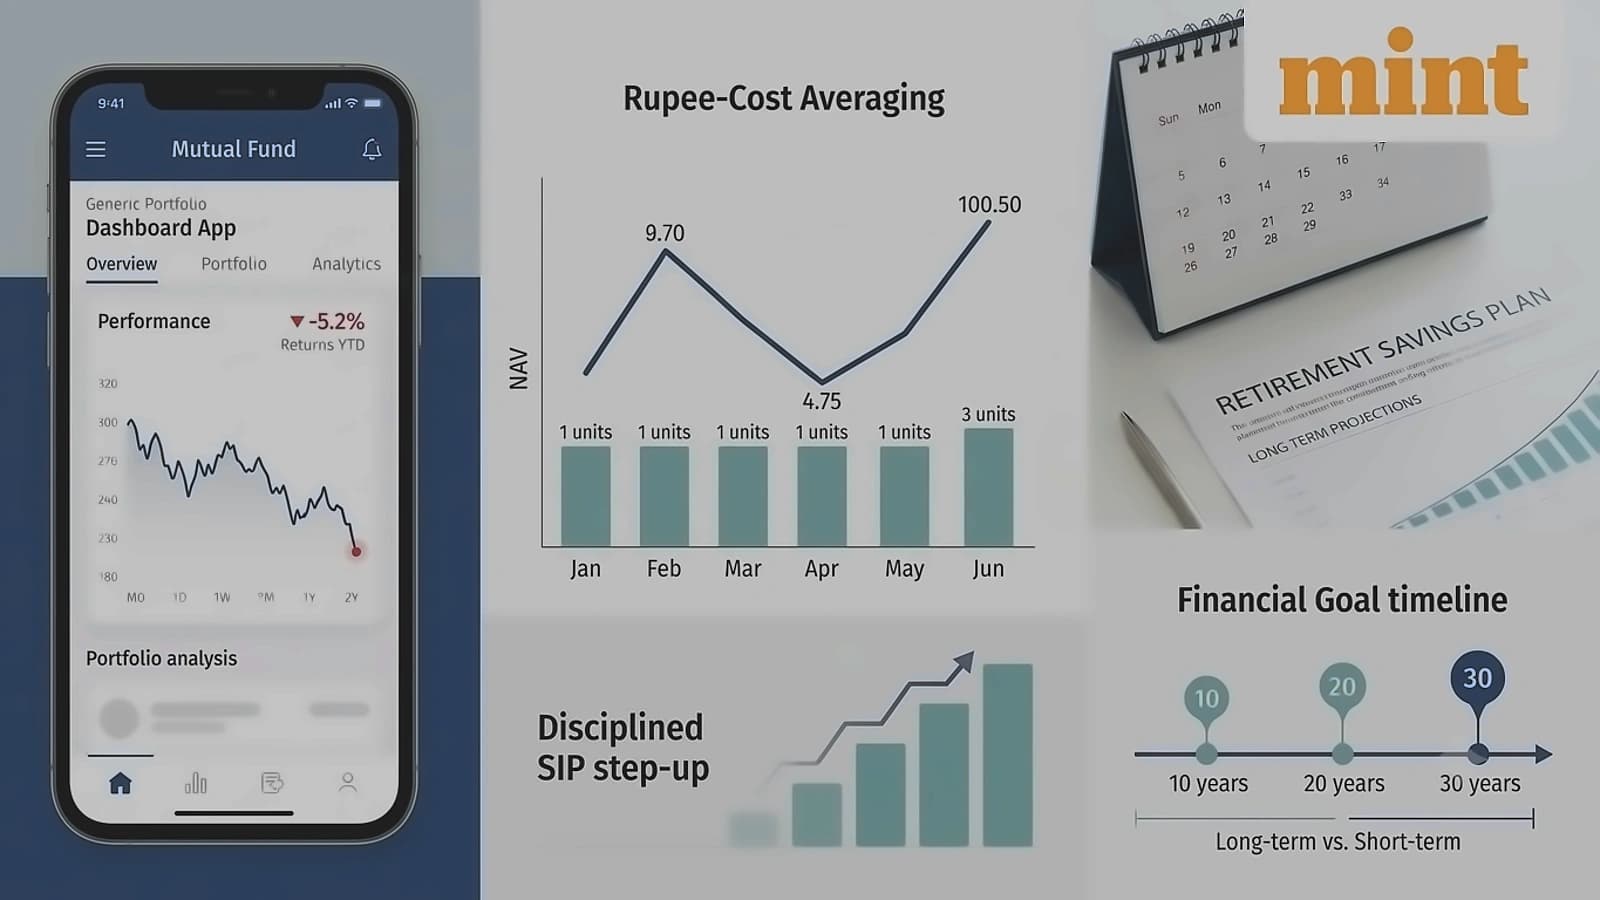
Systematic Investment Plans (SIPs) represent an effective approach to long-term wealth creation through compounding and rupee cost averaging. According to reports from the source, SIPs provide investors with capital market exposure without requiring market timing expertise. This systematic approach allows investors to benefit from market movements while maintaining a disciplined investment approach. For salaried investors, setting up a SIP is fairly straightforward with a fixed amount deducted from the bank account every month, either manually or through an auto-debit mandate. Many investors choose a SIP date close to their salary credit date, so the investment is made before other monthly expenses.
The primary advantages of SIP investments include compounding effects that amplify returns over time and rupee cost averaging which helps smooth out market volatility. As reported by the source, SIPs offer investors capital market exposure without the need to time the market. This systematic approach eliminates the stress and uncertainty associated with market timing decisions while providing consistent investment discipline.
The source emphasizes that SIP allocation should be based on take-home pay rather than a fixed percentage of income. This approach ensures that investment decisions align with actual financial capacity rather than theoretical income levels. The systematic nature of SIPs makes them particularly suitable for long-term wealth building, as they allow investors to maintain consistent investment discipline regardless of market conditions. Small contributions in SIPs can go a long way in creating wealth, making them accessible even for modest income levels.
Many investors follow the popular 50-30-20 rule for monthly budgeting, allocating 50% of pay towards needs, 30% towards wants, and the remaining 20% towards savings and investments. For someone with take-home pay of ₹40,000, this framework suggests investing approximately ₹8,000 for savings and investments. However, early career professionals with lower take-home pay can aim for 10-15% of pay for investment purposes, while maintaining emergency fund requirements. The exact allocation of the ₹8,000 towards assets depends on the investor's risk appetite and specific goals.
Investors should review how their SIP has performed over the years, including investment strategy, risk level, and alignment with their financial goals before deciding whether to continue or move their money elsewhere. As reported by the source, the five-year mark can be a good time to review whether the fund still deserves a place in your portfolio. However, completing five years is not a reason to stop or switch your SIP automatically. The decision should depend on the fund's historical performance, whether its investment strategy remains suitable, and whether it continues to match the investor's evolving financial goals.