When an SCSS account holder dies before maturity, the deposit and applicable interest up to the date of death are paid to the nominee or legal heirs, as applicable. According to reports from Mint, after the date of death, the deposit earns interest at the applicable Post Office Savings Account rate until the final settlement is completed. This ensures that the account continues earning returns even after the primary holder's demise. As of 19 September 2026, the SCSS offers an annual interest rate of 8.2%, paid quarterly, with the government maintaining these rates unchanged for the current quarter.
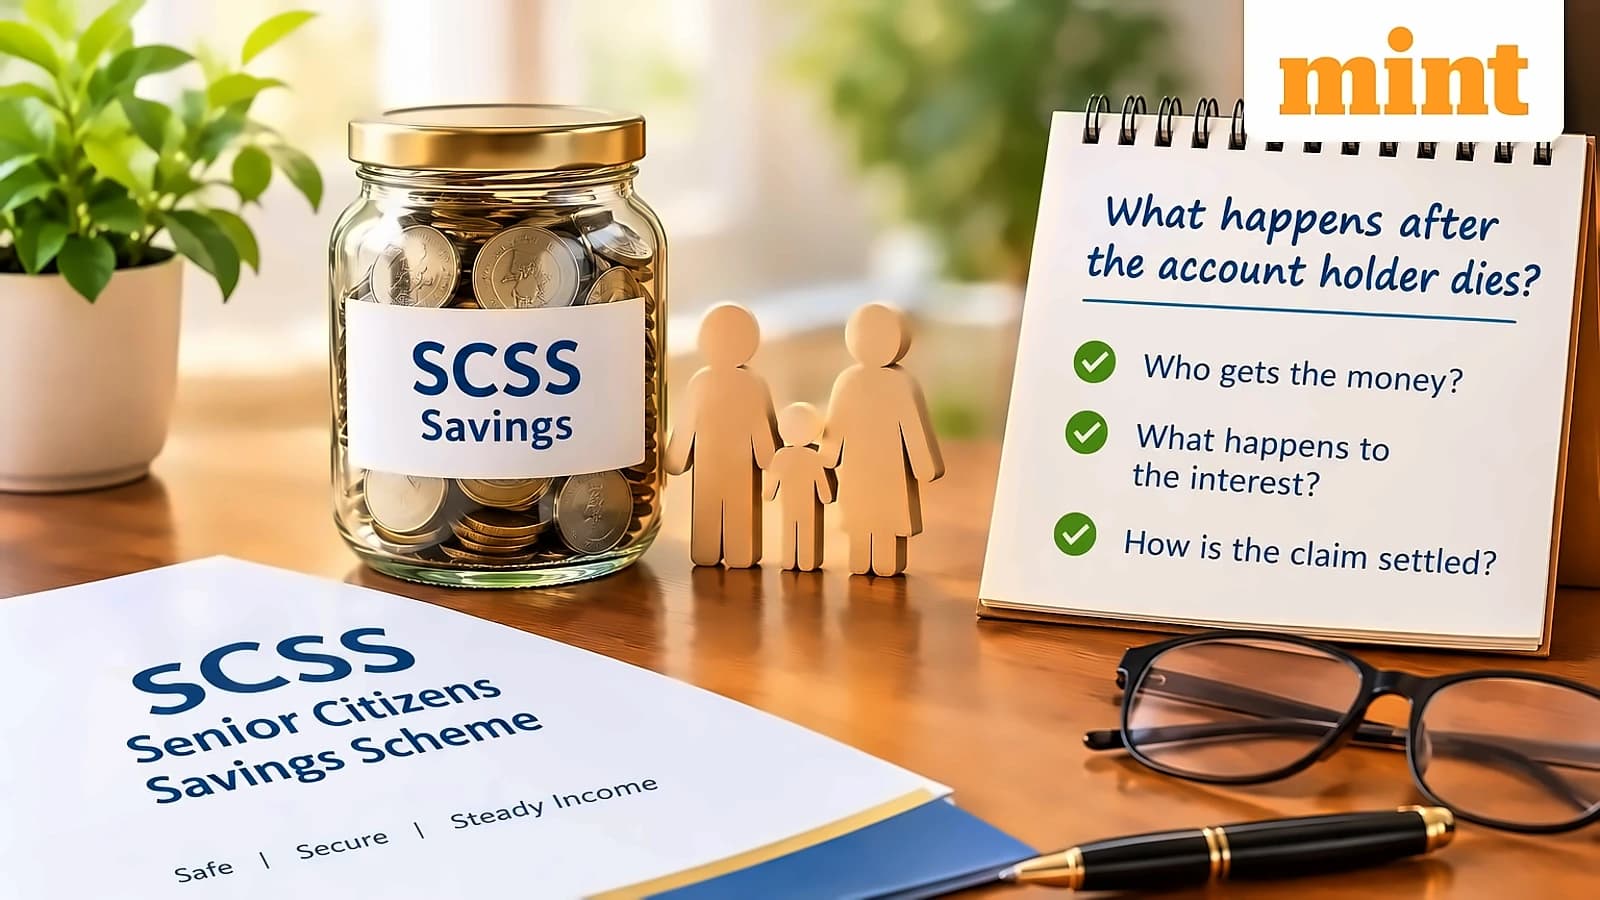
If the account is held jointly with the spouse, or if the spouse is the sole nominee, an eligible spouse can continue the SCSS account on the same terms, subject to the scheme's terms and conditions. As reported by Mint, this provision allows the surviving spouse to maintain the investment and continue earning the 8.2% annual interest rate that is currently offered. The account can be continued for the remaining tenure or until maturity, whichever is earlier. This makes it essential for primary account holders to keep account details up to date and ensure family members are aware of nomination and other critical information.
The Senior Citizens Savings Scheme offers a 5-year tenure with an annual interest rate of 8.2%, paid quarterly. According to Mint, the scheme allows maximum deposits of ₹30 lakh per individual with a minimum deposit of ₹1,000. Eligibility extends to individuals aged 60 years or above, while retired civilian employees aged 55-60 and retired defence personnel aged 50-60 can also participate. The scheme permits maturity extension by 3 years and allows premature closure subject to conditions. Interest earned is taxable under applicable income-tax provisions.
In cases where there is no valid nomination, the legal heirs must follow the prescribed claim-settlement process and may need additional legal documents depending on the circumstances. As reported by Mint, this highlights the significance of a clearly defined nomination, as it can simplify the claims process. The article emphasizes that retirement planning should include strategic succession planning, ensuring nomination details, basic account information, and spouse-related details remain up to date to ensure seamless transfer of savings. This makes it essential for the primary account holder to keep the details up to date and for family members to be aware of the account nomination and other critical details.