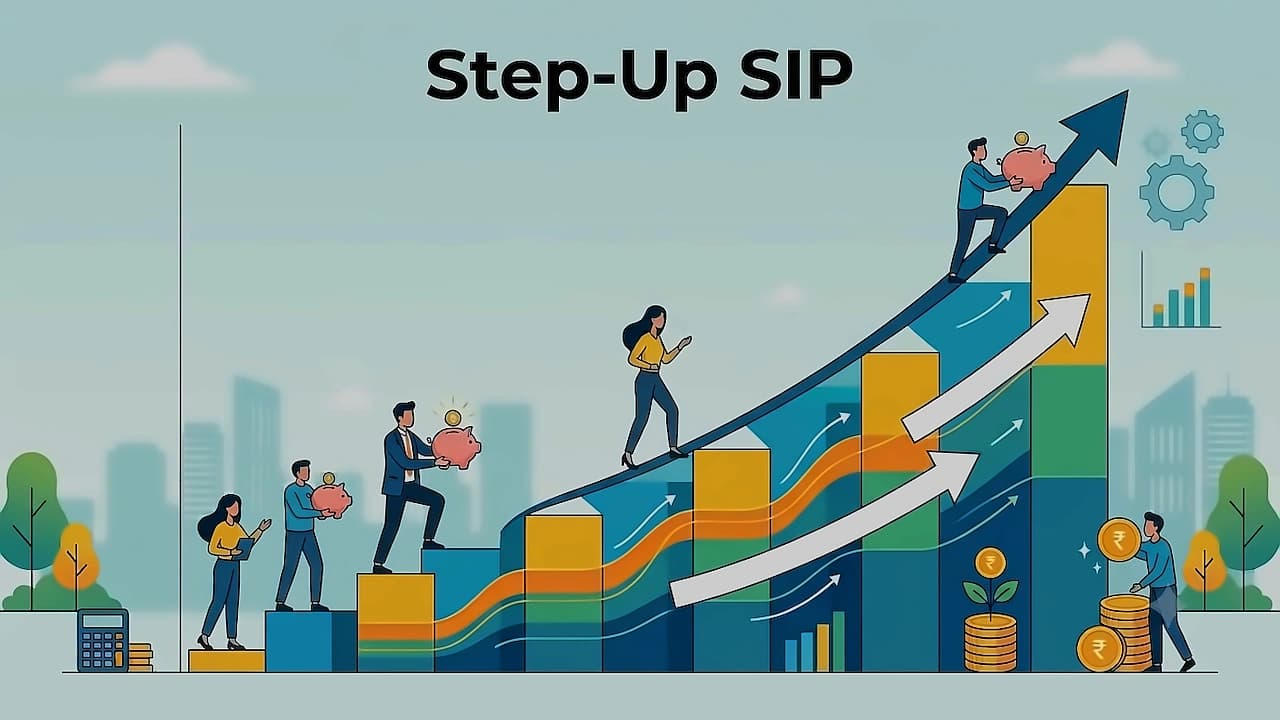
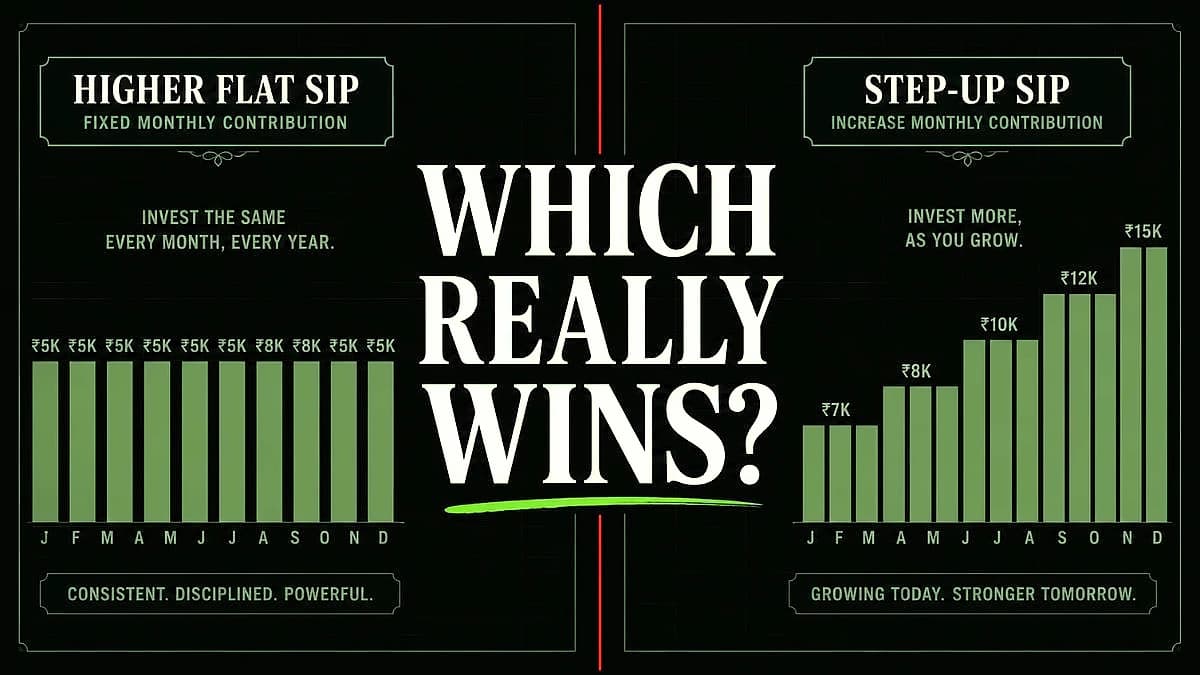
A Rs 10,000 monthly SIP with a 10% annual step-up can help investors build a corpus of around Rs 1.86 crore in 20 years, assuming a 12% annual return. According to reports from NDTV Profit, this strategy allows investors to increase their contribution by a fixed percentage every year, with the monthly investment rising from Rs 10,000 in the first year to Rs 11,000 in the second year and Rs 12,100 in the third year. The contribution continues rising by 10% each year, allowing more money to benefit from compounding over time. As noted in recent reports, many investors increase their SIP amount annually by 10% to accelerate wealth creation, making this strategy particularly effective for systematic long-term planning.
The step-up strategy demonstrates significant acceleration compared to a fixed SIP approach. As reported by NDTV Profit, a fixed Rs 10,000 monthly SIP without increases would require approximately 22 years and 4 months to reach the same Rs 1.86 crore target under the same 12% annual return assumption. The fixed SIP would result in a total investment of Rs 24 lakh with estimated returns of Rs 75.91 lakh, while the step-up SIP achieves the same corpus with Rs 68.73 lakh total investment and Rs 1.18 crore estimated gains. This comparison highlights how the step-up approach leverages compounding more effectively through increased contributions over time.
The step-up strategy provides substantial time savings for investors. According to the calculations from NDTV Profit, the step-up approach allows investors to reach the Rs 1.86 crore target more than four years earlier than a fixed SIP under these assumptions. This acceleration occurs because the increased contributions allow more money to benefit from compounding over time, with the strategy particularly beneficial for young professionals expecting regular salary increments and individuals building long-term financial goals. The approach makes investing more accessible by spreading investments over time, reducing the need to time market highs and lows while encouraging consistent saving habits.
Financial experts emphasize that inflation significantly impacts long-term investment planning. As explained by Zee Business, if inflation is assumed at 6%, a financial goal requiring Rs 1 crore today could require more than Rs 4 crore after 25 years. This inflation reality makes step-up strategies particularly relevant, as they allow investors to increase contributions in line with rising income and changing financial requirements. Recent analysis shows that keeping ₹3,118 under your mattress in 2006 would still be ₹3,118 today, but may buy only what ₹972 bought in 2006, with approximately 69% of the value eaten by inflation. The strategy may be particularly useful for young professionals expecting regular salary increments, investors building a retirement corpus, parents saving for their children's higher education and individuals working towards other long-term financial goals. However, investors must choose a step-up percentage that remains manageable when household expenses and financial commitments rise, ensuring the strategy remains sustainable throughout the investment period.