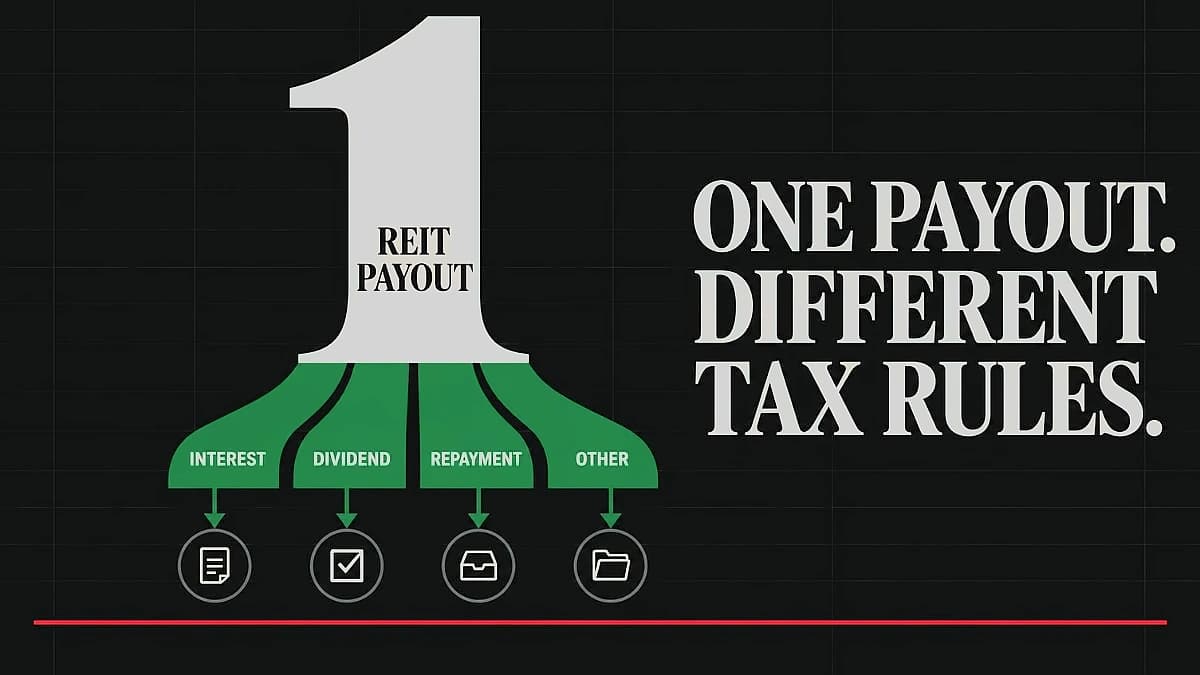
Real Estate Investment Trusts (REITs) in India operate under a 30% tax slab on distributed income, resulting in approximately ₹78,400 of every ₹1 lakh being retained by investors. According to reports from [source], this tax structure applies to the net distribution amount received by unit holders after accounting for all applicable deductions and charges.
The REIT distribution tax framework consists of four distinct components that determine the final tax liability. As reported by [source], these components include the base tax, tax on capital gains, tax on interest income, and tax on other income. Each component is calculated separately based on its specific tax rate and applicable deductions, with the total tax liability being the sum of all four components.
The Finance Act 2023 introduced significant modifications to the REIT taxation framework, affecting how these components are calculated and reported. According to reports from [source], these changes have resulted in revised tax calculations for REIT distributions and require updated reporting procedures in income tax returns. The Act has also clarified certain exemptions and streamlined tax deduction processes for REIT distributions.
REIT investors must report their distributions in their income tax returns under the appropriate sections, following the updated guidelines from the Finance Act 2023. As reported by [source], the tax calculation methodology has been standardized across all REIT distributions, ensuring uniform reporting across the sector. The new framework provides clearer guidance for investors and reduced compliance burden through streamlined procedures.