The SGB 2019-20 Series IV is set for redemption at ₹15,173 per unit, providing investors with a 295% profit based on their initial investment. According to recent reports, the redemption price is calculated based on the simple average of closing gold prices of 999 purity over September 16, September 15, and September 11, 2026, as published by the India Bullion and Jewellers Association Ltd. Originally issued at ₹3,840 per gram for online purchases, these bonds are now yielding a profit of ₹11,333, representing the substantial return for investors. An investment of ₹1 lakh in this SGB series at the time of its launch would be worth a little over ₹3.95 lakh today, excluding the interest earned on the principal amount. However, investors must be aware that missed submission windows result in a 6-month waiting period, making timely processing crucial for optimal returns.
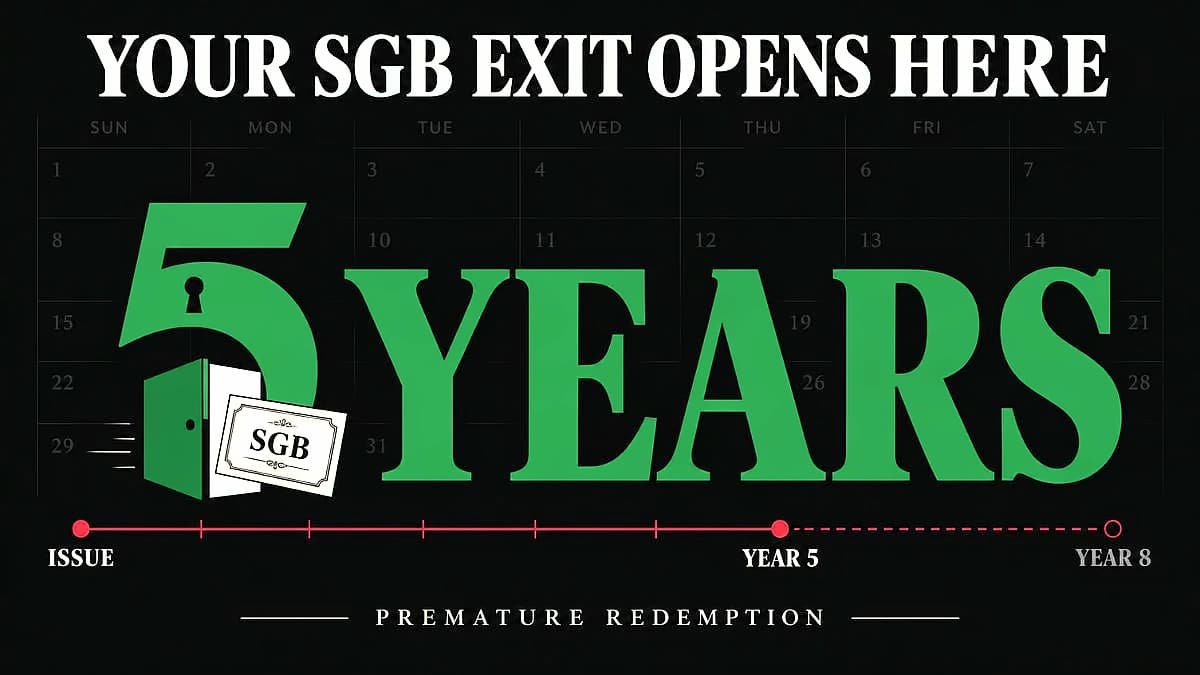
There are significant tax implications between RBI premature redemption and exchange sales of Savings Certificates. RBI premature redemption is tax-exempt from year five, while exchange sales are taxed under ordinary rules. This fundamental difference creates important considerations for investors planning early exits from their Savings Certificates. However, tax rules for SGBs have undergone changes from April 1, 2026, with capital gains tax exemption now only available for bonds held until maturity through primary issuance, not for premature redemptions. Wrong bank account or holding channel information can cause redemption credit failures, making proper documentation essential for successful processing.
As reported by [source], exchange sales of Savings Certificates are subject to taxation under ordinary rules, which means investors face tax liability on the gains from their early exit. This tax treatment applies when investors choose to sell their certificates through stock exchanges rather than through the RBI premature redemption process. For SGBs specifically, investors in the secondary market are subject to tax even when holding until maturity, with exemptions only applicable to those maintaining holdings through to maturity and having participated in primary issuance.
According to [source], RBI premature redemption offers tax-exempt status from year five, providing significant tax advantages for investors who choose this exit route. This exemption applies specifically to certificates that are redeemed through the RBI process rather than through exchange transactions. However, premature redemptions invoke tax liabilities, irrespective of when and how bonds were acquired, making the timing of redemption crucial for tax optimization. The premature redemption of the SGB series is permitted after the fifth year from the date of the issue of such gold bonds on the date when interest is payable, as per the RBI statement. Missed submission windows result in a 6-month waiting period, making timely processing essential for investors seeking immediate liquidity.
Investors must carefully consider the timing and method of their Savings Certificate exit to optimize their tax position. The choice between RBI premature redemption and exchange sales depends on individual tax planning considerations and the specific circumstances of each investor's portfolio. For SGBs specifically, offline investors purchased these bonds at a slightly higher price due to the absence of a ₹50 discount available for digital transactions, affecting their overall returns and tax implications. Interest is credited semi-annually to the bank account of a gold bond investor, with the last interest payable on the bond's maturity along with the principal. Proper documentation and account verification are essential to avoid processing delays or credit failures during the redemption process.