On 26 August 2026, the Financial Services Council (FSC) issued FSC Standard No. 30, Private Markets Best Practice Principles, alongside FSC Guidance Note No. 57. The Standard takes effect on 1 July 2027 and is mandatory for FSC Full Members that manage, operate, or hold primary responsibility for investment management, governance, or risk management within private markets. This represents a direct response to ASIC's call in REP 823 for strengthened industry standards and lands amid an escalating enforcement programme of DDO stop orders, active surveillances and investigations into the private credit sector. The Standard establishes obligations across seven key pillars and is publicly available, expected to serve as a reference point for ASIC, ratings agencies, institutional investors, and superannuation fund trustees when assessing fund manager practices and making investment decisions.
According to recent reports, private credit funds typically offer 12% yields to investors. However, this headline figure requires careful examination of the actual returns investors receive after accounting for various costs and market conditions. The actual yield after fees and losses is approximately 8.7%, representing a significant reduction from the advertised rate. This discrepancy highlights the importance of understanding the true cost structure before investing in private credit funds. The new FSC Standards address fee alignment considerations, requiring managers to assess fee disclosure practices end-to-end, including borrower-paid fees, net interest margin arrangements and related-party economic benefits. The Guidance Note provides model definitions for key metrics like default, arrears, impairment, watchlist and LVR, addressing ASIC's concern about inconsistent terminology that was reducing comparability across funds.
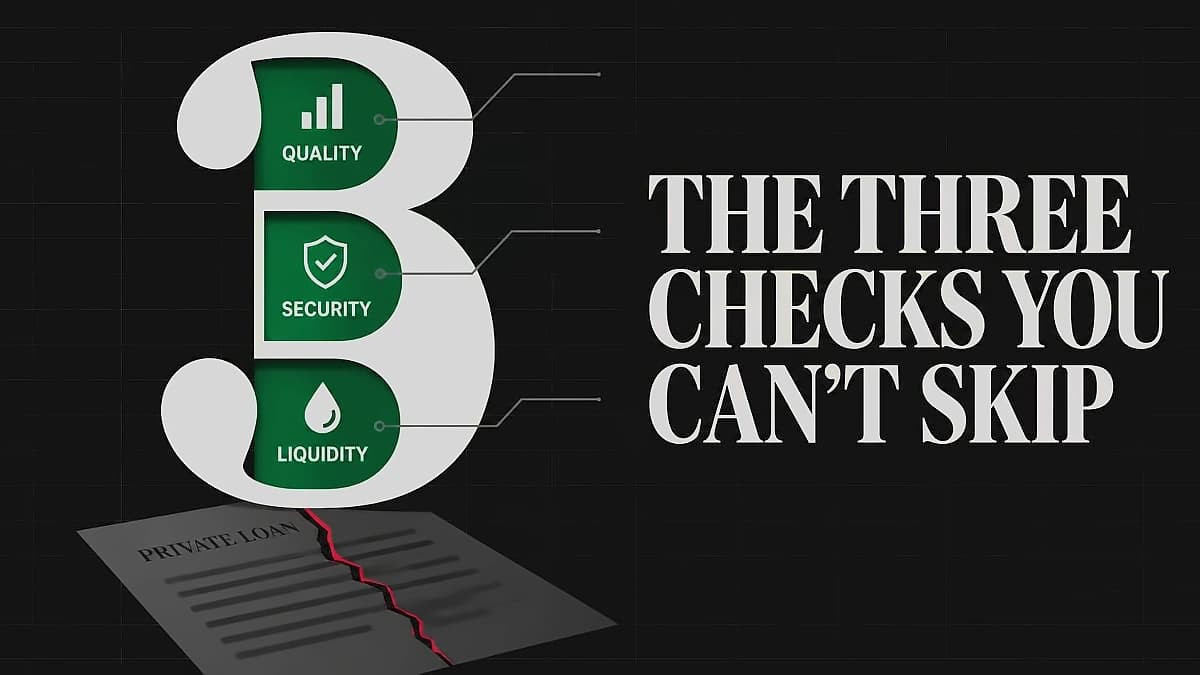
As reported, portfolio quality emerges as a critical factor when evaluating private credit funds. The quality of the underlying investments directly impacts the fund's ability to deliver consistent returns and manage risk exposure. The new FSC Standards require managers to conduct a gap analysis against each of the Standard's seven obligation pillars, using the practical examples in the Guidance Note as implementation benchmark. Managers must align their credit risk terminology with the Guidance Note's model definitions - an area ASIC has already flagged as inconsistent across the sector. The Guidance Note offers good-practice guidance on valuation frequency (at least quarterly in most circumstances) and defining triggers for valuation reassessment outside normal cycles. Investors should carefully examine the composition of the fund's portfolio, including the types of borrowers, loan structures, and risk profiles of the investments to determine whether the fund's strategy aligns with their risk tolerance and return expectations.
According to the analysis, fee alignment represents another essential evaluation criterion for private credit funds. The new FSC Standards require managers to review valuation governance arrangements, particularly the independence of valuation approvals from origination and asset management. The Guidance Note provides model definitions for key metrics that directly address ASIC's concerns about inconsistent terminology. Managers must assess fee disclosure practices end-to-end, including borrower-paid fees, net interest margin arrangements and related-party economic benefits. The fee structure should be transparent and competitive, with costs clearly outlined in the fund documents. Investors should compare the total cost of ownership, including management fees, performance fees, and other charges, against the expected returns. Fee alignment becomes particularly important when considering the significant reduction in actual yields after accounting for various costs.
As reported, liquidity terms and exit strategy constitute the third key criterion for evaluating private credit funds. These terms determine how easily investors can access their capital and when they can expect to receive returns. The new FSC Standards require managers to provide transparent reporting of manager remuneration and apply independent oversight to related-party lending and cross-fund transactions. The Guidance Note offers guidance on applying independent oversight to related-party lending and cross-fund transactions. The liquidity profile affects the fund's ability to meet redemption requests and provides clarity on the investment horizon. Understanding the liquidity terms helps investors align their investment timeline with their financial goals and risk management strategy. The Standard is underpinned by an annual attestation requirement under FSC Standard No.1, with the FSC retaining the ability to conduct enquiries into how the Standard is being applied in practice.