The Public Provident Fund (PPF) has emerged as a top choice for long-term financial planning, launched by the Centre in 1986 as a reliable, low-risk government-backed savings scheme with consistent returns. According to reports from Mint, PPF accounts can be opened at any post office or bank branch across India with a 15-year lock-in period, after which investors can extend their accounts in five-year blocks indefinitely. The scheme offers guaranteed returns and can be used for various financial goals including wedding funding, children's education abroad, house purchases, retirement planning, or wealth building. Investors can easily open a PPF account at their nearest bank or post office branch by submitting an application form, along with required KYC documents, with no minimum age requirement. Parents can choose to open an account for their child, which must be converted into a major account once the holder turns 18.
Starting PPF investments early significantly reduces the required monthly investment to achieve crorepati status. As reported by Mint, beginning investments when a child is a toddler with a 50-year investment horizon requires only ₹1,900 per month to build a corpus exceeding ₹1 crore. However, delaying investment by just five years can substantially increase the required monthly contribution. For example, starting at age 10 instead of 5 would require ₹2,900 per month for a total corpus of over ₹1.09 crore, while starting at age 20 necessitates ₹6,000 per month for the same target. Financial planning experts note that investing early allows you to slowly and steadily take advantage of the power of compounding to build a sizeable corpus, even with relatively smaller contributions, while a late start may force you to stretch beyond your means with monthly contributions.
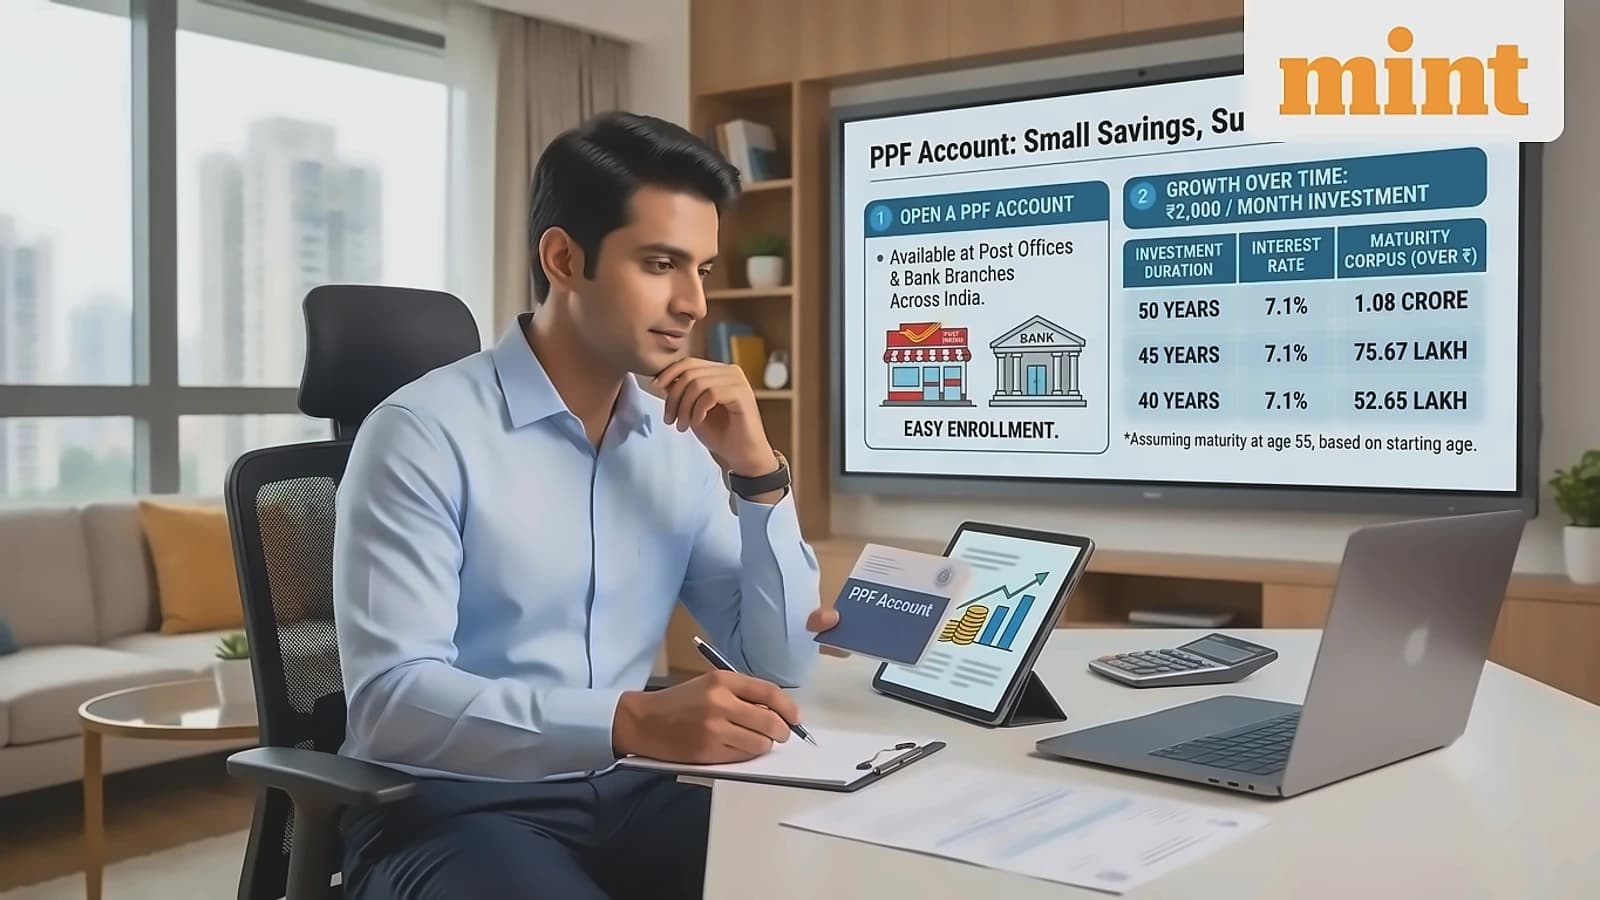
The analysis reveals specific investment requirements across different starting ages and contribution amounts. According to Mint calculations, starting at age 5 with ₹2,000 monthly for 50 years at 7.1% interest rate generates a corpus of over ₹1.08 crore by age 55. Starting at age 10 requires ₹2,900 monthly for 45 years to achieve the same ₹1.09 crore target. The most challenging scenario involves starting at age 40, where ₹34,000 monthly for 15 years is needed to build a ₹1.10 crore corpus. For structured annual contributions, ₹1.5 lakh annually as lumpsum investments totals to ₹27 lakh and earns interest of more than ₹28.14 lakh, generating a total maturity corpus of over ₹55.14 lakh at age 18. The same amount can be invested as ₹12,500 monthly for 18 years, achieving the same maturity amount. ₹1 lakh annually as lumpsum generates ₹18 lakh with interest of more than ₹18.76 lakh, totaling over ₹36.76 lakh at age 18, while ₹50,000 annually as lumpsum creates ₹9 lakh with interest of more than ₹9.38 lakh, totaling over ₹18.38 lakh at age 18.
The power of compounding becomes evident in these calculations, with early investment providing the greatest benefit. As reported by Mint, if adult account holders continue PPF contributions for another 42 years after age 18, they can accumulate substantial wealth. The ₹1.5 lakh annual contribution can grow to ₹75 lakh with interest of ₹6 crore, creating a combined 50-year maturity corpus of over ₹6.75 crore at age 60. The ₹1 lakh annual contribution can accumulate ₹50 lakh with interest of ₹4 crore, generating a combined 50-year maturity corpus of over ₹4.50 crore at age 60. The ₹50,000 annual contribution can grow to ₹25 lakh with interest of ₹2 crore, creating a combined 50-year maturity corpus of over ₹2.25 crore at age 60. The analysis emphasizes that investing larger amounts monthly may not be feasible or tax beneficial for most salaried individuals, making early and consistent investment the key strategy for long-term wealth building through PPF.