Paying the final equated monthly instalment (EMI) on a personal loan does not guarantee an immediate improvement in the borrower's CIBIL score. According to reports from Mint, the lender must first report the loan closure to the credit bureau, after which the updated information is processed and reflected in the credit report. Under Reserve Bank of India (RBI) rules, credit institutions are required to update credit information every fortnight from January 1, 2025. However, the time taken for the revised information to appear in an individual's credit report can vary significantly.
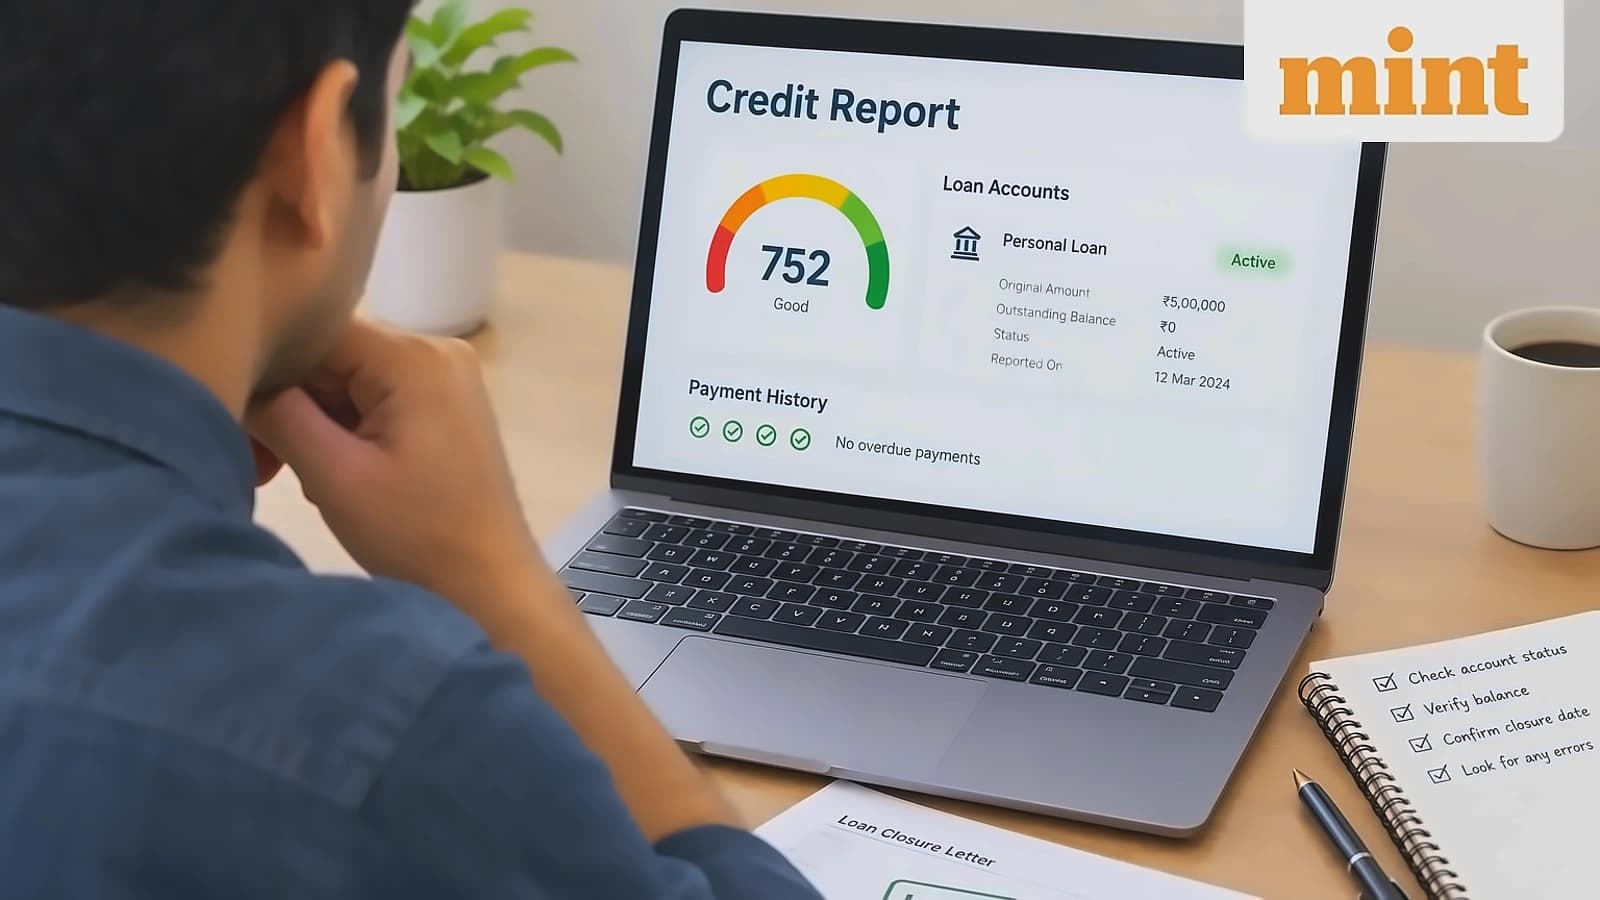
Credit bureau updates are not necessarily reflected in the consumer's report immediately after the payment. As reported by Mint, recent payment updates may take around 15 to 30 days to appear, depending on the reporting and processing cycle. For instance, a borrower who repays a personal loan on October 5 may still see the earlier account status when checking the credit report a few days later. Borrowers should check whether the lender has reported the account as closed and updated the outstanding balance to zero after making the final payment.
Closing a loan is only one of several factors that influence a credit score. According to TransUnion CIBIL, payment history, credit utilisation, the age of credit accounts and recent credit enquiries also affect an individual's credit profile. A personal loan is an unsecured credit facility, and repaying it reduces the borrower's outstanding debt, but the resulting effect on the credit score depends on the overall credit profile. As reported by Mint, one borrower may experience a modest improvement, another may see no immediate movement, while a third may notice a change after updated information is processed. Recent analysis suggests that credit mix - the variety of account types on your credit report including credit cards, personal loans, mortgages, and auto loans - plays a significant role in scoring models, with scoring models giving credit for successfully managing multiple types of debt simultaneously.
If the score remains unchanged after loan closure, borrowers should first review their credit reports rather than apply for fresh credit. According to Mint, they should check the account status, outstanding balance, payment history and date of the latest update. If the loan continues to show an incorrect balance or status after a reasonable reporting period, contact the lender and request a correction. A dispute can also be raised with CIBIL if the information reported is inaccurate, though the bureau cannot independently alter account information without the required confirmation from the concerned credit institution. Recent research indicates that maintaining good credit habits elsewhere, such as continuing on-time payments on other accounts, can help scores recover quickly while the debt remains permanently eliminated.