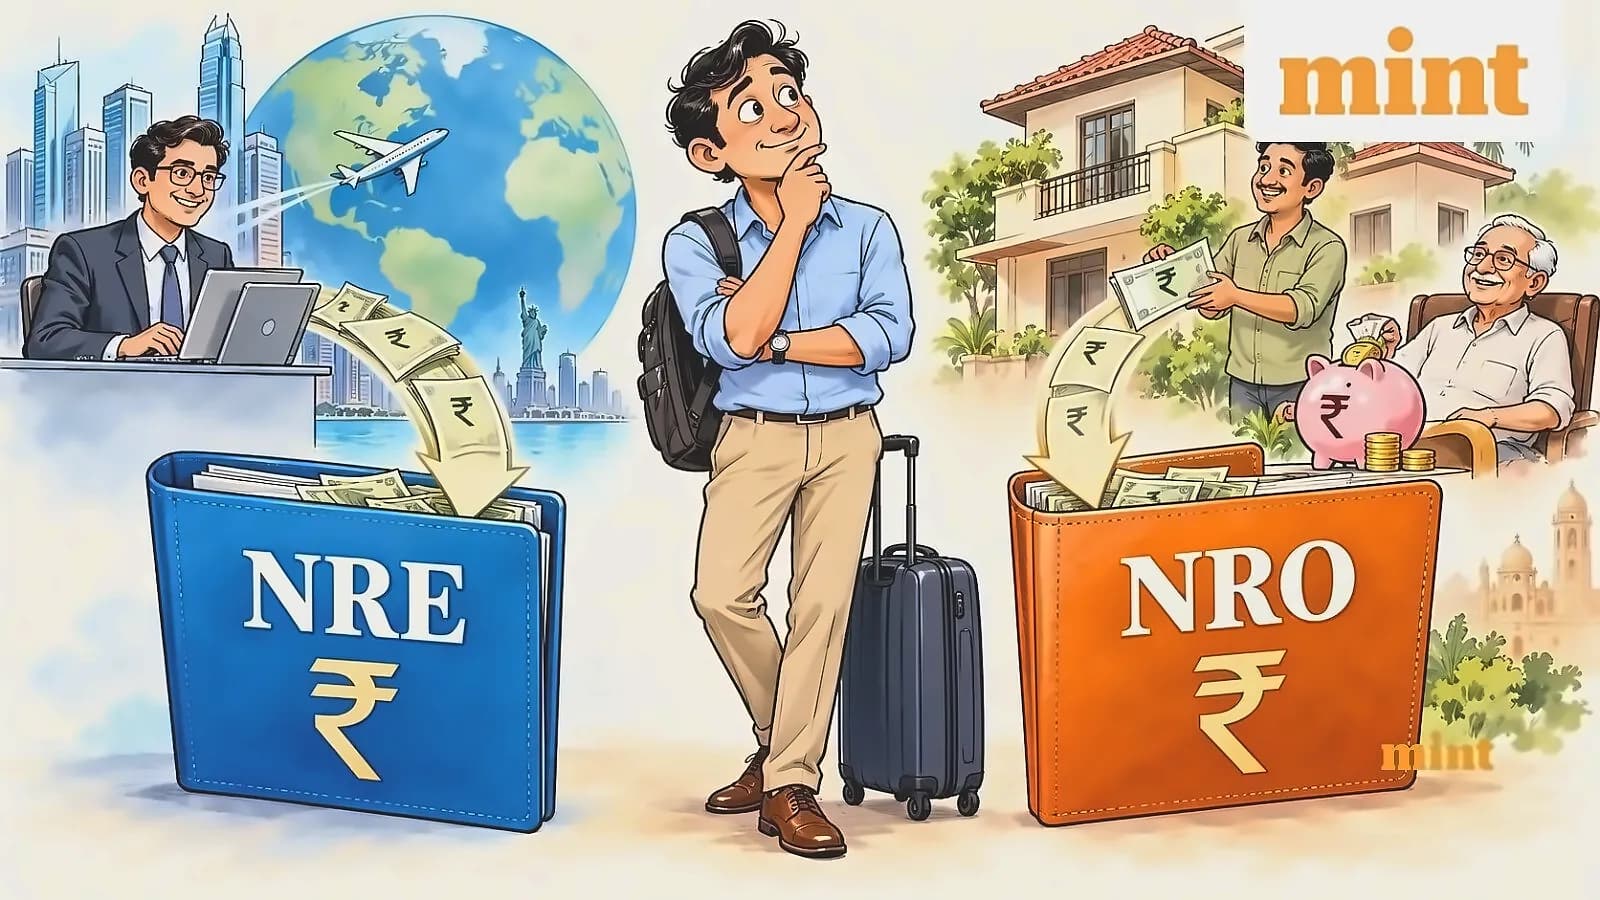
Non-residents in India must update their banking arrangements by switching old savings accounts to avoid tax issues and compliance problems. According to reports from Mint, once you become a non-resident under India's foreign exchange rules, you must inform your bank to change your existing resident savings account to an NRO (Non-Resident Ordinary) account. Gaurav Matta, co-founder of NRiSimplify, explains that many NRIs overlook this review after moving abroad, advising that the basic distinction is straightforward: Non-Resident External Accounts are meant for overseas earnings or inward remittances from abroad, while NRO accounts are meant for income arising in India, such as rent, pension or property proceeds.
As reported by Mint, NRE accounts mainly help bring overseas earnings into India, while NRO accounts commonly handle Indian income, including rent, pensions and property sale proceeds. However, NRO accounts can also receive money from abroad, as eligible Indian income can be remitted to NRE after bank verification and applicable taxes are addressed. Matta advises that NRIs should map every source of income to the appropriate account and review their arrangements whenever their residency or income profile changes.
According to Mint reports, NRE interest is exempt from Indian income tax while meeting eligibility conditions, while NRO interest is taxable, with banks deducting tax before paying at a rate of 30% plus applicable surcharge and cess, working out to 31.2%. Latest RBI guidelines reveal that interest earned/accrued on NRE & FCNR Term Deposits is tax free in India under the relevant provisions of Income Tax Act, with no tax at source deductible. For NRO deposits, depositors can claim benefits under Double Tax Avoidance Agreement (DTAA) by submitting prescribed documents at the beginning of every financial year, though banks have statutory obligation to deduct tax at source. If PAN is submitted with declaration, TDS is deducted at applicable rates for the country of residence. Without PAN or declaration, TDS is deducted at 30%, while if PAN and declaration are not submitted, TDS is deducted at 30%. All interest payments will be rounded off to the nearest rupee.
As detailed in the Mint article, NRE deposits and interest can be freely transferred abroad, while NRO balances generally qualify for transfers up to USD 1 million each financial year with conditions and applicable taxes. Current income such as rent or pension can be remitted separately after applicable taxes are withheld, though the million-dollar limit does not cover every NRO transfer. According to the latest RBI guidelines, for transfers exceeding USD 1 million, prior approval from RBI is required, with funds being transferred to NRE accounts within this USD 1 million facility. Interest rates on NRE/NRO deposits shall not be higher than those offered by the bank on comparable domestic rupee term deposits. Interest on FCNR (B) deposits shall be paid at rates calculated in accordance with RBI basis for various maturities, with rates not subject to negotiation between depositors and banks.
According to Mint reports, NRE accounts can include a resident relative under the permitted former-or-survivor arrangement, while NRO accounts can also have a resident joint holder. The article recommends reviewing incoming payments, interest deductions, nominees, and overseas transfer needs with your bank, noting that keeping both accounts may help when you earn money in India and abroad. Matta emphasizes that continuing to use a resident savings account after becoming an NRI can create compliance issues.