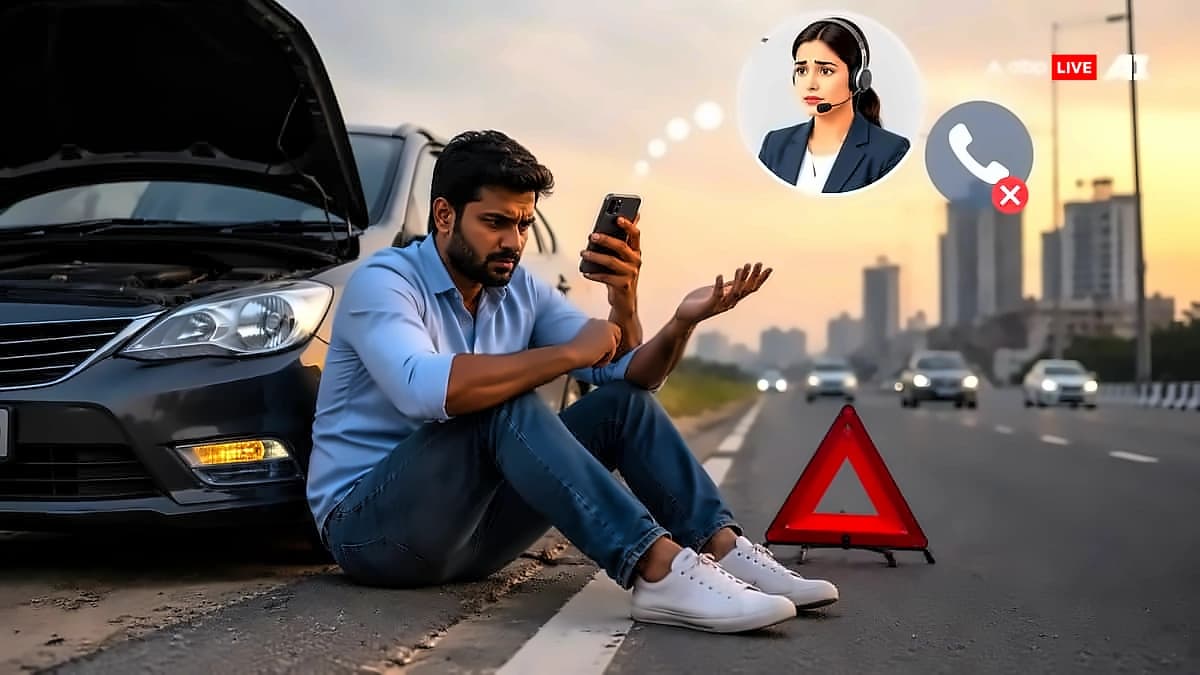
According to reports from The Times of India, motor insurers in India operate with a stark contrast between aggressive sales tactics and poor post-sales service. Calls go unanswered, emails disappear, and service requests are marked resolved without actual problem resolution. The pattern is consistent where policyholders raise queries or initiate claims, service tickets are opened with assurances that the 'concerned team is working on it', but tickets close within 24 hours without actual resolution. Company helplines are frequently unreachable, websites trap users in CAPTCHA loops that go nowhere, and there is rarely a direct line to speak to anyone with authority to resolve issues.
As reported by The Times of India, IRDAI prescribes clear turnaround timelines for motor insurance claims, measured in hours, not days or weeks. However, many claims drag on far longer, with surveyors taking days to submit reports and insurers taking additional time to respond once they do. The surveyor visit, which should be swift and professional assessment, often becomes a source of further delay. Garages wait on surveyors, surveyors wait on insurers, and policyholders are left without their vehicles and without clear timelines. Communication during this period is typically poor, and the burden of follow-up falls entirely on the customer.
According to the report, add-ons such as tyre protection, engine cover and zero depreciation are aggressively marketed at the time of sale. When claims are actually filed under these covers, a different set of rules quietly comes into play, including partial approvals, depreciation deductions, and lengthy investigations into matters that could be resolved with a single phone call. Policyholders who have paid for comprehensive cover frequently discover that the effective payout bears little resemblance to the coverage they believed they had purchased.
As reported by The Times of India, the regulatory framework offers recourse to policyholders, but using it requires proactive and informed action. The first and most important step is to communicate in writing at every stage, with email and WhatsApp messages creating a documented trail that verbal conversations do not. When following up on delayed claims, citing IRDAI's prescribed turnaround timelines directly puts the insurer on notice of their regulatory obligations. If the insurer does not respond within the stipulated period, the matter should be escalated to the insurer's Grievance Redressal Officer. If the grievance officer route yields no resolution, IRDAI's Integrated Grievances Management Portal (IGMS) allows policyholders to file formal complaints with the regulator.
According to the report, the frustration is widespread and growing, and it cuts across segments, vehicle types and insurer categories. The sales machinery operates at full throttle with aggressive marketing, but post-sales service runs on silence. Before buying or renewing any policy, the add-ons, exclusions and depreciation clauses deserve careful reading, as the fine print is rarely where the sales pitch focuses, but it is where most disputes begin. Recent legal precedent from the United States demonstrates the importance of prompt action, as failure to serve court documents within statutory deadlines can result in dismissal of claims, even when filed within policy limitations periods.