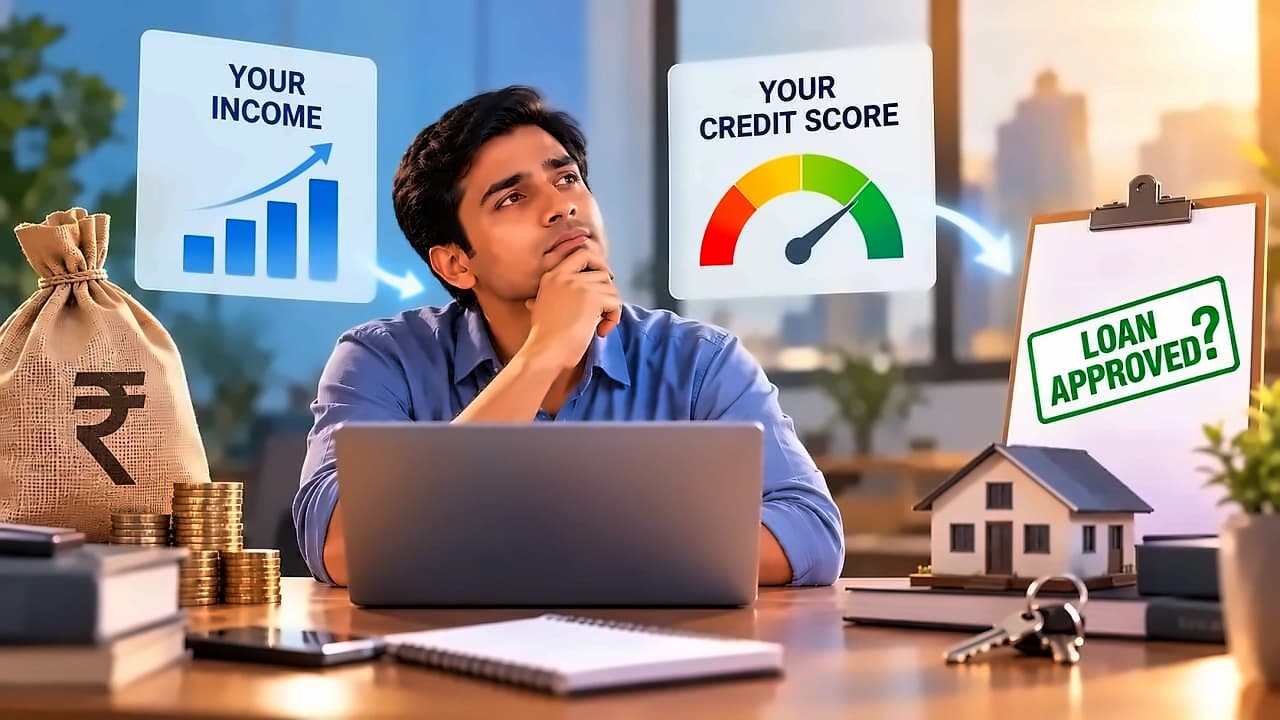
Lenders conduct comprehensive risk assessment while approving loan applications, focusing on ability to pay and intention to pay through multiple factors. According to reports from The Times of India, the assessment includes monthly income, credit history, current obligations, income stability, employer profile, and existing debt. The lender's analysis determines whether the borrower has demonstrated responsible credit behavior, can repay the loan on time, and if the risk aligns with the lender's credit policy. Past credit behavior is summarized in credit history, while repayment capacity is assessed through income and existing debt profile. All lenders have their own eligibility criteria, which may be based on their risk appetite, product policies, existing relationship with the borrower, internal credit models, and income assessment methodologies.
While gross income remains important, lenders consider income stability, continuity, employer profile, employment type, and industry type during loan application analysis. As reported by The Times of India, salaried borrowers are preferred due to their predictable and documentable income patterns, with those employed in government or large multinational companies having higher approval chances. However, even high-income applicants may face rejection if their employer is new, like a startup, or works in sectors with future risks. Self-employed professionals and freelancers face additional challenges due to variable income patterns and inconsistent earning profiles. Self-employed professionals such as doctors, lawyers, CAs, financial consultants, architects, etc. may also have variable income patterns even after an established professional profile, leading to challenges during loan approval. Freelancers or those working in unorganized sectors may have less conventional earning profiles, and the income patterns can also be inconsistent, making documentation and assessment very important.
Existing EMI obligations and financial commitments play a crucial role in loan approval, with lenders preferring responsible borrowing behavior. According to the report, Fixed Obligation to Income Ratio (FOIR) is a significant factor, where fixed obligations including new loan EMIs should be less than 55% of net monthly income. Two applicants with identical credit scores earning ₹1 lakh monthly may receive different evaluations based on existing EMIs of ₹15,000 vs ₹55,000. The first applicant can service a loan of ₹40,000 monthly comfortably, while the second applicant's stretched liabilities limit their borrowing capacity. Instead of only evaluating whether the applicant earns enough, lenders want to know whether the applicant can comfortably service the proposed loan. A higher income can improve eligibility for a larger loan amount, but the loan amount requested, age, and the proposed loan tenure may also impact loan approval or the sanctioned loan amount.
Credit score indicates disciplined credit behavior and reduces default risk, but lenders still evaluate applicants based on income, existing obligations, loan amount, and other eligibility parameters. As reported by The Times of India, unpaid debt and defaults from the past are detrimental to credit profiles and almost guarantee rejection. A borrower with a poor score is unlikely to get a loan, despite meeting other eligibility conditions. The reason behind the low score matters significantly, as unpaid debt and defaults from the past are detrimental to your credit profile and almost guarantee a rejection. Self-employed borrowers are assessed through financial statements, income consistency, business vintage, and banking behavior, with established businesses and strong business models increasing approval chances despite variable income patterns.
Borrowers should evaluate their complete financial profile rather than optimizing single parameters for larger loans. According to the report, applicants should maintain stable and well-documented income, manage current debt responsibly, afford new EMI over long-term, ensure healthy and accurate credit reports, and compare offers to find the most suitable and sustainable options. A financial marketplace can be very helpful in situations where the applicant can compare available loan offers from multiple lenders and identify those where his chances of loan approval are the highest, depending on the lenders' eligibility criteria and his financial situation and creditworthiness. Borrowers should not aim to optimize one parameter to secure a larger loan. Instead, they should evaluate their complete financial profile and try to match it with the most suitable offer that is affordable and sustainable in the long run. Applicants can create a 5-point 'Loan Approval Readiness' checklist that answers five simple questions: is my income stable and well documented, what is my current debt, can I afford the new EMI over the long-term, is my credit report healthy and accurate, and have I compared offers to find the best one.