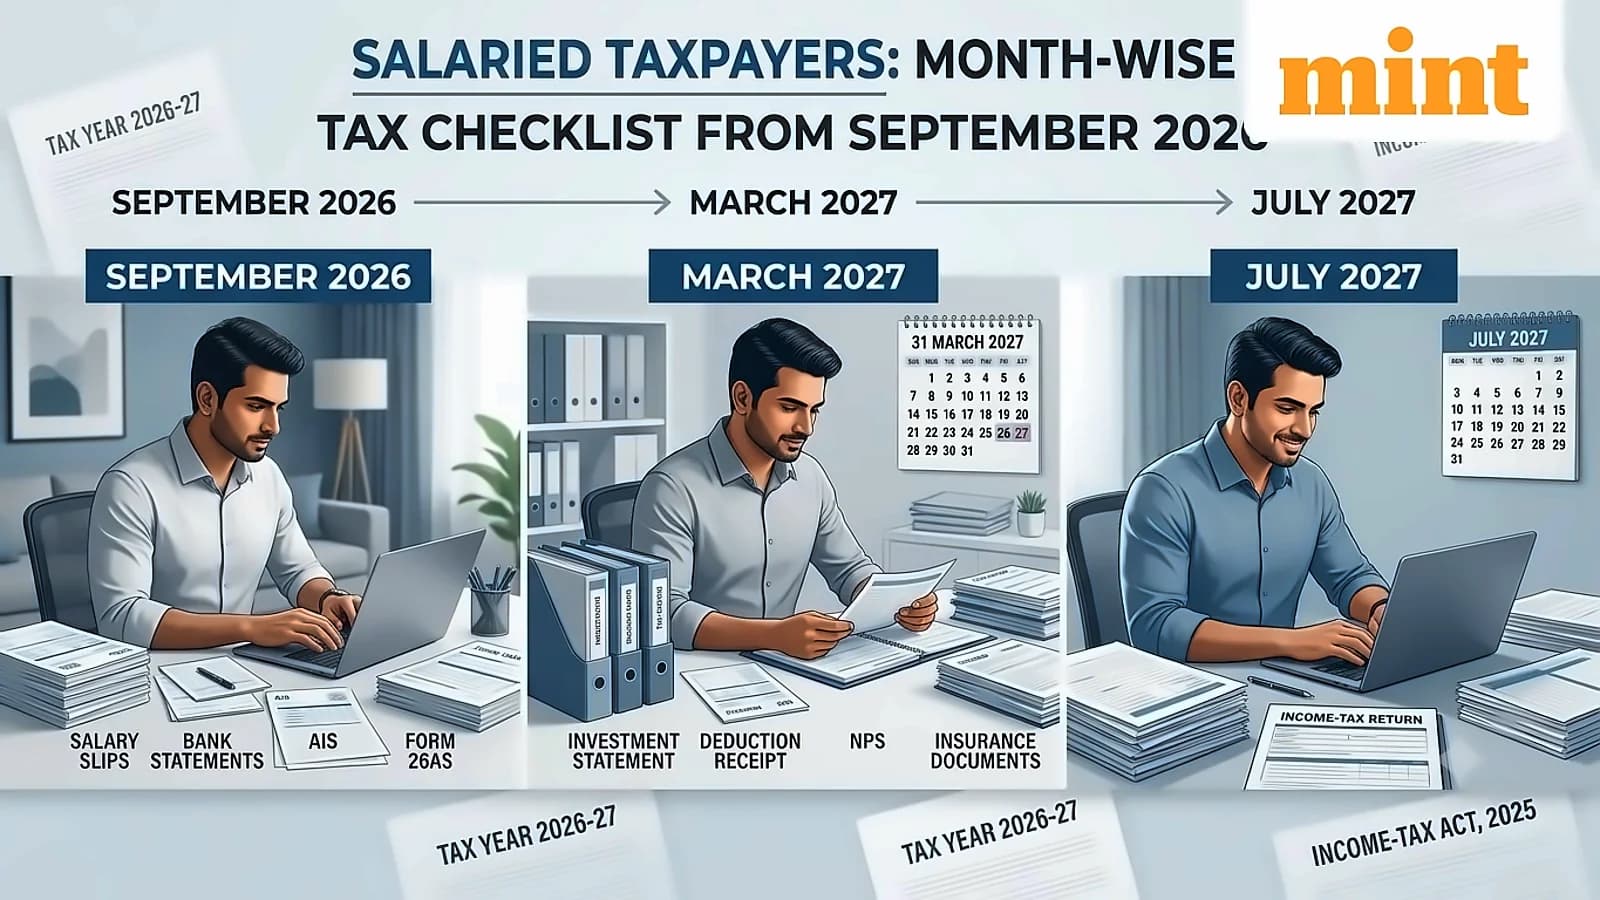
Salaried taxpayers must file their tax returns for Tax Year 2026-27 by July 2027, covering the period from 1 April 2026 to 31 March 2027. According to reports from Mint, the Income Tax Act, 2025 is now effective from Tax Year 2026-27, replacing the Assessment Year terminology with a single 'Tax Year' concept. While the filing deadline remains 31 July 2027, maintaining tax documents and records from September 2026 onwards can significantly streamline the filing process.
Tax expert Isha Sekhri from Isha Sekhri & Associates LLP has outlined a comprehensive month-wise checklist for salaried taxpayers. As reported by Mint, the strategy begins in September 2026 with checking interest and dividend income and advance tax requirements. October 2026 involves reconciling bank, broker, and mutual fund statements while raising AIS feedback on mismatches. November 2026 focuses on preparing receipts for old regime deductions, while December 2026 requires reviewing total income and paying the third advance-tax instalment by 15 December. January 2027 involves confirming final tax proofs required by employers, followed by finalising tax computations and comparing both regimes in February 2027. March 2027 concludes with collating records and completing eligible investments by 31 March, along with paying the fourth advance-tax instalment by 15 March.
According to Mint reports, taxpayers should maintain comprehensive documentation in a digital folder including salary details such as monthly slips and prior-employer information, investment records covering bank statements, mutual fund CAS, demat and broker capital-gains statements, property documents including rent agreements and home-loan interest certificates, and deduction receipts for insurance premiums, NPS contributions, tuition fees, and donations. The report also suggests tracking foreign assets and crypto transactions using a simple tracker reconciled with AIS quarterly, with Form 16 (now Form 130) to be provided by employers in May/June 2027.
As reported by Mint, taxpayers should check both Form 26AS (TDS/TCS ledger) and AIS (broader financial transaction coverage) on a quarterly basis, as they are generally updated within 45 days of quarter-end. Taxpayers can submit feedback against AIS entries and revise them multiple times, while for TDS mismatches, they should ask deductors to correct their TDS returns as Form 26AS pulls information from that filing. The report emphasizes conducting a final check of both documents before filing the ITR.
According to Mint reports, taxpayers should start with determining which regime suits them better - the new regime (default) allows only ₹75,000 standard deduction and limited other deductions, while the old regime maintains a wider list of deductions including ₹1.5 lakh deduction basket, NPS contributions, home-loan interest, HRA, and donation receipts. The report suggests comparing both regimes in September 2026, revisiting calculations after bonus or variable pay, and finalising the choice in February 2027. Notably, salaried taxpayers with no business or professional income can choose either regime while filing their ITR, regardless of what was declared to employers for TDS purposes.