A postgraduate medical student received ₹18.34 lakh as stipend from Aligarh Muslim University while pursuing an MS in General Surgery. The Income Tax Department treated the amount as taxable salary, but the Delhi Income Tax Appellate Tribunal (ITAT) has deleted the addition, holding that the stipend was connected with her postgraduate education and compulsory residency training. According to reports from Business Standard, the ruling came in Snehlata, Rewari vs ITO, Ward-1, Sonipat, ITA No. 5462/Del/2026 for assessment year 2024-25, with the order pronounced on 30 July 2026. The case involved a detailed legal battle where the Income Tax Assessing Officer from ITO, Sonipat, disagreed with the student and treated her educational stipend as taxable salary, while the Commissioner of Appeals (CIT A) also upheld the addition. Chartered Accountant Anirudh Bharadwaj represented the student before ITAT Delhi, with Judicial Member Satbeer Singh Godara hearing the case and passing the judgement.
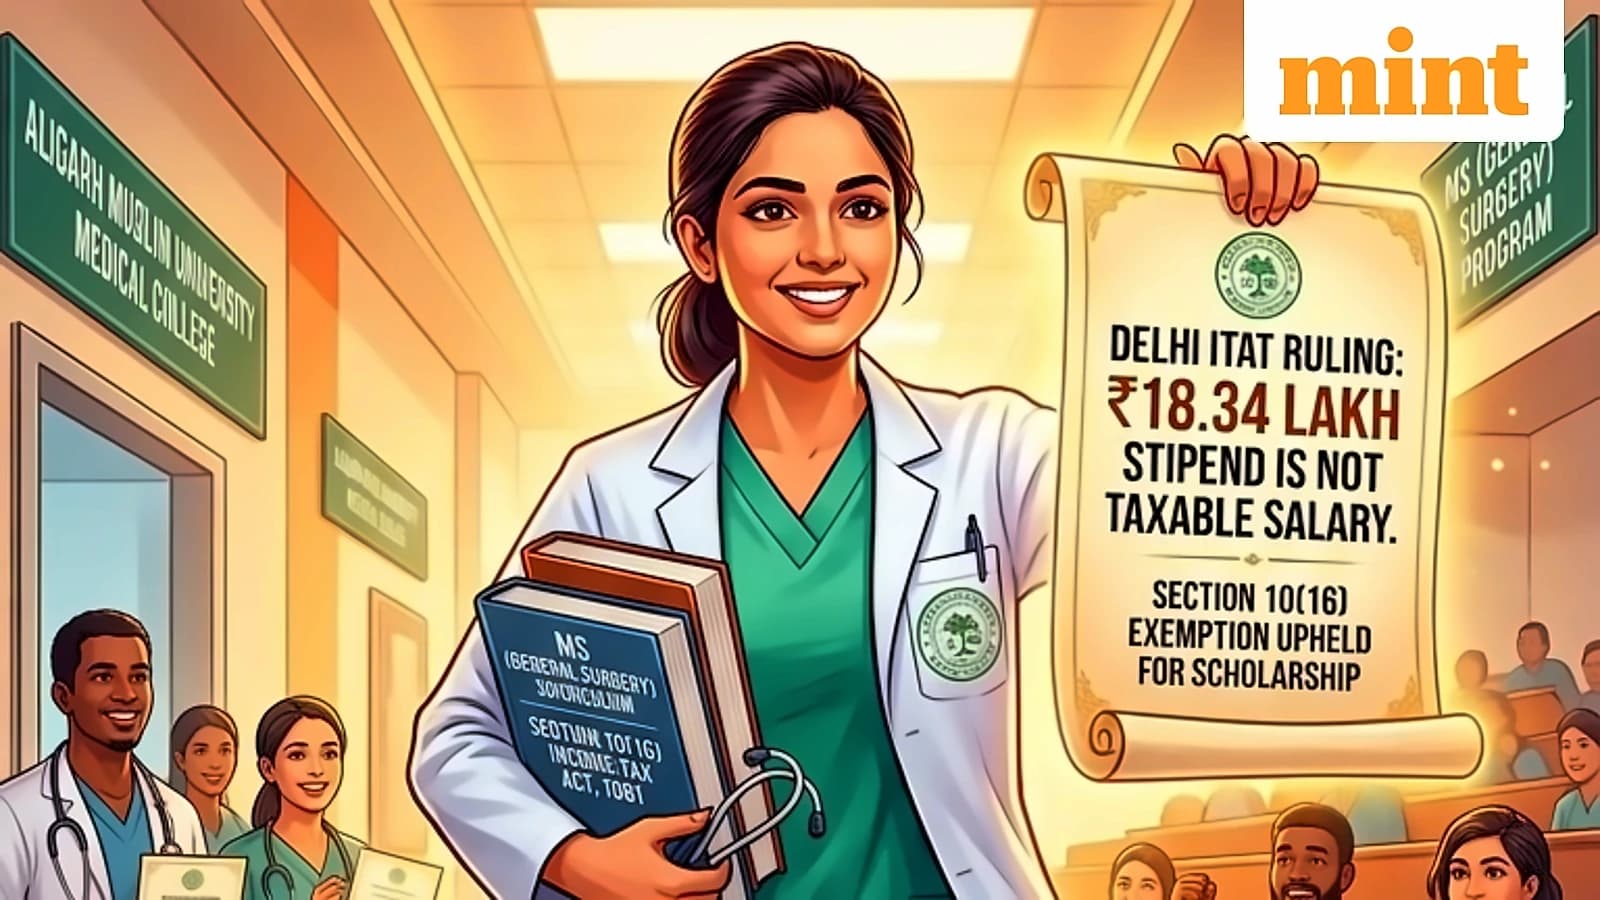
The Delhi tribunal examined an earlier decision of the Chandigarh ITAT in Hiteshi Aggarwal v. PCIT, where a medical doctor pursuing postgraduate studies had received ₹8.61 lakh as stipend. As reported by Business Standard, the Chandigarh ITAT had accepted the claim for exemption under Section 10(16), holding that the stipend received during postgraduate studies could not simply be equated with salary. The Delhi ITAT found the facts in Snehlata's case to be similar, noting that there was no dispute that she was a qualified MBBS doctor pursuing a full-time MS (General Surgery). The tribunal adopted the reasoning of the earlier Chandigarh Bench decision and deleted the ₹18,34,578 addition. According to Tax Guru, the Delhi ITAT applied the same reasoning to Smt Lata's case, noting that there was no dispute regarding her status as a postgraduate medical student or the fact that the stipend had been received while pursuing the MS (General Surgery) course and completing the compulsory residency attached to it. The tribunal treated the payment as being connected with the pursuit of education rather than remuneration arising from an ordinary employer-employee relationship.
Section 10(16) provides an exemption for scholarships granted to meet the cost of education. According to the ruling, the fact that a payment is called a stipend does not by itself determine its tax treatment. What matters is whether it is a scholarship granted to meet the cost of education. In Snehlata's case, the tribunal's decision turned on the educational character of the payment and its connection with the postgraduate medical course and compulsory residency training. The tribunal treated the payment as a scholarship or educational stipend rather than taxable salary. As reported by Tax Guru, scholarships, fellowships or research grants may qualify for Income Tax exemption if they are primarily intended to support the student's education, academic training or research. However, if the said scholarships, fellowships or research grants is given as remuneration for services rendered, it is taxable. The decisive test is the substance of the arrangement and the purpose for which the amount is paid, rather than the nomenclature used. This principle was applied in the case of Hiteshi Aggarwal v. PCIT, where stipend received during a postgraduate medical course was accepted as exempt under section 10(16).
The Delhi ITAT order provides a useful distinction for students receiving financial support during higher education. As reported by Business Standard, if the payment is a scholarship granted to meet the cost of education, Section 10(16) may provide an exemption. However, a payment that is actually remuneration for employment or services cannot become tax-free merely because the institution calls it a 'stipend' or 'scholarship'. The ruling is particularly relevant for professional courses where students may undertake practical or clinical training as part of their education, with the presence of such compulsory training not by itself meaning the amount received during the course must be treated as salary. According to Tax Guru, the fact that student performs practical or clinical duties as part of the course does not, by itself, convert the educational stipend into salary. The decisive factor remains the substance of the arrangement and the purpose for which the amount is paid, with the stipend's purpose needing to be examined to determine whether it is made to support education or is remuneration. Legal experts emphasize that the ruling does not create a blanket exemption for every stipend received by a student, with the facts and purpose of the payment remaining crucial for tax determination.