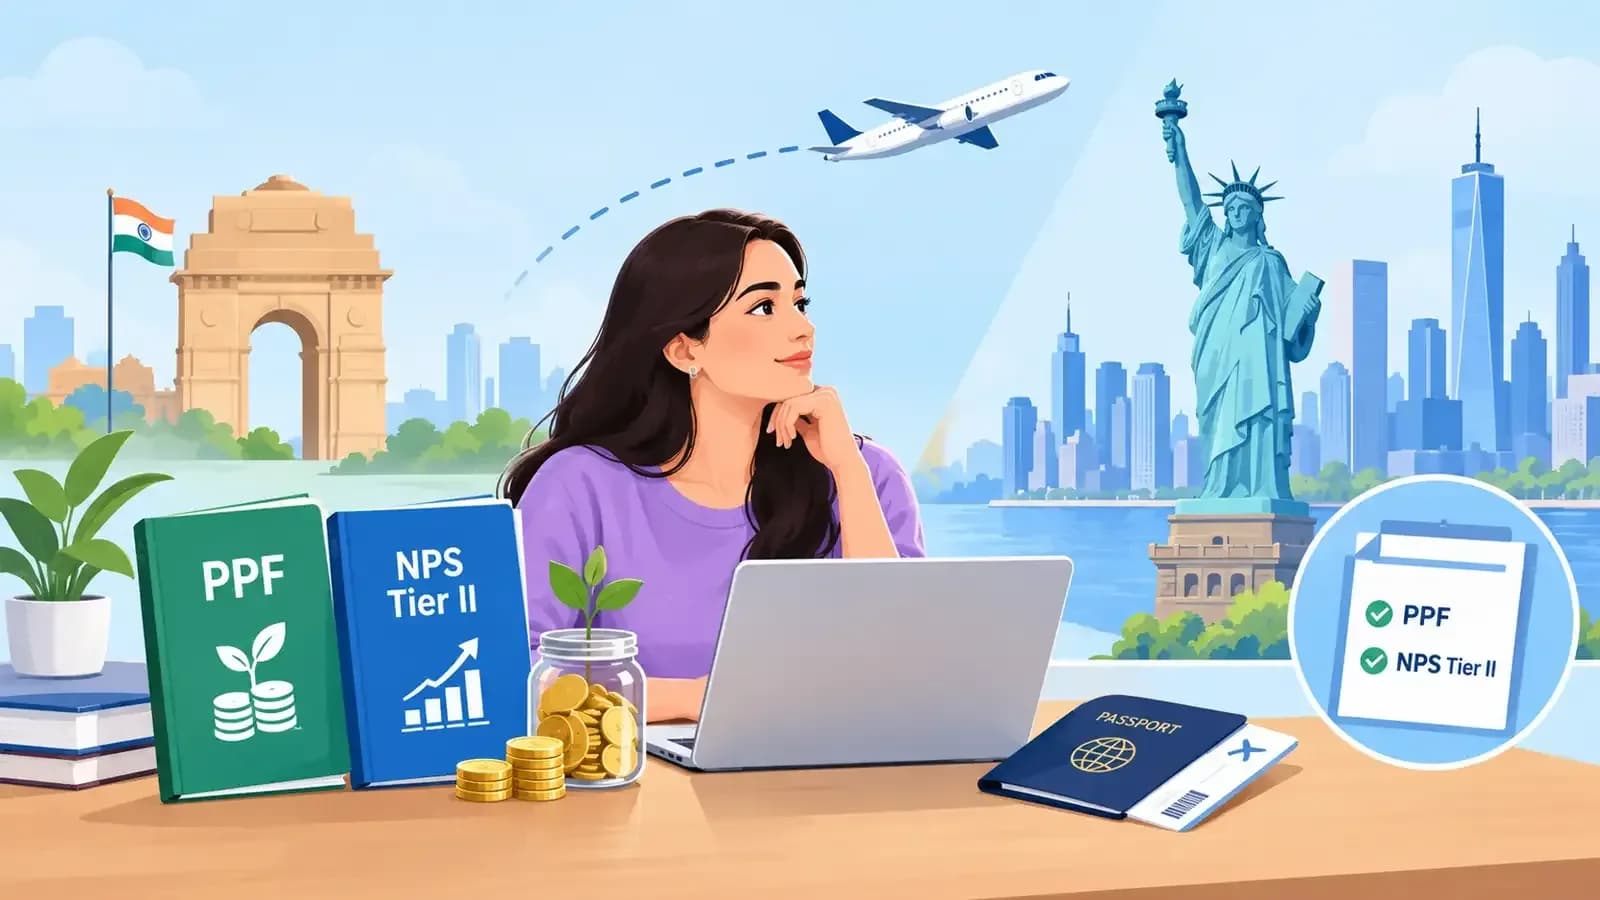
According to personal finance expert Balwant Jain, non-residents cannot maintain a Tier II account or continue contributions after becoming a non-resident under FEMA regulations. For individuals who have already established these accounts, they have two primary options: either transfer the balance to Tier I account or withdraw the money completely. The NPS trust must be notified of the non-resident status to ensure proper tax deduction at source on any redemption activities. As confirmed by tax expert Nishant Shanker from Navraj Global Advisors, an Indian who settles in the US should not assume that every existing Indian investment must be closed or transferred to family members. Each investment must be reviewed independently, with account holders promptly updating residential status and KYC details with relevant banks, post offices or NPS providers to obtain confirmation on further contribution permissions.
As reported by Jain, existing fixed deposits can continue but must be designated as NRO deposits after informing the bank about the change in residential status under FEMA. The bank will then deduct tax at the appropriate rate on interest earned. According to Shanker, existing FDs may often be retained after appropriate redesignation, and premature withdrawal or gifting should not be undertaken merely to reduce Indian tax or filing obligations. After withdrawal, the funds can be gifted to either parent depending on whose tax liability is lower, without creating any tax implications for either party, provided the gifts are genuine and documented.
According to the expert analysis, gifts to parents can significantly reduce India income and help avoid the requirement to file Income Tax Returns (ITR) in India. The gifts will not attract any tax liability for either party, with no clubbing of income in either situation. However, there may be tax implications in the country of residence at the time of making or receiving the gift, which may be treated as income in that jurisdiction but will not create any tax implications in India. Parents can also make gifts to their children without any clubbing or tax implications. As noted by Shanker, gifts between a daughter/son and their parents are generally not taxable in India, but they must be genuine and documented.
When Indians move to the US on a permanent basis, they must understand that their PPF and NPS Tier II investments are taxable in the US once they become US tax residents, and these earnings must be reported annually on Form 8938 and the Report of Foreign Bank and Financial Accounts (FBAR). According to Shanker, US tax residency can create separate tax and reporting obligations, which should be evaluated before any transfer or withdrawal. The broader classification shows that PPF accounts can remain active until maturity but cannot open new accounts or extend them after maturity once NRI, while NPS Tier II accounts must be closed, withdrawn, or transferred to Tier I accounts as NRIs. Seeking professional guidance from certified financial advisors is recommended to ensure meaningful, tax-efficient financial planning when faced with such situations.