According to Mint reports, joint home loans can significantly improve borrowing eligibility by combining spouses' incomes and repayment capacities. Pankaj Gadgil, MD & CEO of Aditya Birla Housing Finance, explains that lenders consider both applicants' incomes and repayment capacity, allowing couples to consider properties that may not be affordable on one income alone. The final loan amount depends on the lender's assessment of factors including income, credit history, and existing financial obligations. A joint loan allows both spouses to share EMI payments, making household cash-flow management easier and potentially reducing the EMI burden on any single individual. However, higher eligibility does not mean couples should borrow the maximum amount, as both borrowers share the repayment responsibility and any delays or defaults can affect both credit profiles.
According to Mint reports, home loan affordability should be calculated based on sustainable EMI levels rather than maximum bank sanctions. Sanjiv Bajaj, Joint Chairman & Managing Director of Bajaj Capital, recommends keeping home-loan EMI at around 30-35% of take-home income. For someone with monthly take-home income of ₹1.5 lakh, this translates to a comfortable EMI range of ₹45,000-52,500. However, Santosh Agarwal, CEO of Paisabazaar, notes that lenders generally prefer the total EMI ratio to remain within 50-60% of in-hand monthly income. As reported by Mint, the appropriate EMI amount depends on existing expenses, debt, and financial goals beyond the bank's willingness to lend. Bajaj warns that when EMI reaches 40% or more of take-home income, households can start losing financial flexibility, particularly if there are other loans or high recurring expenses.
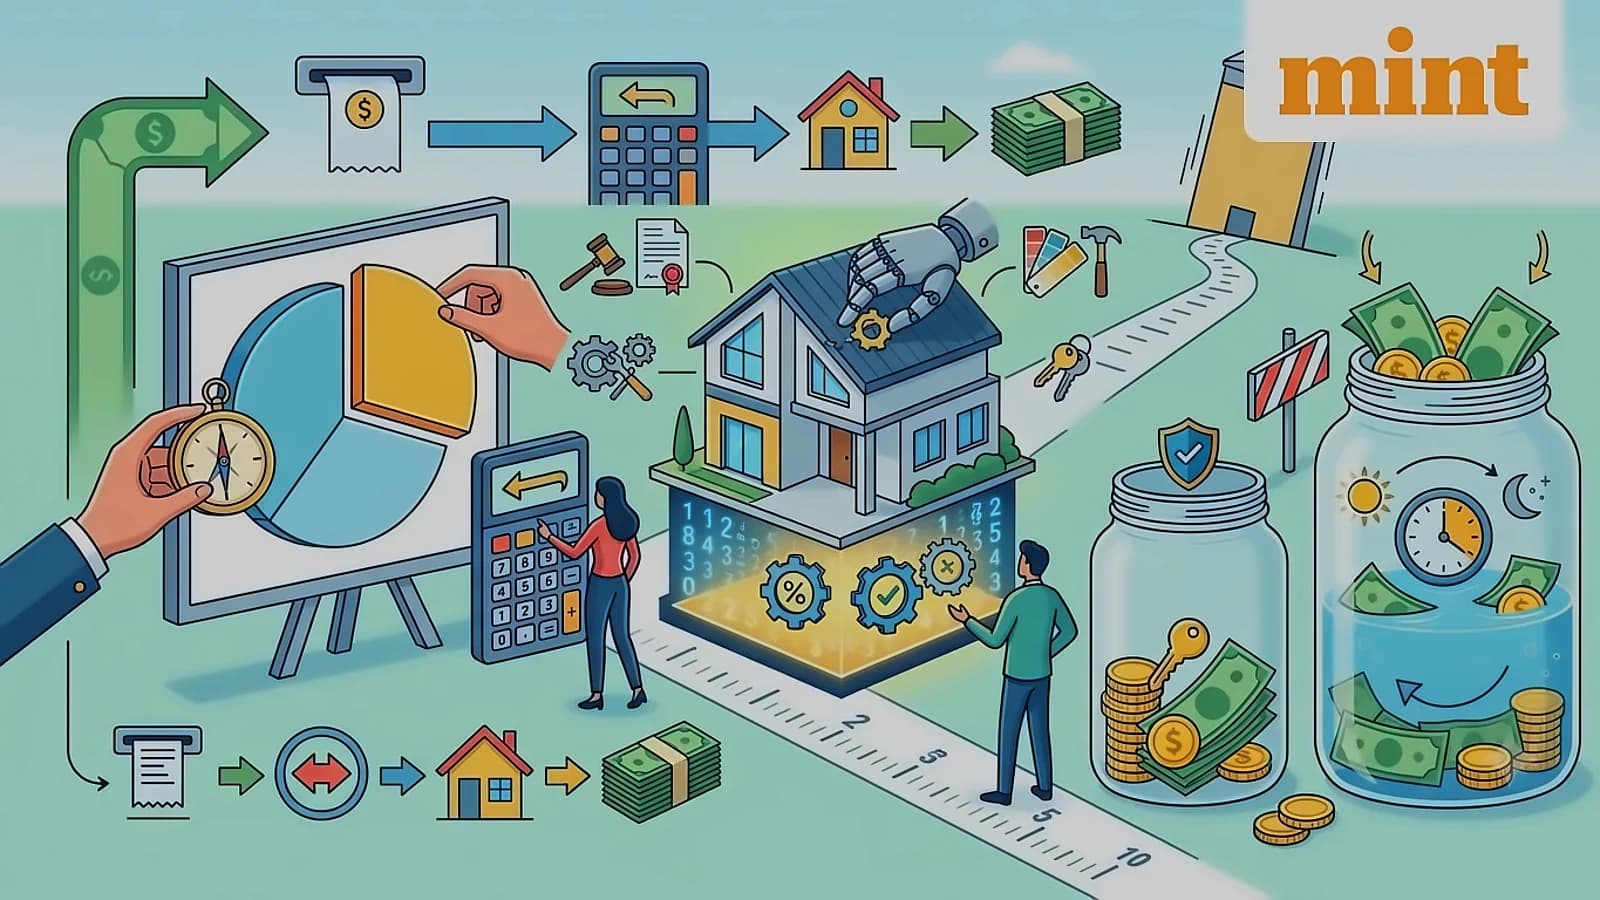
As reported by Mint, buyers should work backwards from sustainable EMI calculations instead of starting with maximum loan amounts. The process involves calculating monthly surplus after accounting for essential expenses, existing EMIs, and ongoing investments. Bajaj Capital's Sanjiv Bajaj emphasizes starting with what can be comfortably paid monthly after existing commitments are accounted for. Santosh Agarwal from Paisabazaar recommends calculating sustainable EMI first and then determining the home-loan amount that this EMI can support. Interest rates and loan tenure should also be factored into calculations, as longer tenure may reduce monthly EMI but increase total interest outgo over the loan's lifetime. Agarwal notes that a larger down payment can reduce the loan amount and interest burden, but putting almost all available savings into the property can leave the household without enough liquidity for emergencies.
According to Mint reports, maintaining adequate emergency reserves is crucial for home loan affordability. Bajaj Capital's Sanjiv Bajaj recommends retaining at least six months of essential expenses and EMIs as a buffer after making the down payment. For self-employed buyers, he suggests maintaining a larger reserve of 9-12 months depending on income variability. Santosh Agarwal from Paisabazaar similarly recommends keeping an emergency fund covering 6-12 months of unavoidable monthly expenses, including EMIs, rent, school fees, insurance premiums, and household expenses. The emergency fund should remain liquid and not depend on selling investments quickly or at unfavorable prices. Self-employed borrowers should maintain a higher buffer because their cash flows can be less predictable. Mint emphasizes that couples should plan for situations such as temporary loss of income or career breaks, maintaining adequate emergency funds and suitable life insurance coverage to ensure continued loan servicing during unexpected financial setbacks.
As reported by Mint, home ownership involves costs beyond the purchase price and EMI. Additional upfront expenses include stamp duty, registration, brokerage, paperwork, and transfer-related costs. Recurring expenses such as maintenance, property tax, and insurance must also be budgeted for. Buyers may additionally need to spend on interiors, furniture, or other costs after taking possession. These expenses can reduce cash availability after purchase and should be included in affordability calculations. According to Mint, the key numbers to calculate before buying a house include comfortable EMI, corresponding loan amount, down payment without exhausting savings, and emergency corpus remaining after the purchase. As noted by experts, a bank's loan sanction tells a buyer how much they can borrow, but their own cash flow determines how much they can realistically afford without putting other financial goals on hold.