Health insurance experts emphasize that adequate base sum insured should come first before considering additional riders, according to reports from Mint. Amitabh Jain, COO of Star Health Insurance, explained that an adequate base sum insured protects against overall hospitalization costs, while add-ons typically address specific expenses or situations. Shashi Kant Dahuja, Executive Director & Chief Underwriting Officer at Shriram General Insurance, advised policyholders to first assess whether their existing base policy provides adequate coverage for healthcare needs before considering add-ons for risks not sufficiently covered by the base policy.
Experts warn against choosing riders at the expense of adequate core coverage, as reported by Mint. Gurmeet Singh, Vice President & Head – Health Underwriting at IFFCO-TOKIO General Insurance, stated that buying several riders while keeping the base sum insured too low may be insufficient for overall protection. Renuka Kanvinde, Vice President – Health Insurance at TATA AIG General Insurance, emphasized that priority should be given to strengthening foundational coverage before supplementary benefits are added. The objective should focus on meaningful financial protection rather than maximum feature accumulation, according to Jain from Star Health Insurance.
Add-ons become useful when they address genuine gaps in base policy coverage, as reported by Mint. For instance, policyholders may consider benefits that provide additional protection against specific medical expenses or restore sum insured after usage. OPD benefits could be relevant for families with recurring outpatient expenses, while hospital cash can provide fixed benefits during hospitalization. However, there is no universal list of add-ons that every policyholder needs, with decisions based on individual health needs, age, family profile and likely medical expenses rather than adding every available benefit.
Consumables cover can reduce out-of-pocket expenses that may otherwise be excluded from the main health insurance policy, covering items such as gloves, masks and syringes. As per Mint, such expenses may seem small individually but can add to policyholder expenses during hospitalization. Hospital cash provides fixed benefits for each eligible day of hospitalization, helping meet expenses such as caregiver costs, transportation, loss of income and other incidental expenses not covered by the main policy. OPD cover may be relevant for individuals or families with regular outpatient expenses, providing benefits for consultations, treatments, dental and vision care, and pharmacy expenses. Critical illness benefits can provide additional financial cushion for specified illnesses, while personal accident cover offers support for accidental death or disability.
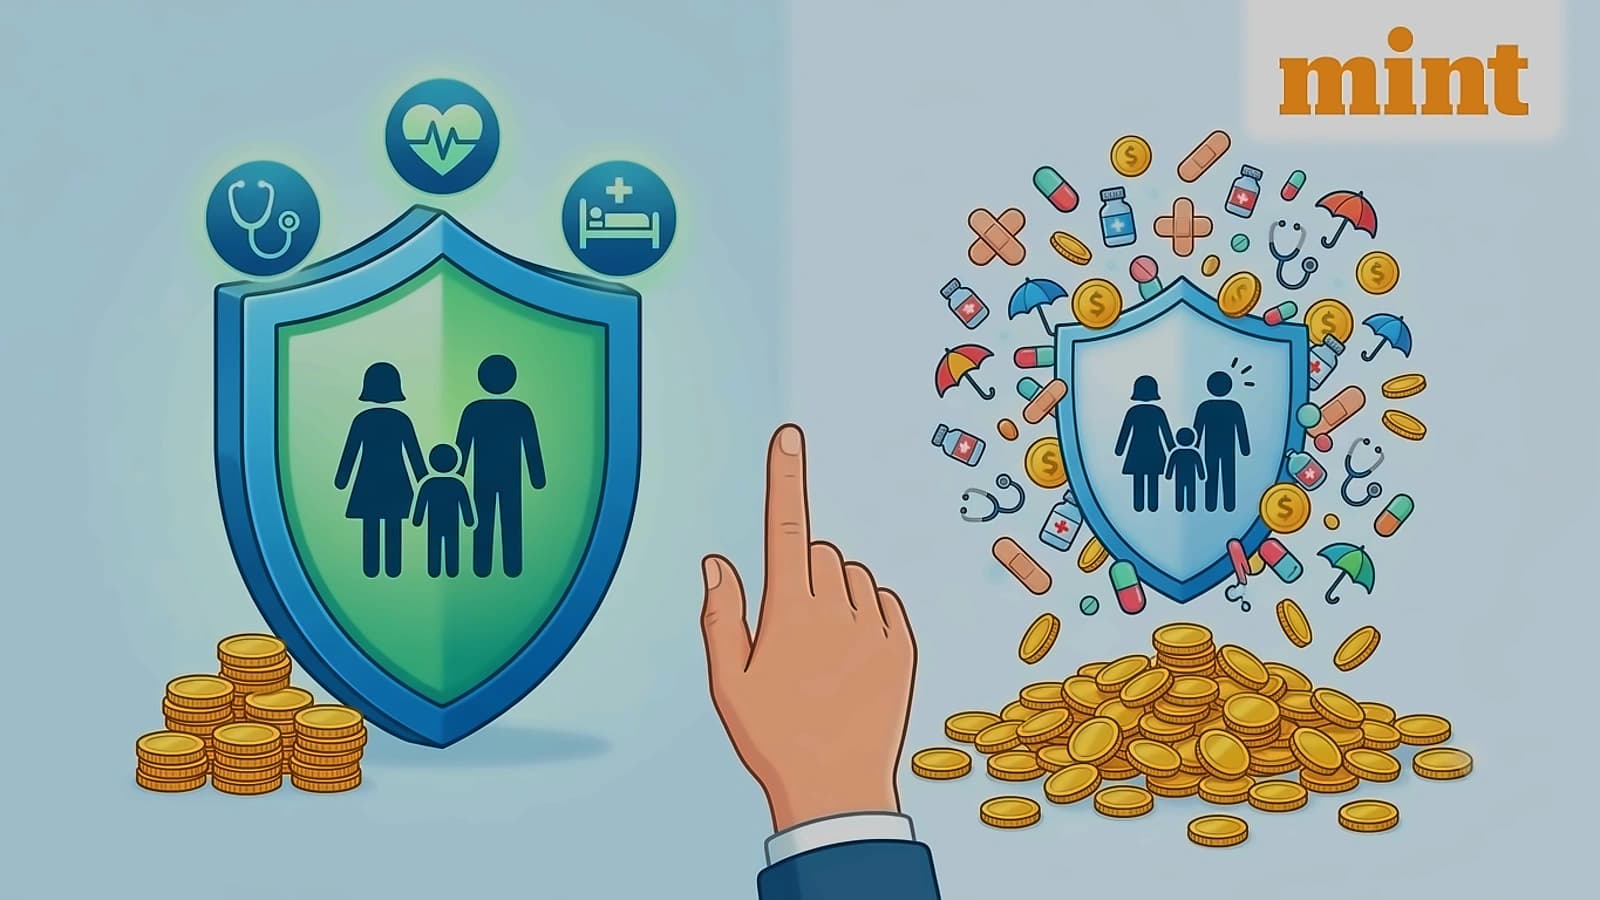
Before purchasing riders, policyholders should compare the additional premium with actual benefits, exclusions, waiting periods and costs, according to Mint reports. Dahuja from Shriram General Insurance advised checking waiting periods, exclusions, sub-limits and eligibility conditions before opting for add-ons. Singh emphasized that consumers should compare sum insured, coverage, exclusions, sub-limits, waiting periods, network hospitals and premium rather than choosing policies based solely on rider availability. The same principle applies when choosing between comprehensive policies with fewer add-ons and lower-cost policies with several riders.
Maintaining continuous health insurance coverage requires timely policy renewal, as missing renewal deadlines can lead to policy lapse and loss of accumulated benefits, according to Mint. Policyholders should track renewal dates early and utilize the 15- to 30-day grace period if immediate payment is missed. Key renewal considerations include assessing evolving healthcare needs based on life stage changes, enhancing sum insured to keep pace with medical inflation, and reviewing updated policy terms for any structural changes under IRDAI guidelines. The right combination of coverage will depend on individual health needs, age, family profile, and budget, with decisions based on specific financial risks rather than simply adding every available benefit.