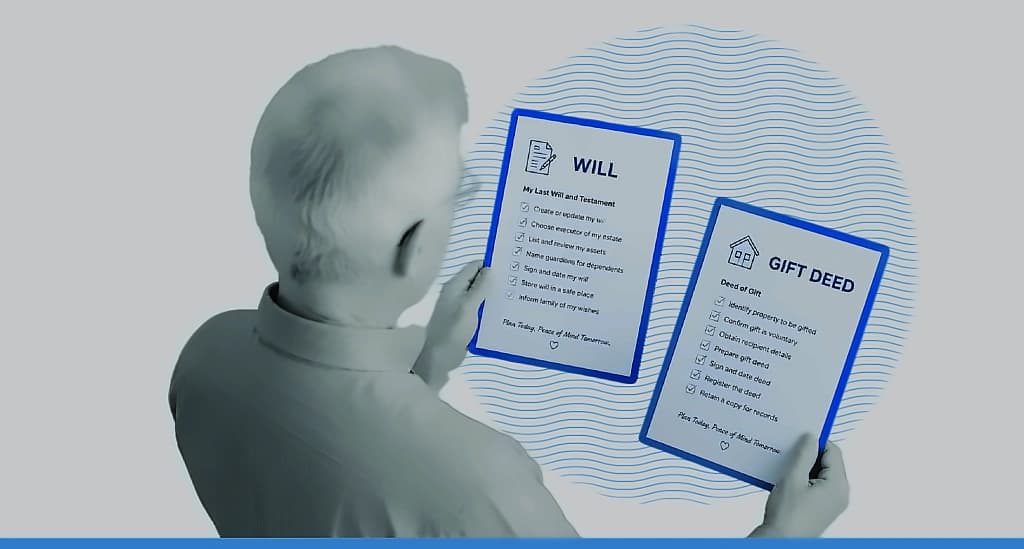
Senior citizens face a fundamental choice between gift deeds and wills when transferring property to children. According to estate planning guidance, a gift deed transfers ownership immediately upon registration and requires the child's acceptance while the donor is alive. In contrast, a will holds property until the donor's death, allowing rewriting or cancellation during their lifetime. The choice between these options depends on whether settling matters early or maintaining control until death is more important to the donor.
Gift deeds offer significant tax advantages for property transfers between relatives. As reported by estate planning experts, gifts between parents and children carry no income tax under Section 56(2)(x) of the Income Tax Act, with no capital gains tax liability since the transaction isn't treated as a sale. For transfers after July 23, 2024, long-term capital gains are generally taxed at 12.5% with indexation removed, though grandfathering relief may apply for properties acquired before this date. Stamp duty costs vary significantly by state, with Maharashtra charging as low as ₹200 for gifts to lineal descendants, while Delhi charges approximately 2% of stamp duty value plus ₹1.2 lakh registration fees.
Property transfers can significantly impact Medicaid eligibility for both donors and recipients. According to Medicaid planning experts, while a bona fide sale for fair market value is generally treated differently from gifts for Medicaid purposes, the proceeds from such sales could become countable assets affecting ongoing eligibility. Some people establish irrevocable trusts early enough to avoid the five-year look-back rule, with assets properly transferred into a Medicaid Asset Protection Trust (MAPT) generally not counted for Medicaid eligibility purposes. Nebraska's expanded estate recovery system allows Medicaid to seek recovery against assets in which the recipient had legal interest at death, even if property transfers automatically to heirs. Whether jointly owned property with rights of survivorship is subject to recovery depends on deed language and other variables.
Before making property transfers, donors must evaluate their future living expenses, healthcare costs, and unexpected financial needs. As reported by financial advisors, gifting assets during lifetime requires ensuring sufficient liquidity remains for personal care and unexpected expenses. The decision affects not only the primary recipient but also other children who may receive smaller portions of the estate. Estate planning lawyers recommend weighing property against income, health status, and the entire estate to ensure the chosen route maintains financial independence across unpredictable future years.