The mutual fund industry has witnessed a dramatic shift toward direct investing, with retail investors leading the transformation. According to latest AMFI data, direct-plan retail AUM surged from ₹1.6 trillion in March 2021 to nearly ₹7 trillion in March 2026, representing a more than fourfold increase. The direct-plan share in retail AUM has grown from 21.4% in March 2021 to 36.7% in March 2026, while regular-plan assets under management has only doubled during the same period. This shift reflects the steady expansion of self-directed investing, supported by digital access, greater product awareness and increasing sensitivity to costs, as noted in a joint report by AMFI and CRISIL.
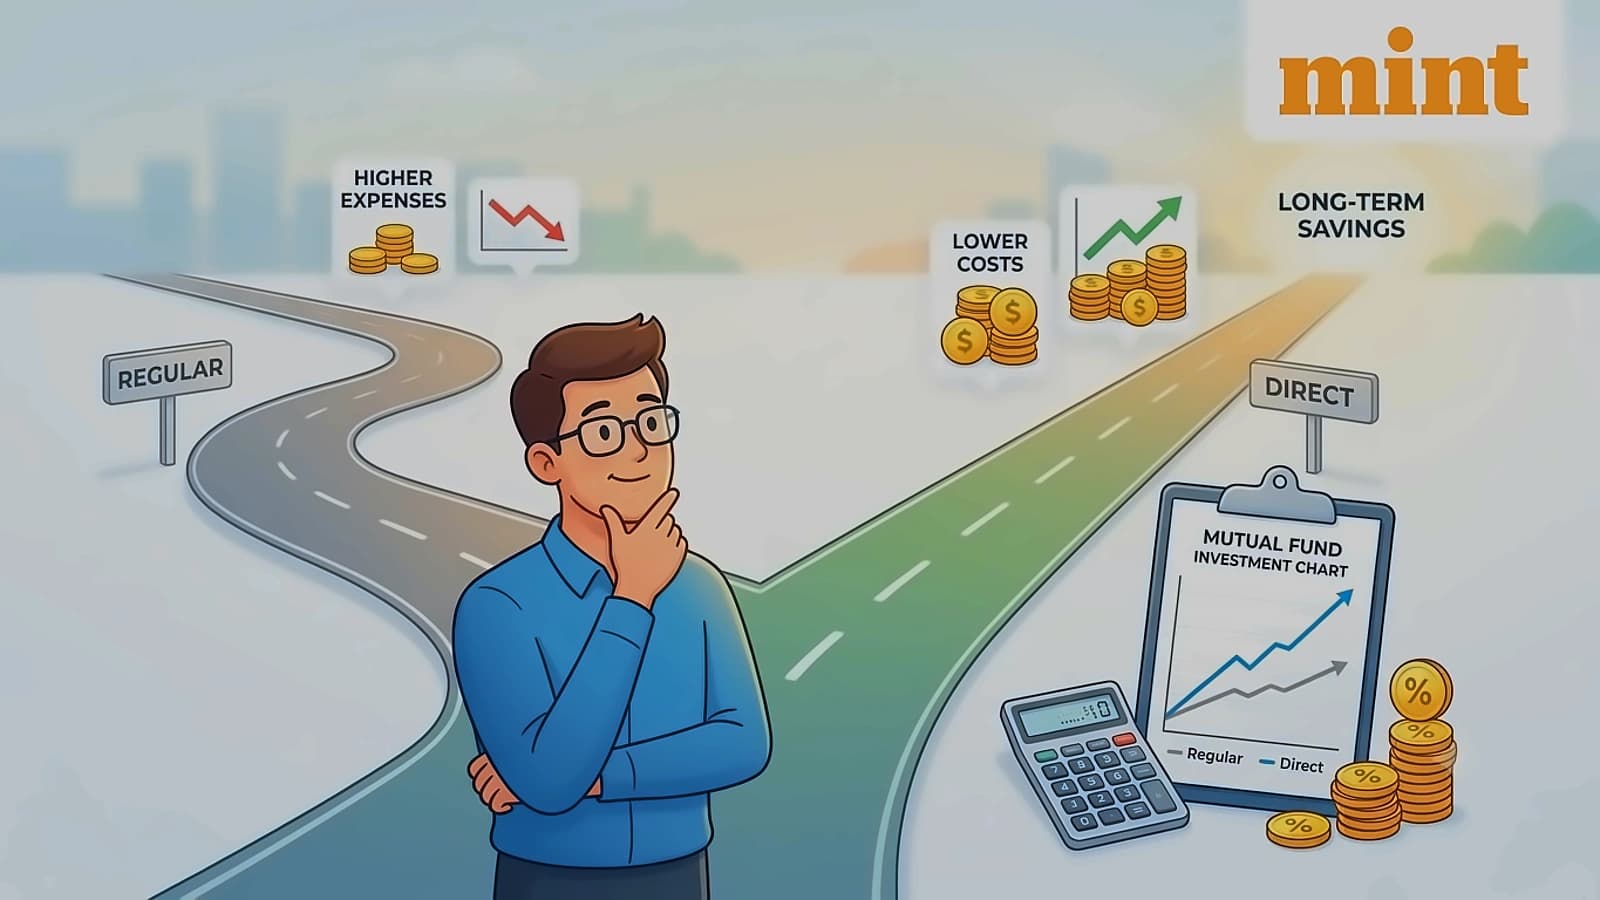
The expense ratio structure creates meaningful differences over time. Regular Plan expense ratio = 1.80% compared to Direct Plan expense ratio = 1.20%. While this 0.60% difference may appear insignificant today, because investments compound every year, this small difference can become substantial over decades. For example, with a net return after expenses of 10.20%, a Regular Plan would generate approximately ₹69 lakh future value, while a Direct Plan would yield approximately ₹78 lakh - a difference of nearly ₹9 lakh over the investment period.
Direct Plans have experienced significant growth across all investor categories, with retail investors leading the transformation. The direct-plan share in high net-worth individual (HNI) AUM has grown from 28.8% to 35.1% in the five-year period, while corporate investors have seen regular plans gain share from 22% to nearly 29%. Direct plans accounted for 45.1% of the industry's total AUM in March 2026, only a small increase from 43.4% in March 2021, as regular plans have a higher ticket size on the individual investor side. The number of accounts opened on the direct side has been outpacing regular plans, with direct plans adding 25.2 million net accounts in FY26 compared to 14.2 million on the regular side.
Regular Plans provide valuable professional guidance that many investors find worthwhile. They include distributor or advisor commissions within the expense ratio, covering services such as investment advice, portfolio reviews, and ongoing financial guidance. Regular Plans are suitable for investors who: have limited knowledge of mutual funds, need help planning financial goals, prefer ongoing portfolio monitoring, want assistance with tax-efficient investing, and need emotional support during market corrections. Many busy professionals choose Regular Plans simply because they value expert advice more than the small cost difference.
The decision between Direct and Regular Plans depends on your knowledge, experience, and need for advisory support. If you're confident managing investments, understand portfolio construction, regularly review investments, and don't require advisory support, Direct Plans may be suitable. However, if you need professional guidance, prefer ongoing portfolio monitoring, want help with financial planning, and value expert advice, Regular Plans may be the better choice. The key is to evaluate the overall value you receive rather than basing decisions solely on commission differences, as poor investment decisions can easily cost much more than the commission paid in a Regular Plan. The shift toward direct investing reflects the growing confidence of retail investors in managing their own investments through digital platforms and self-directed strategies.