The Employees' Provident Fund Organisation has clarified that an employee who exits employment before the age of 55 can continue to receive interest on the EPF balance until turning 58, subject to applicable rules. According to EPFO's frequently asked questions, when an employee retires voluntarily before 55, the account can continue to earn interest until the member reaches 58. This is particularly relevant for people who take a career break, retire early, become self-employed or leave formal employment and decide not to withdraw their accumulated provident fund corpus. The EPFO has reiterated this point through a recent post on X, specifically stating that accounts will earn interest up to the member's age of 58. As per the EPFO's post on X, interest will continue until age 58, after which the EPF account will become inoperative. The EPFO has also provided detailed guidance on when accounts become inoperative, with specific timelines for different retirement scenarios.
The important distinction is between stopping contributions and stopping interest. Once an employee leaves a job, fresh monthly contributions from that employer stop, but the existing EPF balance does not automatically stop earning interest simply because the employee is no longer on the payroll. EPFO's FAQ specifically gives the example of an employee who voluntarily retires at 50, stating that interest would still be paid until the member reaches 58 because the account becomes inoperative only when the member turns 58. The same principle applies to someone leaving employment at 40, provided the account continues to qualify for interest under applicable EPF rules. Many employees mistakenly believe that an EPF account stops earning interest as soon as there are no fresh monthly contributions, but EPFO's current position clearly states that accounts will earn interest up to age 58. The effect of compounding becomes more significant over a long period, with interest credited to the existing corpus earning interest in subsequent years even without new contributions.
EPFO classifies an account as inoperative when no contribution has been received for three years after retirement, permanent migration abroad or in the event of the member's death. An inoperative account does not earn further interest. However, for employees leaving employment before 55, EPFO's specific guidance states that interest can continue until age 58. According to EPFO's FAQ, an employee who retires on attaining 58 can receive interest up to 58, if an employee voluntarily retires at 50, interest can continue until 58, and if an employee retires at 60, interest is payable up to 63. The EPFO distinguishes between an account with no fresh contributions and an inoperative account, with accounts earning interest up to age 58, and once the account becomes inoperative, it does not earn further interest. Recent EPFO guidance confirms that an account may become inoperative under specific circumstances, such as if a member retires at age 55 or older, the account will become inoperative 36 months after the last contribution. The rules governing inoperative EPF accounts have changed over the years, with the government stating that interest is credited to an EPF account up to the age of 58 under the amended provisions.
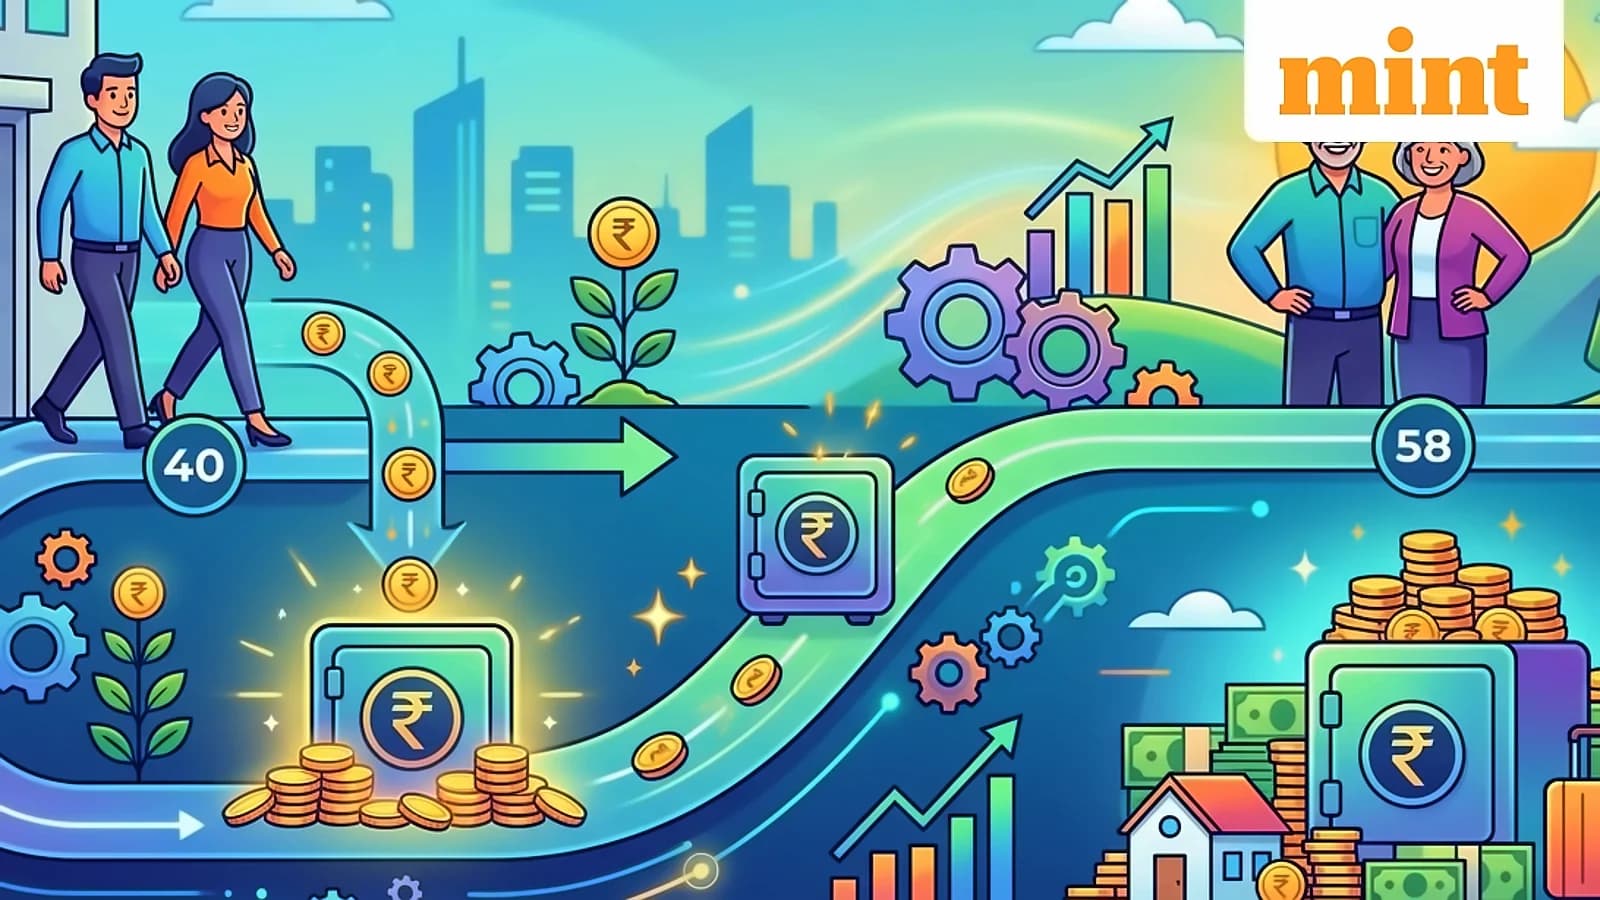
For someone leaving a job at 40, the practical takeaway is that the EPF balance can remain invested in the account and earn interest until 58, rather than interest stopping on the employee's last working day. EPFO advises that if a person expects to return to formal employment, transferring the existing EPF balance to the new employer's EPF account can generally be more useful than withdrawing it. Keeping the money within the EPF system avoids prematurely breaking the retirement corpus and helps consolidate retirement savings if the member later joins another EPF-covered employer. The Universal Account Number (UAN) is designed to provide continuity to a member's EPF records across employers, making it easier to transfer accumulated balances when changing jobs. Members should not assume that leaving an old account untouched for years means that it will continue earning interest forever, as the age-related rules still apply. Before deciding to withdraw, transfer or retain the balance, members should check their EPF passbook and the status of the account. Recent guidance emphasizes that an inactive or inoperative EPF account does not mean that money is lost, with members able to file Form 19 online to withdraw money or use Form 13 for balance transfers.