The Income Tax Rules, 2026 have significantly increased the annual tax-free limit on employer-provided gifts, vouchers and tokens from ₹5,000 to ₹15,000. According to reports from Mint, this benefit is available as an aggregate annual limit per employee, not separately for each occasion such as Diwali, birthdays or work anniversaries. The change took effect from 1 April 2026 and applies to gifts received during the tax year ending 31 March 2027. As per OneBanc Technologies, this represents the first revision in over two decades for meal exemptions, with the exemption for employer-provided meals rising from ₹50 to ₹200 per meal.
The new tax rules have introduced a ₹1.05 lakh annual exemption for employer-provided meal vouchers, significantly expanding tax-saving opportunities for salaried employees. As per Ebizfiling, meal vouchers are now tax-free up to ₹200 per meal when provided during working hours at office premises or through paid vouchers usable only at eating joints. The exemption is calculated based on 2 meals per working day and 22 working days per month, resulting in a ₹8,800 monthly exemption and ₹1,05,600 annual benefit. This benefit is available under both old and new tax regimes, making it a viable tax-saving alternative for employees. According to OneBanc Technologies, this represents a dramatic increase from the previous ₹26,400 annual limit, with the meal benefit surviving an employee's regime choice under perquisite valuation.
As reported by Mint, the provision covers gifts, vouchers and tokens subject to applicable tax rules, with digital gift cards and shopping vouchers being particularly relevant due to their convenience and choice they offer employees. However, gifts in cash or convertible to money, such as gift cheques, are fully taxable. Arvind Prabhakar, CEO and Co-founder of GyFTR, explained that the exemption threshold applies to both old and new tax regimes, making non-cash rewards more attractive for employers and employees. The meal voucher exemption is subject to specific conditions including non-transferability, usage only for food and non-alcoholic beverages, and compliance with daily restrictions. According to OneBanc Technologies, employers face liability for non-compliance, with cash allowances being fully taxable and any reclassification risks carrying communications budgets.
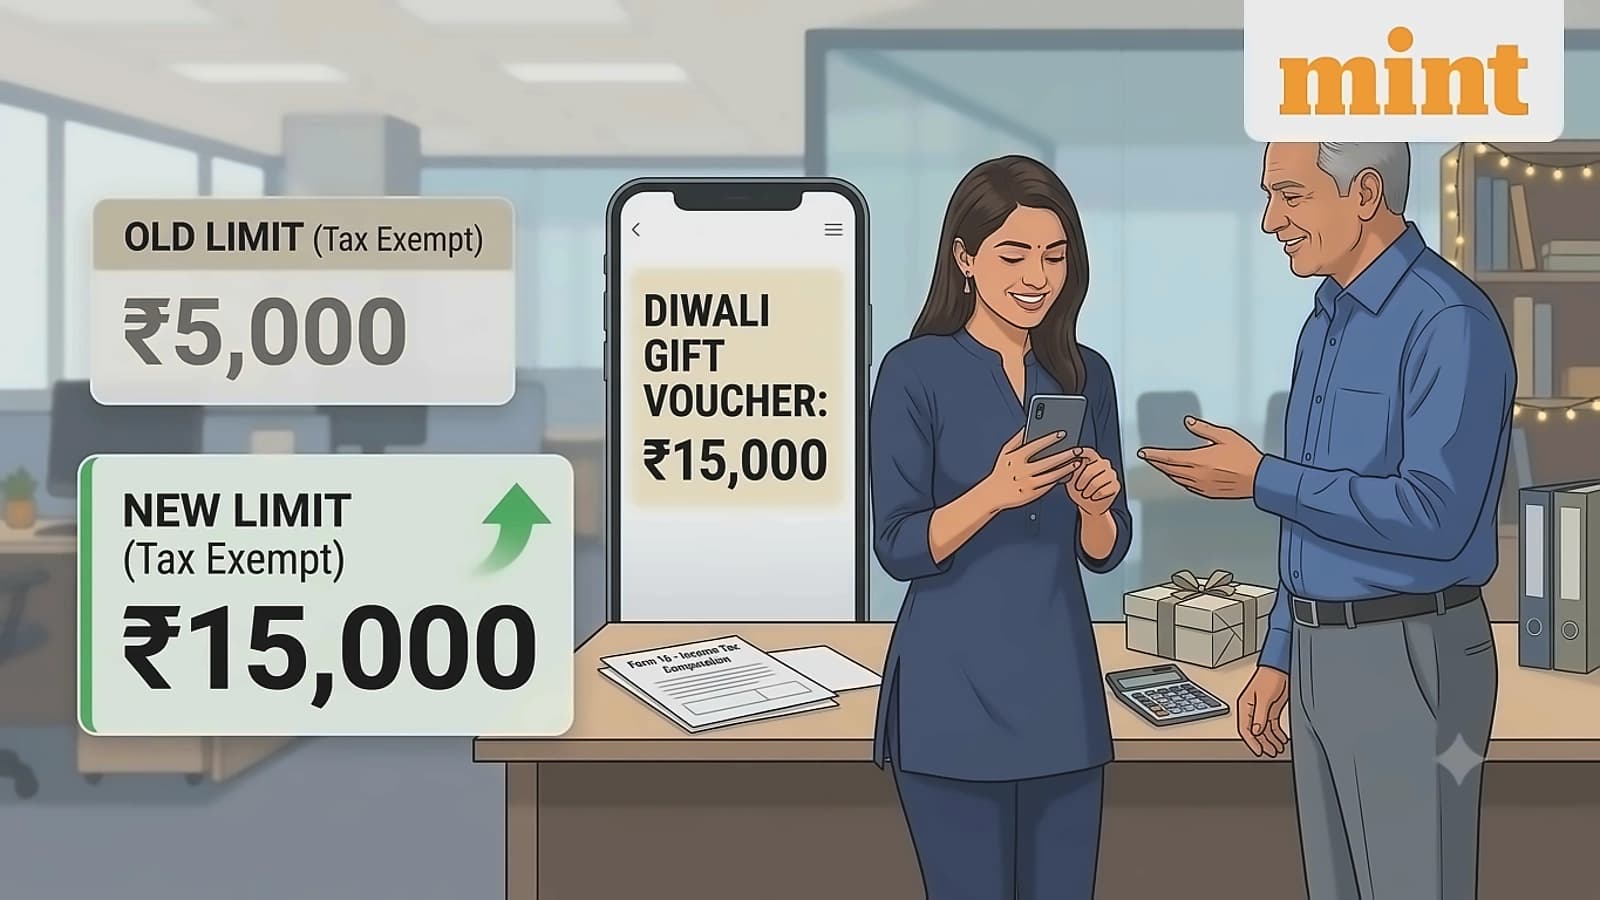
The new tax rules could significantly reshape employee compensation strategies as companies rethink their Cost to Company (CTC) structures. As per OneBanc Technologies, 88% of individual taxpayers have adopted the new tax regime, fundamentally changing the addressable population for benefit design from a shrinking minority to nearly all of the payroll. For employees in the 30% tax bracket, the potential additional ₹200K exemption is worth approximately ₹60K in hand salary without changing the CTC. This represents a permanent liability rather than an annual grant, unlike traditional increments that compound into next year's base. The analysis suggests that compensation advantage in 2026 will come from reading the rulebook more carefully than competitors rather than spending more, as every competitor has the same 9.1% budget allocation.
According to Mint reports, the tax treatment depends on the nature and value of the benefit rather than whether it forms part of an employee's Cost to Company (CTC). Employers must ensure benefits are correctly accounted for through payroll, with the employer determining applicable tax treatment and reporting any taxable perquisites in the employee's Form 16, now referred to as Form 130 under the Income Tax Act, 2025. Employees should reconcile these details with their ITR while filing their tax returns. For meal vouchers, compliance is crucial as any misuse or failure to meet prescribed conditions may result in exemption disallowance by tax authorities. As per OneBanc Technologies, benefits without an audit trail are not benefits but reclassification risks with communications budgets attached, making evidence-based tracking essential for program success.