Financial planners emphasize that health insurance and emergency funds serve different purposes and should not be treated as competing financial goals. According to Mint reports, Anooj Mehta, Partner at 1 Finance, recommends that for someone starting with limited savings, the practical approach is to buy adequate health insurance first and build an emergency corpus alongside it. "The decision for Emergency Fund or Health Insurance is not a choice one should make over another, these go parallel," Mehta stated. For a healthy 35-year-old, health insurance premiums of ₹12,000-₹15,000 annually for a ₹10 lakh individual cover should be viewed as a relatively small recurring expense rather than competing with long-term investments.
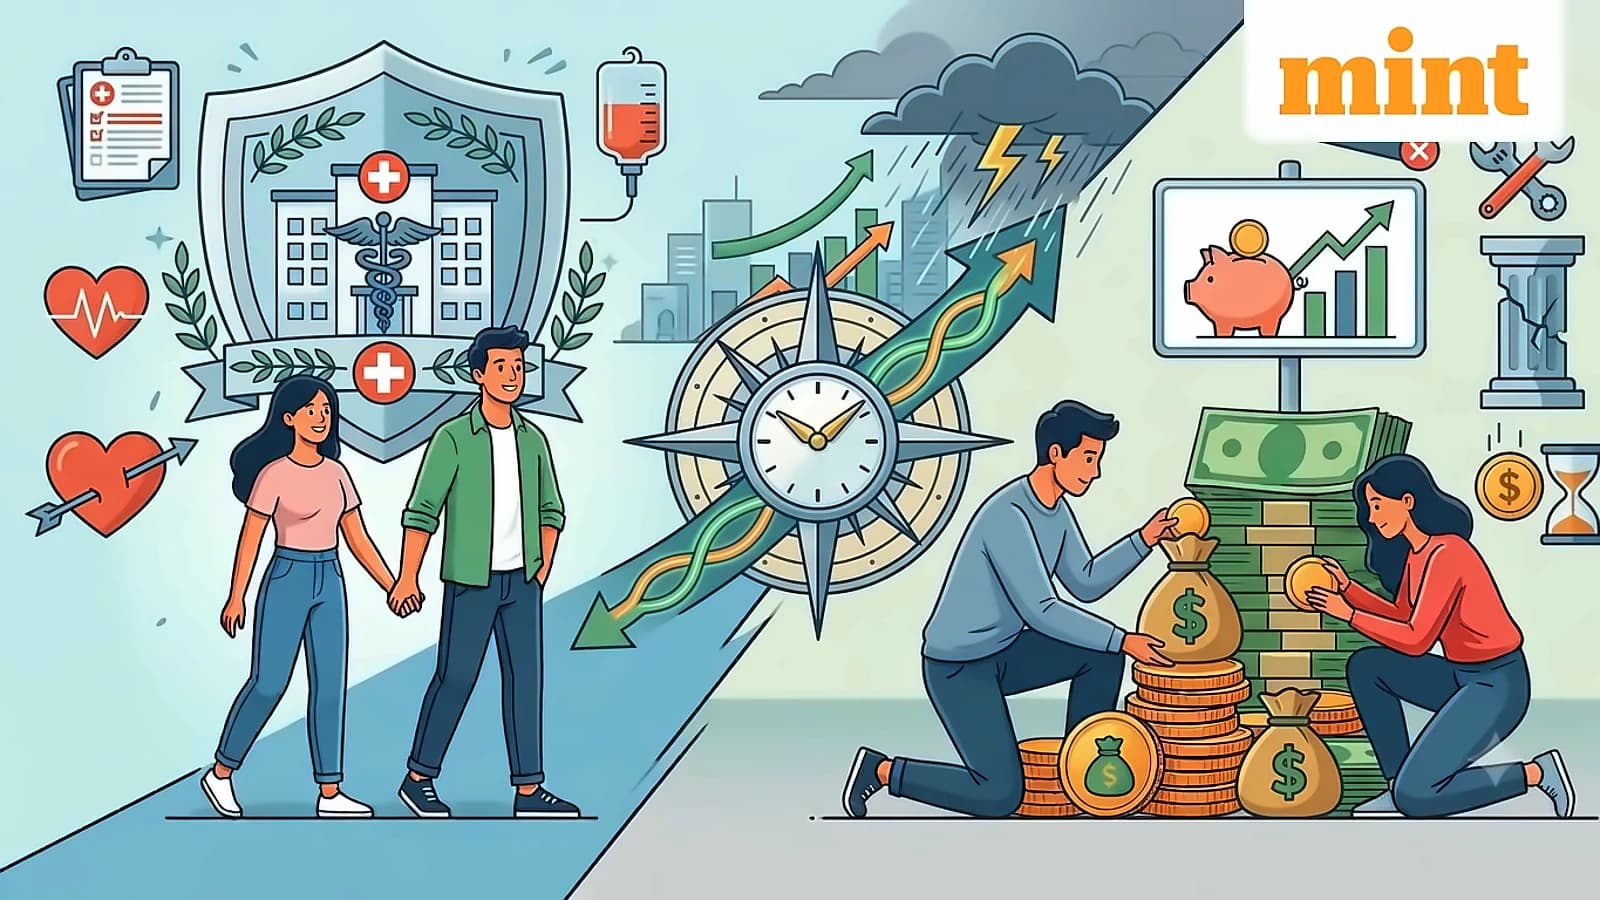
The commonly followed six-month emergency fund rule serves as a useful starting point, but financial experts recommend calculating the corpus based on committed monthly expenses rather than total spending or income. As reported by Mint, for a household with ₹80,000 in committed monthly expenses, three months would amount to ₹2.4 lakh and six months would require ₹4.8 lakh. However, income stability determines the ideal amount - single-income households and employees with commission-linked pay may need 9-12 months of expenses, while households with two stable incomes can manage with six months. Mehta also recommends keeping ₹1 lakh-₹2 lakh as a separate medical buffer within the broader emergency corpus.
Medical costs present significant financial risks that savings alone cannot adequately address. According to Mint reports, medical inflation of around 13-14% means procedures costing ₹5 lakh today could cost ₹17-18 lakh a decade from now. Relying on savings for major medical expenses can result in unfavorable investment liquidation, tax implications from equity sales, and derailment of financial goals. Additionally, serious illness can become a pre-existing condition, potentially affecting future health insurance availability. Mehta warns that insurance covers the bill, it doesn't cover everything on the bill - policyholders may still need to pay for consumables, diagnostics, and post-discharge expenses. Recent analysis reveals that health insurance acts as a financial buffer during illness or injury, helping share eligible expenses with the policy and reducing potential for large medical debts.
The distinction between emergency funds and health insurance is crucial for comprehensive financial protection. As reported by Mint, an emergency fund provides liquidity for frequent, smaller financial disruptions such as job loss or temporary income gaps, while health insurance protects against low-frequency but high-severity events like major hospitalizations. Mehta highlights that people often make the mistake of holding substantial cash savings while relying on relatively small employer health coverage, such as someone with ₹15 lakh in fixed deposits but only ₹5 lakh of employer-provided health insurance. The emergency corpus should be kept in liquid instruments like savings accounts or fixed deposits, and health insurance should be in place with completed waiting periods before considering the emergency fund adequately funded. Recent guidance emphasizes that insurance helps manage medical debt by sharing costs and providing financial protection for health events, with coverage typically conditional on policy terms and exclusions. Recent analysis reveals that health insurance acts as a financial buffer during illness or injury, helping share eligible expenses with the policy and reducing potential for large medical debts.