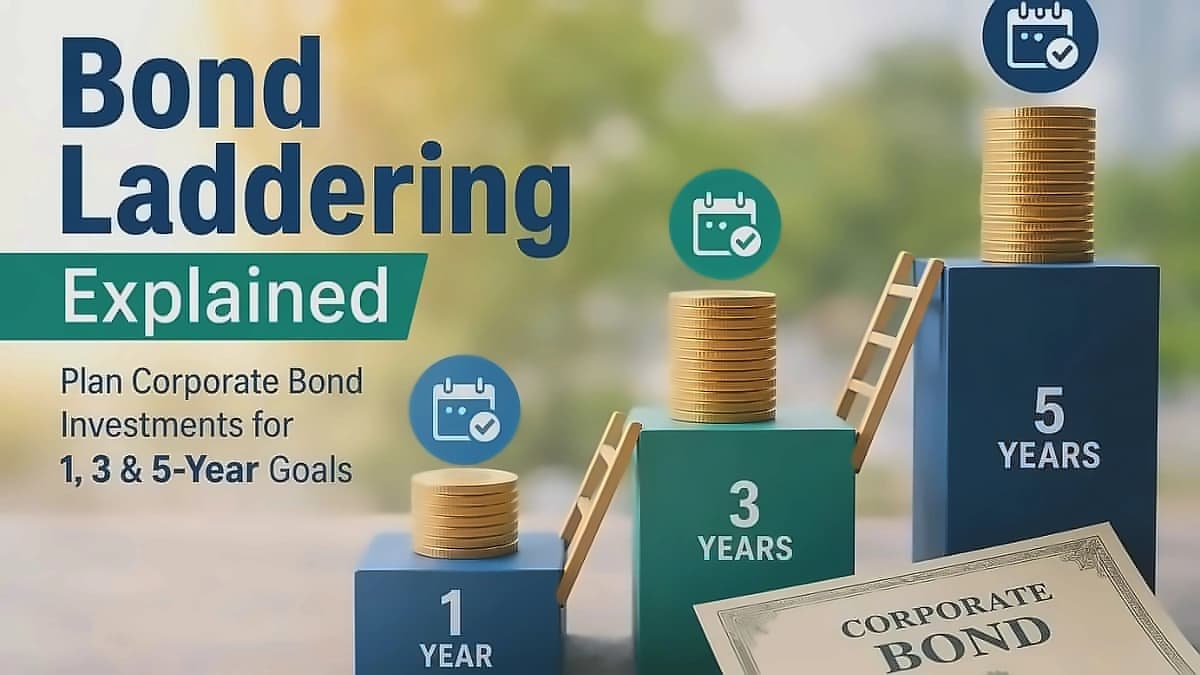
Bond laddering represents a systematic approach to fixed-income investing that addresses key risks associated with traditional bond investments. According to reports from Mint, this strategy involves splitting a lump-sum investment across several bonds or fixed deposits with different maturities, typically spaced one year apart. The approach allows investors to avoid the challenge of locking in for extended periods while missing potential rate increases, or maintaining shorter tenures that may result in reinvestment at lower rates during market downturns. As one plain-language guide explains, a ladder reduces single-point timing risk and improves cash flow planning by spreading that timing decision across many maturities instead of concentrating it in one.
Two features of the current market make laddering more attractive than it's been in a long stretch. According to recent fixed income analysis, the entire yield curve is currently offering income meaningfully above inflation, with a blended yield on a five-year Treasury ladder at roughly 4.38%, well above core inflation running near 2.8%. Additionally, credit spreads on investment-grade corporate bonds have compressed to historically tight levels, meaning the extra yield an investor picks up for taking on corporate credit risk is unusually thin right now. A Morningstar analysis published this year found that a properly constructed 30-year TIPS ladder can support an inflation-adjusted withdrawal rate of roughly 4.8% in retirement, compared to 3.9% for the best-performing traditional balanced portfolio strategy over the same study.
The primary advantage of bond laddering lies in its ability to spread reinvestment risk across multiple time periods. When rates rise, the maturing rung can be reinvested at the higher rate, while the remaining portfolio continues earning the older, higher rates. Conversely, if rates fall, the strategy protects against having to reinvest the entire amount at unfavorable terms. Additionally, the approach provides liquidity through regular cash flows, eliminating the need to break deposits early or sell bonds before maturity for planned expenses such as school fees or retiree household costs. The mechanism works by automatically capturing upside of rising rates a few percent of the portfolio at a time, while longer-dated rungs purchased at old, higher rates continue paying their original coupon to cushion against declines.
Investors can construct bond ladders using various fixed-income instruments including bank fixed deposits, government securities purchased through the RBI Retail Direct platform, corporate bonds, state development loans, or target maturity funds. According to Joydeep Sen, corporate trainer (financial markets) and author cited by Mint, target maturity funds offer particular advantages for small investors by holding bonds to fixed maturity dates without requiring individual bond purchases. The strategy involves investing smaller amounts across multiple instruments with different maturities, creating a systematic approach to managing interest rate risk. For the most conservative rungs, brokered CDs add FDIC insurance up to applicable limits, with competitive CD rates currently running around 4% APY for shorter maturities. Investment-grade corporate bonds can add incremental yield for investors comfortable with modest credit risk, though at today's tight spreads that extra yield is thinner than historically.
While bond laddering provides risk management benefits, it comes with trade-offs regarding return potential. The strategy typically doesn't offer the highest possible returns in any single year because part of the investment always sits in shorter-tenure instruments where yields are typically lower than longer-tenure bonds. The approach works best for investors seeking predictable income or those putting lump sums into fixed income without wanting to speculate on interest rate direction. Success depends on matching rung maturities to when money will be needed and maintaining investments in good-quality issuers. A bond fund offers instant diversification across many more issuers than most individual investors can practically replicate, professional ongoing credit monitoring, and same-day liquidity without needing to sell an individual bond into a potentially illiquid secondary market.