The Allahabad High Court has taken a prima facie view that banks cannot recover loan dues from life insurance proceeds when the widow was neither the borrower nor the guarantor. According to reports from Business Standard, the court directed the State Bank of India (SBI) to refund ₹17,29,999 deducted from Priti Singh's account, or explain through affidavits why the refund should not be made. A Bench of Justice JJ Munir and Justice Indrajeet Shukla was hearing the writ petition filed by the widow, who challenged the deduction made from her savings bank account maintained with SBI's Colonelganj Branch, Prayagraj. The matter has been listed for October 7, 2026, along with a report on the status of pleadings.
The case concerns Priti Singh, whose husband Ambesh Kumar Singh had taken a personal loan from SBI while working as Headmaster of a primary school in Uttar Pradesh's Kaushambi. As reported by Business Standard, the husband died in a road accident on June 7, 2025, without repaying the loan. After his death, insurance proceeds of ₹50 lakh were credited to Priti Singh's bank account, and SBI subsequently deducted ₹17,29,999 from that account to recover the outstanding loan amount. Singh challenged the recovery, stating she was neither a borrower nor a guarantor for the loan. The petitioner's husband had availed a personal loan from SBI while serving as Headmaster of a primary school at Balipur, Chail, Kaushambi.
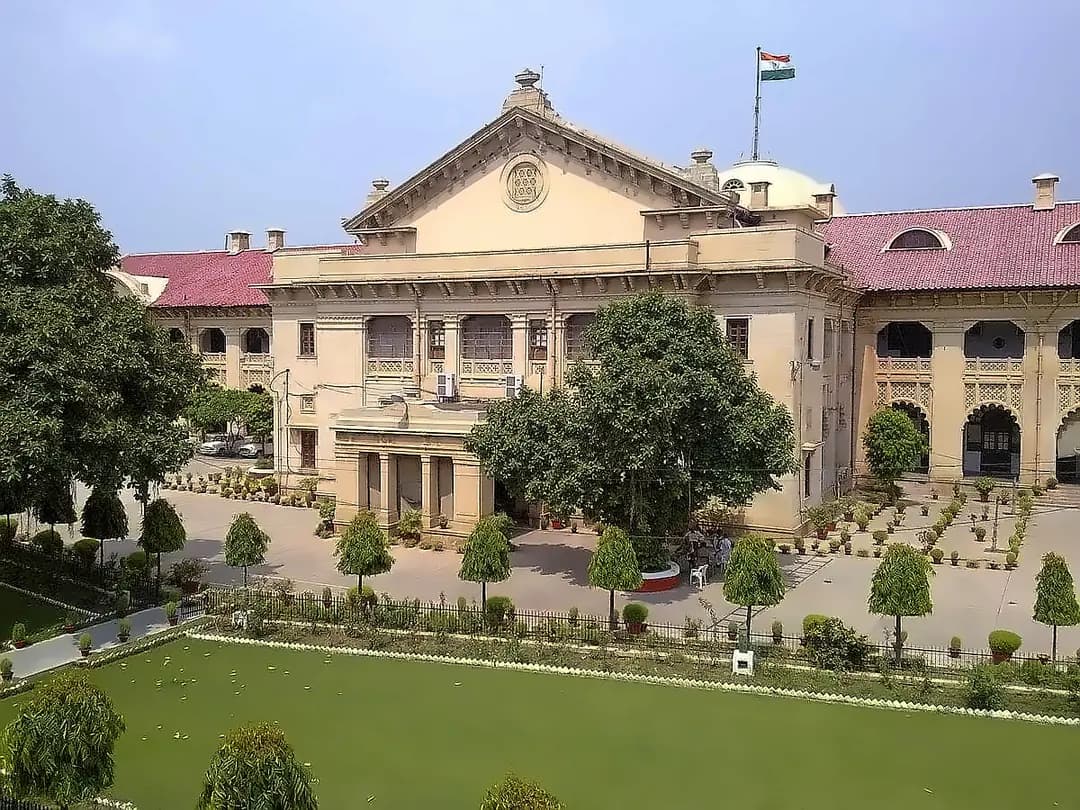
The SBI relied on Clause 18(iii) of the loan agreement signed by the deceased borrower on February 7, 2025, which gave the bank a right of set-off and lien over monies, accounts, securities, goods and other assets belonging to the borrower. According to Business Standard, the court acknowledged this clause was "very widely worded" and gave the bank a "paramount right to set off" and general lien over the borrower's assets. However, the judges found this clause did not prima facie cover insurance proceeds received by the widow after the borrower's death. The Bench observed that the clause was "very widely worded" but noted that, prima facie, the clause did not entitle SBI to recover the deceased borrower's dues from the insurance proceeds received by the widow.
The court emphasized that under a life insurance policy, proceeds become payable upon the death of the insured and "possibly, can never be owned by him." As reported by Business Standard, the court stated that the proceeds are not the deceased's money or property, but belong to the beneficiary. The judges noted that the proceeds are not an estate passed on to heirs, but a social security measure or benefit acquired by the deceased after his death. The bank's clause dealt with assets owned by the deceased while he was alive, not benefits under a life insurance policy that went to the nominee or beneficiary after his death. The Court remarked that such proceeds do not constitute the estate which the deceased passes on to his heirs, but rather constitute a "social security measure or a benefit" which the beneficiary acquires in their own right after the assured's death.
In its interim order, the high court directed the senior manager of SBI's Regional Office in Johnstonganj, Prayagraj and the branch manager of its Colonelganj branch to ensure the refund of ₹17,29,999 to Singh's account. According to Business Standard, they can file separate affidavits within two weeks explaining why the interim direction should not be made absolute. The High Court admitted the writ petition and granted the respondents two weeks to file their counter affidavits. The matter has been listed for October 7, 2026, along with a report on the status of pleadings. Meanwhile, while considering the petitioner's stay application, the Court issued an interim mandamus directing the bank officials to either ensure the refund or show cause by filing separate personal affidavits within two weeks.