The Income-tax Act provides nine key capital gains exemptions under Sections 54 to 54GB, allowing taxpayers to reinvest sale proceeds from capital assets within prescribed timelines. According to reports from Mint, these exemptions are available when capital gains or sale proceeds are reinvested in specified assets, with rules varying depending on the asset sold and the reinvestment option chosen. The exemptions are designed to encourage long-term investment and provide relief from capital gains tax liability. The Income-tax Act, 2025 has further enhanced these provisions by introducing Sections 82 to 86, which provide various deductions from capital gains where the consideration or capital gain arising from transfer of specified capital assets is reinvested in prescribed assets within the stipulated period. As per Business Standard, the rules have changed significantly since July 2024, with indexation no longer being the default method for calculating long-term capital gains on property, while resident individuals and Hindu Undivided Families (HUFs) can choose between 12.5% without indexation or 20% with indexation, whichever is lower for properties acquired before July 23, 2024.
Section 54 covers residential property sales where the exemption applies when selling a house or land attached to it. As reported by Mint, individuals and Hindu Undivided Families (HUFs) can claim this exemption if the property is sold after 24 months, with the new house purchased within one year before or two years after the sale, or constructed within three years. The exemption is limited to the amount of actual capital gains, the amount invested, or ₹10 crore, with a one-time option available to invest in two houses where capital gain does not exceed ₹2 crore. According to Business Standard, the exemption is subject to a ₹10 crore cap and focuses on the capital gain reinvested rather than requiring the taxpayer to reinvest the entire sale proceeds. The provisions under Sections 82 to 86 of the Income-tax Act, 2025, broadly cover reinvestment involving a residential house, with the amount of deduction depending upon the relevant section, nature of the original asset, amount reinvested and prescribed limits.
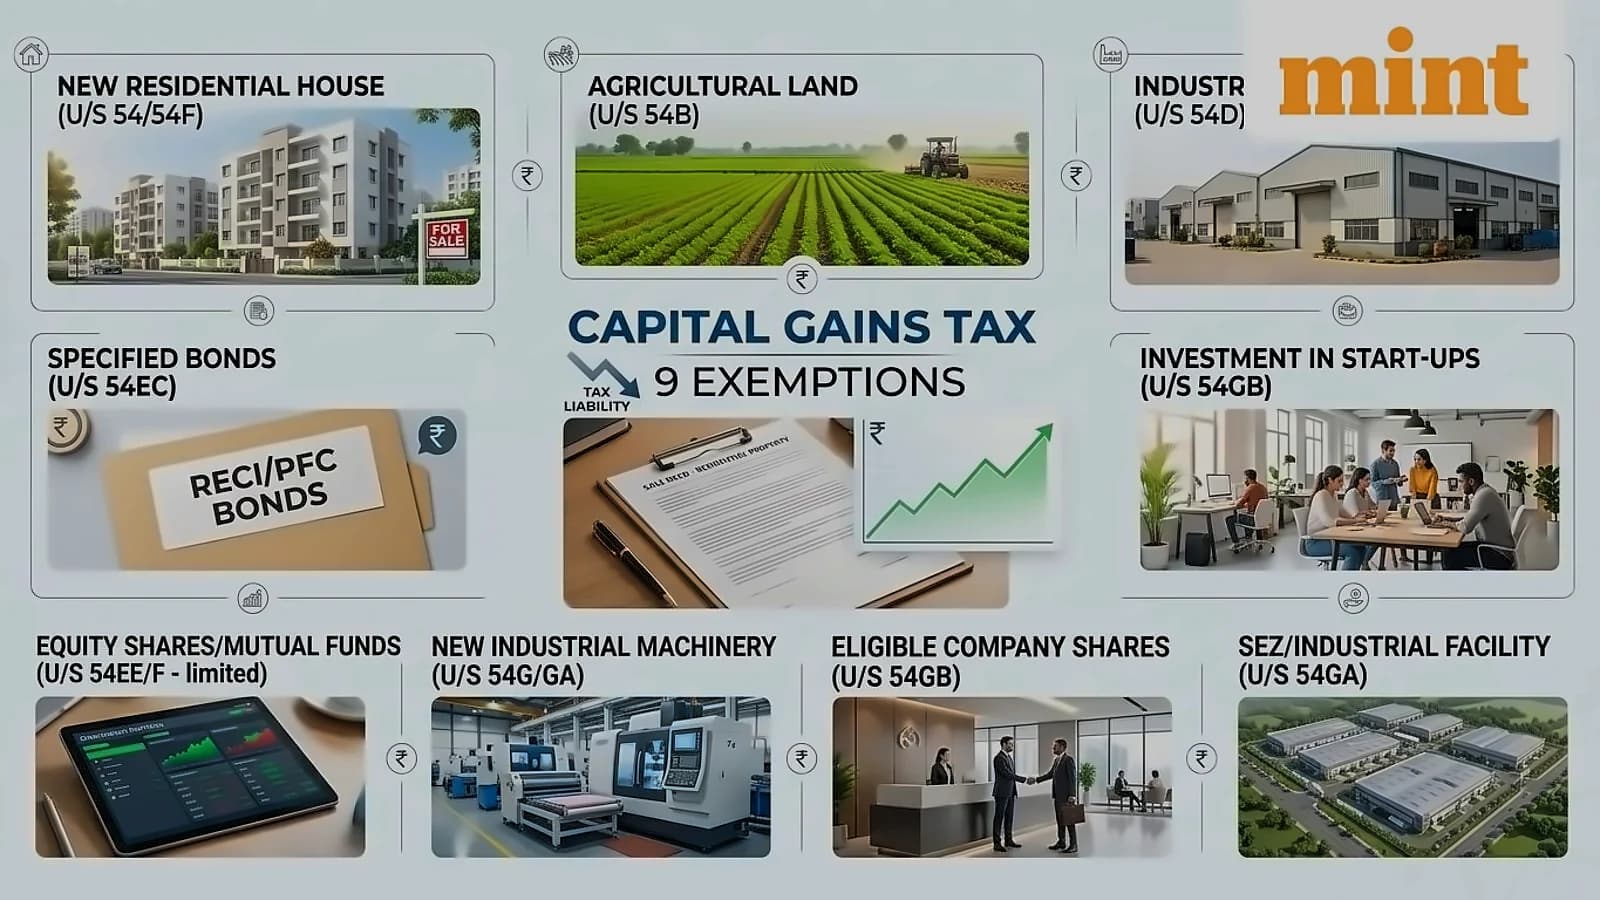
Section 54B specifically addresses agricultural land sales, requiring that the original land was used for agricultural purposes for at least two years before its sale by the taxpayer, their parents, or the HUF. According to Mint, individuals and HUFs can claim this exemption if the new agricultural land is purchased within two years after the transfer. The provision ensures that agricultural land remains in agricultural use while providing tax relief for legitimate land transactions. The amount of deduction depends upon the relevant section, nature of the original asset, amount reinvested and prescribed limits under the updated provisions.
Section 54G covers industrial undertaking relocations from urban areas, allowing capital gains to be used for shifting industrial assets to new locations. As reported by Mint, the section applies to plant, machinery, land, building or related rights used by an industrial undertaking in an urban area, with reinvestment required within one year before or three years after the transfer. Section 54GA extends this to Special Economic Zone (SEZ) relocations, covering assets used by industrial undertakings in urban areas that are shifted to SEZs within the same timeframe. These provisions are now covered under Sections 82 to 86 of the Income-tax Act, 2025, which provide various deductions from capital gains where the consideration or capital gain arising from transfer of specified capital assets is reinvested in prescribed assets within the stipulated period.
Section 54EC allows reinvestment in specified bonds issued by NHAI, REC, HUDCO or other Central Government-notified bonds, with investment required within six months of the transfer. According to Mint, the exemption is capped at ₹50 lakh and is subject to five-year holding conditions. Section 54EE provides similar options for long-term capital assets, covering specified long-term assets notified for funding eligible start-ups with investment generally required within six months and a ₹50 lakh cap. These provisions are now incorporated under Sections 82 to 86 of the Income-tax Act, 2025, which contain important provisions granting such deductions subject to fulfilment of specified conditions.
Section 54F addresses long-term capital assets other than residential houses, such as shares or mutual fund units, allowing reinvestment in residential property with specific conditions. As reported by Mint, the provision is linked to net sale consideration rather than capital gain, with eligible investment subject to a ₹10 crore ceiling and exemption calculated proportionally to the new house investment. The new house must be purchased within one year before or two years after the transfer, or constructed within three years, with exemption not applying if the taxpayer already owns more than one residential house. According to Business Standard, the exemption is based on the amount of capital gain reinvested, with a partial reinvestment leaving a larger taxable portion under Section 54F than under Section 54. The provisions under Sections 82 to 86 of the Income-tax Act, 2025, broadly cover reinvestment involving a residential house, with the amount of deduction depending upon the relevant section, nature of the original asset, amount reinvested and prescribed limits.
Section 54GB provides the most complex exemption, allowing reinvestment through eligible companies or start-ups that acquire qualifying new assets. According to Mint, this exemption is available to individuals and HUFs, subject to conditions on company type, taxpayer shareholding, and use of investment for new assets. The provision represents the most sophisticated reinvestment option, requiring careful consideration of corporate structure and regulatory compliance for maximum tax benefits. These provisions are now incorporated under Sections 82 to 86 of the Income-tax Act, 2025, which provide the most complex exemption allowing reinvestment through eligible companies or start-ups that acquire qualifying new assets.
When immediate reinvestment is not feasible, taxpayers can utilize the Capital Gains Account Scheme (CGAS) to preserve exemptions while completing qualifying reinvestment within statutory windows. As reported by Business Standard, taxpayers can park unutilised gains in CGAS before the return due date, which preserves the exemption while completing purchase or construction within allowed timeframes. Section 54EC bond investments cannot be routed through CGAS and must go directly into specified bonds within six months. The Income Tax Department has clarified that amounts deposited in CGAS before April 1, 2026 will be treated under the transition to the Income-tax Act, 2025, with unused portions becoming taxable when time limits expire. For Section 54, the broad statutory windows include purchase within one year before or two years after transfer, and construction within three years after transfer, with partial reinvestment resulting in proportionate exemption calculations.