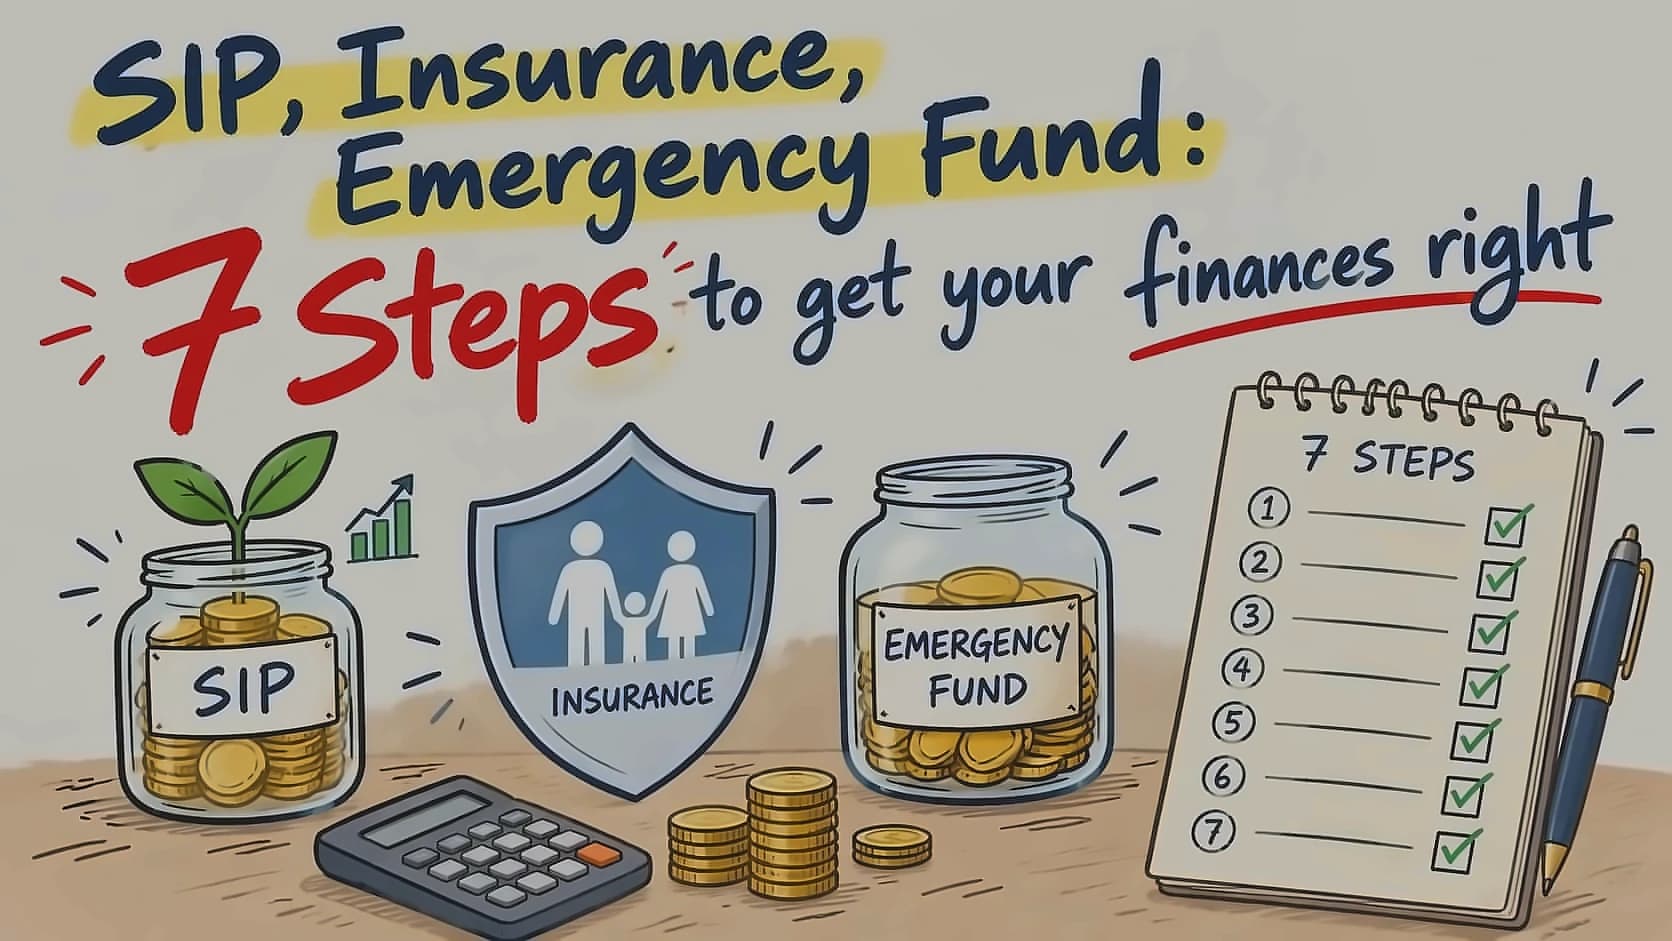
Financial experts recommend a systematic approach to building wealth through disciplined investing and adequate financial protection. According to certified financial planners Poonam Rangta and Pooja Bhinde, who spoke on a special Dussehra episode of Money Guru, investing doesn't require large amounts of money - the key is knowing what you want to achieve with your money, picking the right investment, and staying invested for the long term. As Rangta emphasizes, it's important to know your financial goals and how much risk you are comfortable taking, whether you're saving for a house, child's education, or retirement. However, she warns against simply copying what friends or family are doing, as everyone's situation and risk tolerance varies significantly.
Creating an emergency fund before starting investments is crucial for financial security. As reported by Rangta, investors should aim to save around 6 months of essential outgoings to handle unexpected costs, redundancy, and business issues. She recommends keeping long-term money in accessible instruments like savings accounts, recurring deposits, or liquid funds rather than investing it in something that requires time to access. This approach ensures financial stability during unforeseen circumstances, providing a safety net that can help cope with any unexpected costs or business issues that may arise.
Financial security requires adequate insurance coverage for both health and life protection. According to Bhinde, individuals should secure health insurance for themselves and their family, while those with dependents should consider term insurance policies worth 15-20 times their yearly income depending on their financial commitments. This approach ensures financial stability for dependents in case of unforeseen circumstances, with the amount varying based on individual financial obligations and family size. As Harsh Roongta from Fee-only Investment Advisors emphasizes, while those without financial dependants may not need term life insurance, health insurance and protection against disability and critical illness should be considered essential.
The investment approach varies significantly based on the time horizon of financial goals. As explained by Bhinde, if money is needed within 3 years, it's generally best to avoid equities due to unpredictable stock market returns. For goals within 2-5 years, investors can consider mixing equities and debt based on risk tolerance, while long-term goals like retirement benefit from equity investments for wealth creation. Bhinde emphasizes the importance of considering what you need the money for, as different time horizons require different investment strategies and risk profiles. Roongta cautions young investors against rushing into equity markets out of fear of missing out on compounding, arguing that the amount they can invest in the early years may be relatively small.
Small regular investments through SIP can generate substantial wealth over time. According to Rangta's example, investing ₹5,000 monthly using SIP could potentially turn into ₹50 lakh over 20 years with an annual return of 12%, though mutual fund returns are not guaranteed. She recommends increasing SIP amounts by 10% annually, which could potentially create a corpus of ₹1 crore over 20 years with the same 12% annual return. Rangta suggests using a step-up SIP strategy, where the monthly investment amount increases gradually over time, potentially creating a bigger corpus through compounding effects. Once loans and insurance are addressed, young earners should begin setting aside a portion of their income every month, even if the money initially goes into a fixed deposit or a liquid mutual fund, as emphasized by Roongta.
Effective financial planning involves diversified investments based on individual circumstances and future cost considerations. As suggested by Bhinde, investors should plan their investments considering age, goals, time frame, and risk tolerance, potentially creating portfolios containing equities, debt, and gold. Specific investments can be allocated for specific goals like house purchase, education, and retirement, with inflation consideration factored into future cost planning. She emphasizes the importance of knowing what your goals are and how much they'll cost in the future, taking inflation into consideration when making investment decisions. Roongta advises investors to seek personalised advice that takes their financial circumstances, goals and risk appetite into account, rather than relying on general online information that may not be suitable for every individual.