When borrowers complete their home loan repayment, it represents a significant financial milestone that requires strategic planning rather than immediate spending. According to reports from Mint, for example, if someone has a monthly income of ₹50,000 and their home loan EMI is ₹15,000, the freed-up amount should be used meaningfully rather than spent recklessly. The transition from regular EMI payments to having this additional monthly cash flow creates an opportunity to strengthen financial stability and prepare for future goals. As Mint emphasizes, proper thought, time and planning must be dedicated towards making the most of the freed-up amount, so that borrowers can meaningfully grow in life.
The first priority should be to strengthen the emergency fund using the saved EMI amount. As reported by Mint, the emergency fund should cover approximately six months of essential expenses, including household costs, school fees, insurance premiums, and day-to-day expenses. This amount may need to be higher for borrowers with dependents, variable income, or limited job security. The fund should be kept in a relatively liquid, easily available, and low-risk investment option to ensure accessibility when required. Mint notes that becoming debt-free from a home loan does not necessarily mean all debt has been cleared, and borrowers should review outstanding credit card balances, personal loans, vehicle loans, and other liabilities before redirecting funds towards growth investments.
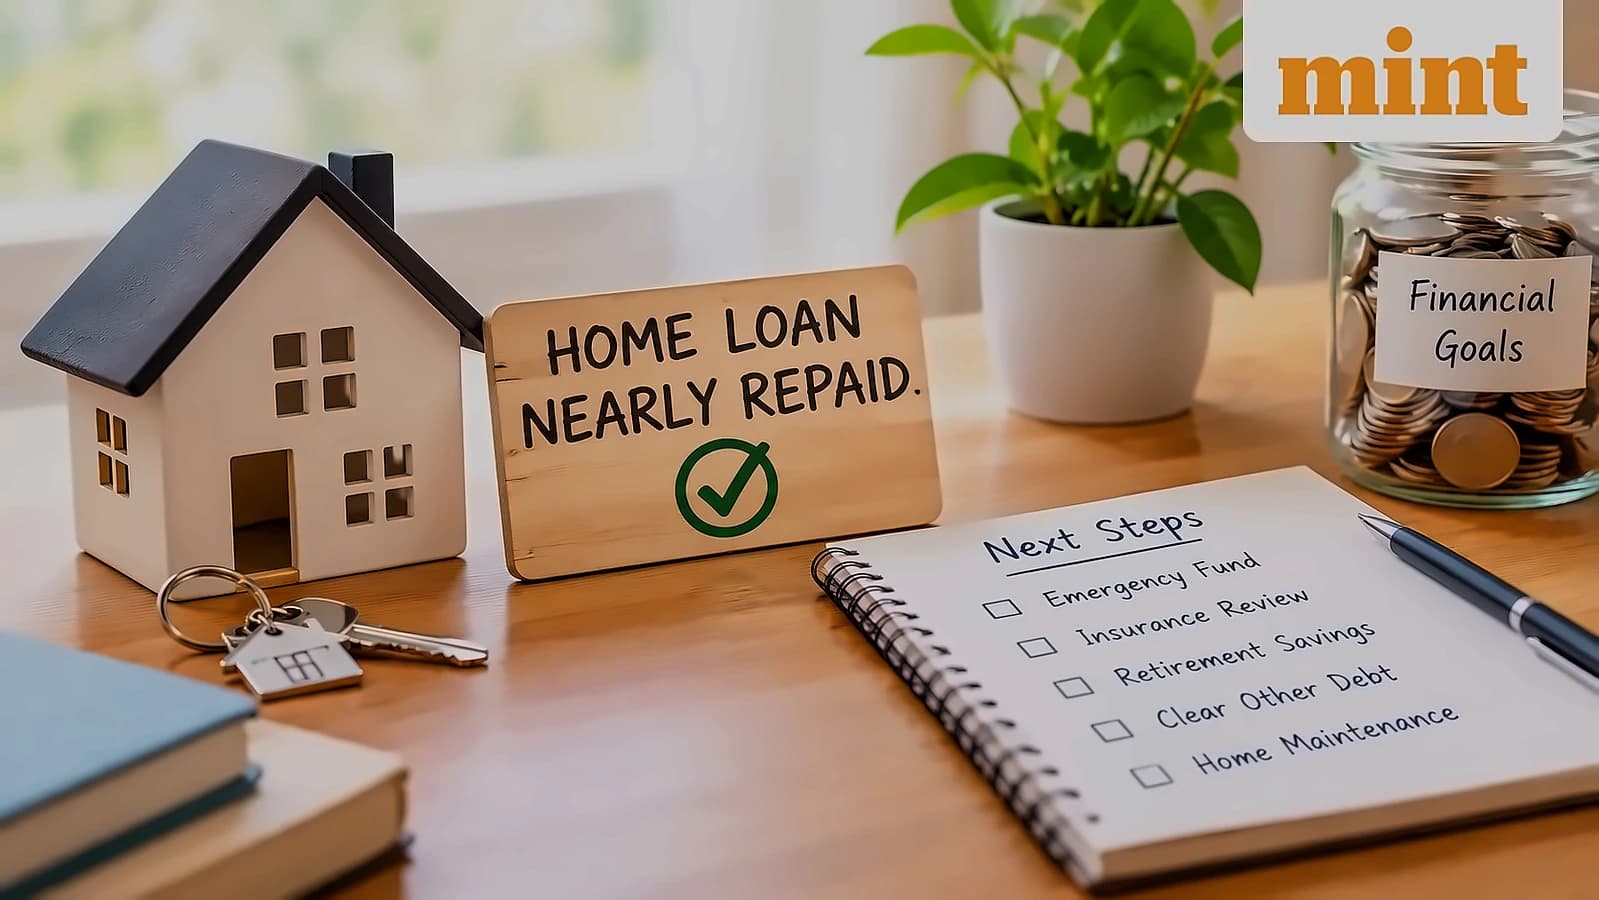
The end of a home loan provides an appropriate time to reassess insurance coverage across multiple categories. According to Mint, borrowers should check whether their term insurance is sufficient to support their family if they are no longer around, and review their health insurance, especially if medical costs or family responsibilities have increased since taking out the home loan. If the home loan included loan-protection insurance, borrowers should confirm whether the policy continues after loan closure and understand its terms. Additionally, borrowers should collect the properly stamped lender's no-dues certificate from the relevant authorities, along with the loan-closure documents, and check that the lender's charge on the property has been removed from the relevant records wherever applicable.
Once the EMI stops, the same amount can be redirected towards long-term financial goals, particularly retirement savings. As reported by Mint, borrowers may consider increasing contributions to retirement-oriented options such as EPF, voluntary provident fund, PPF, NPS, or suitable stocks or mutual fund investments depending on their risk profile and investment horizon. Automating this transfer can help ensure regular investment rather than absorption into lifestyle expenses. Mint emphasizes that once the EMI stops, the same amount can be redirected towards long-term financial goals such as building a more robust and comprehensive retirement corpus, ensuring that individuals can build a more robust and comprehensive retirement corpus.
Using the freed-up cash flow to clear costly debt may be more beneficial than immediately increasing investments, particularly if expensive debt remains. According to Mint, borrowers should review outstanding credit card balances, personal loans, vehicle loans, and other liabilities. Additionally, homeowners should continue setting aside money for repairs, renovations, property taxes, society charges, insurance, and other maintenance expenses through a separate home-maintenance fund to prevent these costs from disrupting other financial goals. Mint notes that there is no single rule that applies to everyone, and when faced with such a situation, it is wise to seek professional guidance to ensure meaningful personal financial planning and long-term economic well-being.